


Grid Upgrade Deal Might Change The Case For Investing In Itron Stock (ITRI)
- Itron reported that Duquesne Light Company expanded its use of Itron’s Grid Edge Intelligence to move from first generation AMI to a more advanced AMI 2.0 setup, including an initial rollout of 20,000 distributed intelligence endpoints for better outage detection and operational insight.
- The decision to build on Duquesne Light’s existing OpenWay network rather than replace it outright highlights utility demand for grid modernization that reuses installed infrastructure, manages upfront capital, and adds software and intelligence over time instead of through one large hardware refresh.
- The next area of focus is how Itron’s investment narrative around grid edge intelligence and software-rich Outcomes intersects with Duquesne’s AMI 2.0 upgrade.
Itron Investment Narrative Recap
Itron is a grid modernization story. To stay invested, you need to believe utilities keep moving from basic AMI to software heavy grid edge intelligence and that Itron converts its US$4.4b pipeline into deployments despite uneven project timing. The Duquesne Light expansion and PG&E wildfire work both lean into that same operational theme.
The near term catalyst still centers on how quickly delayed Networked Solutions programs and AMI 2.0 rollouts convert backlog into revenue and support margins near 40%. The main risk remains slippage in large utility projects or regulatory approvals, which could extend timing gaps and make earnings more sensitive to schedule changes.
The PG&E wildfire collaboration is the clearest reference point for what Duquesne Light is buying into. Thousands of grid edge sensing devices in high fire risk areas show Itron’s Grid Edge Intelligence being used for safety critical fault detection, real time classification and more targeted crew dispatch, not just billing data.
For you, that tie in matters because it reinforces the Outcomes and Resiliency Solutions angle that underpins higher margin software and services. Execution risk stays real, given capital pressure at utilities and long approval cycles, but each scaled deployment in wildfire prevention or feeder reliability gives Itron more proof points to support future AMI 2.0 decisions.
Itron's current earnings are US$274.0 million, with analysts forecasting earnings of US$339.3 million by 2029. This implies an earnings increase of about US$65 million and forecast revenue of US$2.7b that aligns with an assumed 6.1% yearly revenue growth rate.
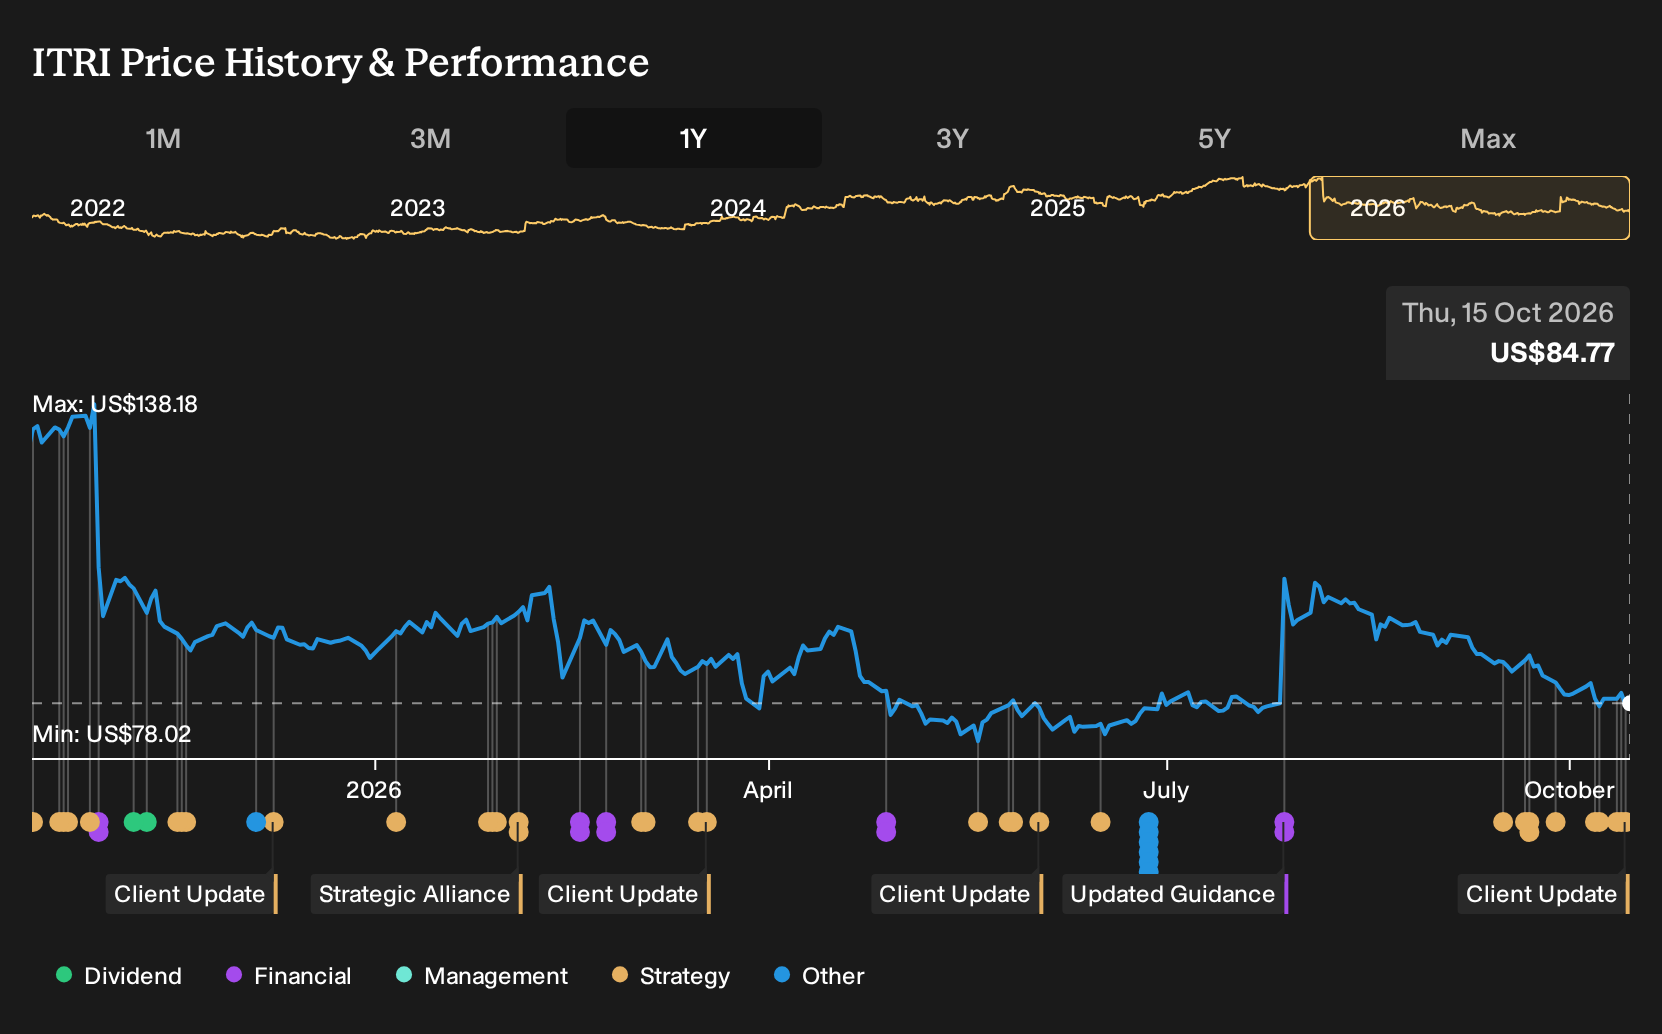
Uncover why Itron's fair value indicates a 53% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$71.5 to US$129.6, so some retail investors see Itron as heavily discounted while others price in a far richer outcome. Set those opinions against project deferrals, regulatory friction and AMI 2.0 demand as potential swing factors, then explore the full range of community views yourself.
Explore 3 other Itron fair value estimates, including one that suggests a potential upside of up to 53% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Itron research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Itron. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Itron's overall financial health at a glance.
Looking For More Ideas Beyond Itron?
If the Itron story has you thinking about where to look next, a focused screener can help you quickly narrow the universe to companies that better fit your risk, income, or quality preferences.
- If resilience matters most to you, start with a basket of companies screened for stronger balance sheets and healthier fundamentals through our list of solid balance sheet and fundamentals (25 results).
- For readers who want quality at a reasonable entry point, filter for stocks that pair solid business profiles with potentially attractive pricing using the 33 high quality undervalued stocks.
- Income focused investors can zero in on companies prioritizing cash returns to shareholders by running the 8 dividend fortresses and seeing which yields align with their goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com