


European Undervalued Small Caps With Insider Activity To Explore In October 2026
In October 2026, the European market has been navigating a landscape marked by renewed Middle East tensions, a more hawkish stance from the European Central Bank, and mixed industrial data across the eurozone. Despite this volatility, small-cap stocks in Europe continue to present intriguing opportunities for investors who are attentive to insider activity and potential undervaluation. Identifying promising stocks often involves examining those with strong fundamentals that can withstand broader economic pressures while capitalizing on unique growth prospects within their sectors.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Volati | 10.1x | 0.2x | 36.76% | ★★★★☆☆ |
| Hanza | 31.3x | 1.3x | 39.04% | ★★★★☆☆ |
| Franchise Brands | 26.8x | 2.0x | 48.16% | ★★★★☆☆ |
| Saniona | 7.5x | 3.2x | 31.02% | ★★★★☆☆ |
| Invisio | 46.9x | 6.1x | 34.72% | ★★★☆☆☆ |
| Nyab | 19.0x | 0.9x | 32.01% | ★★★☆☆☆ |
| Domino's Pizza Group | 14.8x | 1.2x | -1.00% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 20.17% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -225.76% | ★★★☆☆☆ |
| Linc | 11.9x | 12.4x | 35.76% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Genuit Group (LSE:GEN)
Simply Wall St Value Rating: ★★★★★★
Overview: Genuit Group is a UK-based company specializing in sustainable water, climate, and ventilation management solutions with a market cap of approximately £1.24 billion.
Operations: The company's revenue is primarily generated from its Climate Division, with a notable segment adjustment contributing significantly to the overall figures. The gross profit margin has shown variability, reaching up to 44.48% in recent periods. Operating expenses are substantial, with significant allocations towards sales and marketing as well as general and administrative costs.
PE: 21.0x
Genuit Group, a player in the European market, has seen mixed financial results recently. For the first half of 2026, sales increased to £307.8 million from £297.8 million a year prior, but net income fell to £13 million from £23.9 million. Despite this dip in profitability and lower profit margins at 5.6% compared to last year's 8.4%, insider confidence is evident with recent share purchases by company insiders earlier this year, suggesting belief in future growth potential as earnings are forecasted to grow annually by about 20%. The company maintains its interim dividend at 4.2 pence per share and aims for progressive dividends over time despite relying solely on external borrowing for funding.
- Take a closer look at Genuit Group's potential here in our valuation report.
Evaluate Genuit Group's historical performance by accessing our past performance report.
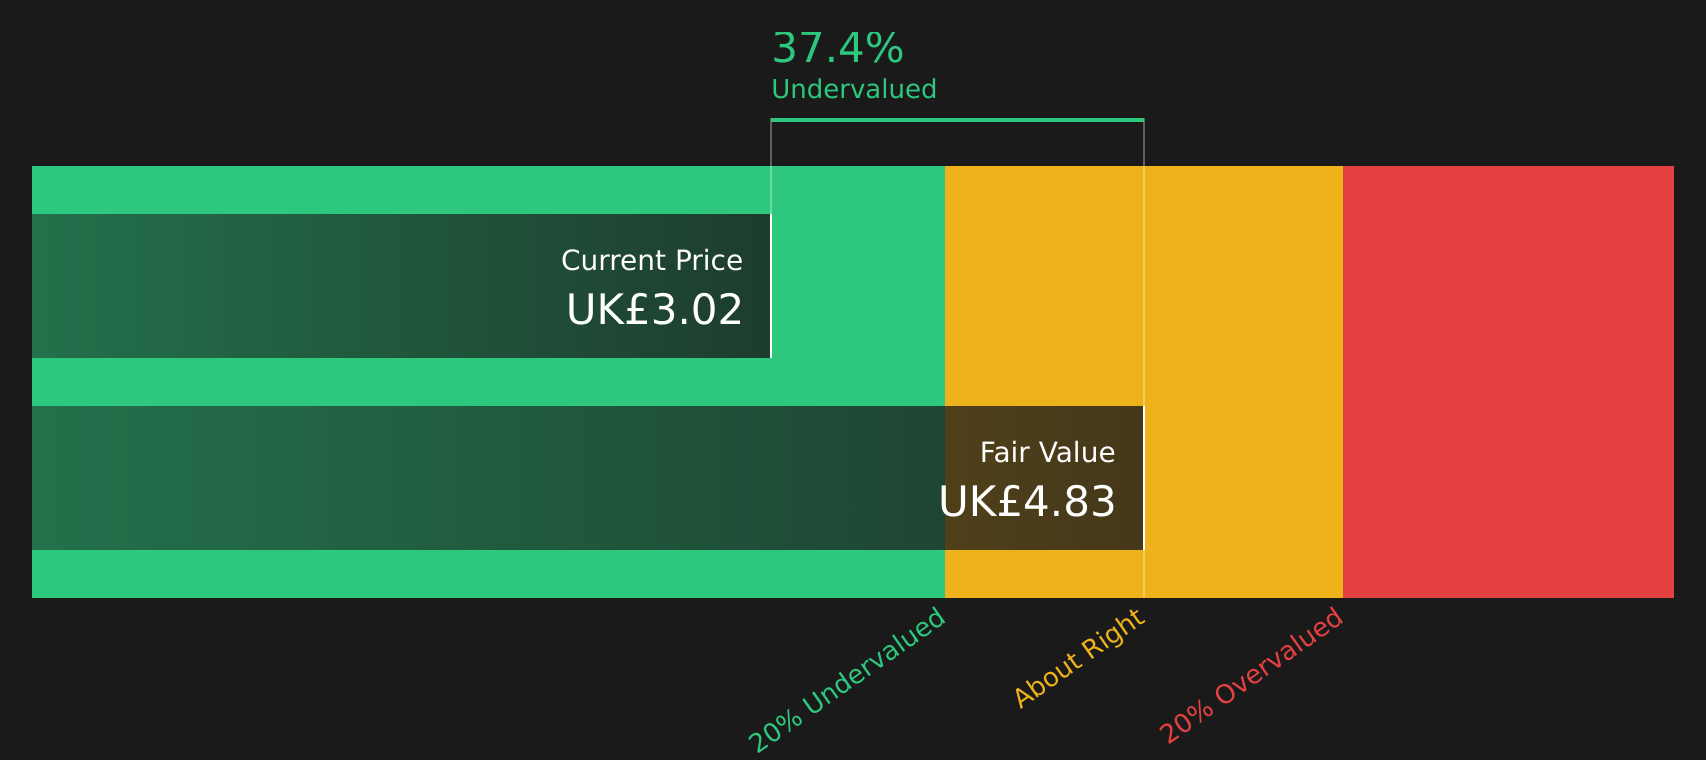
Travis Perkins (LSE:TPK)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Travis Perkins is a leading UK-based company specializing in the supply of building materials and home improvement products, with operations primarily through its Merchanting and Toolstation segments, and a market cap of approximately £1.71 billion.
Operations: The company generates revenue primarily from its Merchanting and Toolstation segments, with Merchanting contributing significantly more. Over the periods analyzed, there is a notable fluctuation in net income margin, which ranges from -3.86% to 5.25%. The gross profit margin also varies considerably, peaking at 38.50% and reaching as low as -9.78%. Operating expenses include significant allocations for sales and marketing efforts alongside general and administrative costs.
PE: -7.3x
Travis Perkins, operating in the building materials sector, shows potential despite recent revenue declines of 1.6% for Q3 and 1.8% year-to-date as of September 2026. The company’s earnings are forecast to grow significantly by 89% annually, indicating strong future prospects. Insider confidence is evident with recent share purchases, reflecting belief in its long-term value. While external borrowing poses a risk, Travis Perkins remains an intriguing player among European small caps due to its growth potential and industry position.
- Unlock comprehensive insights into our analysis of Travis Perkins stock in this valuation report.
Review our historical performance report to gain insights into Travis Perkins''s past performance.
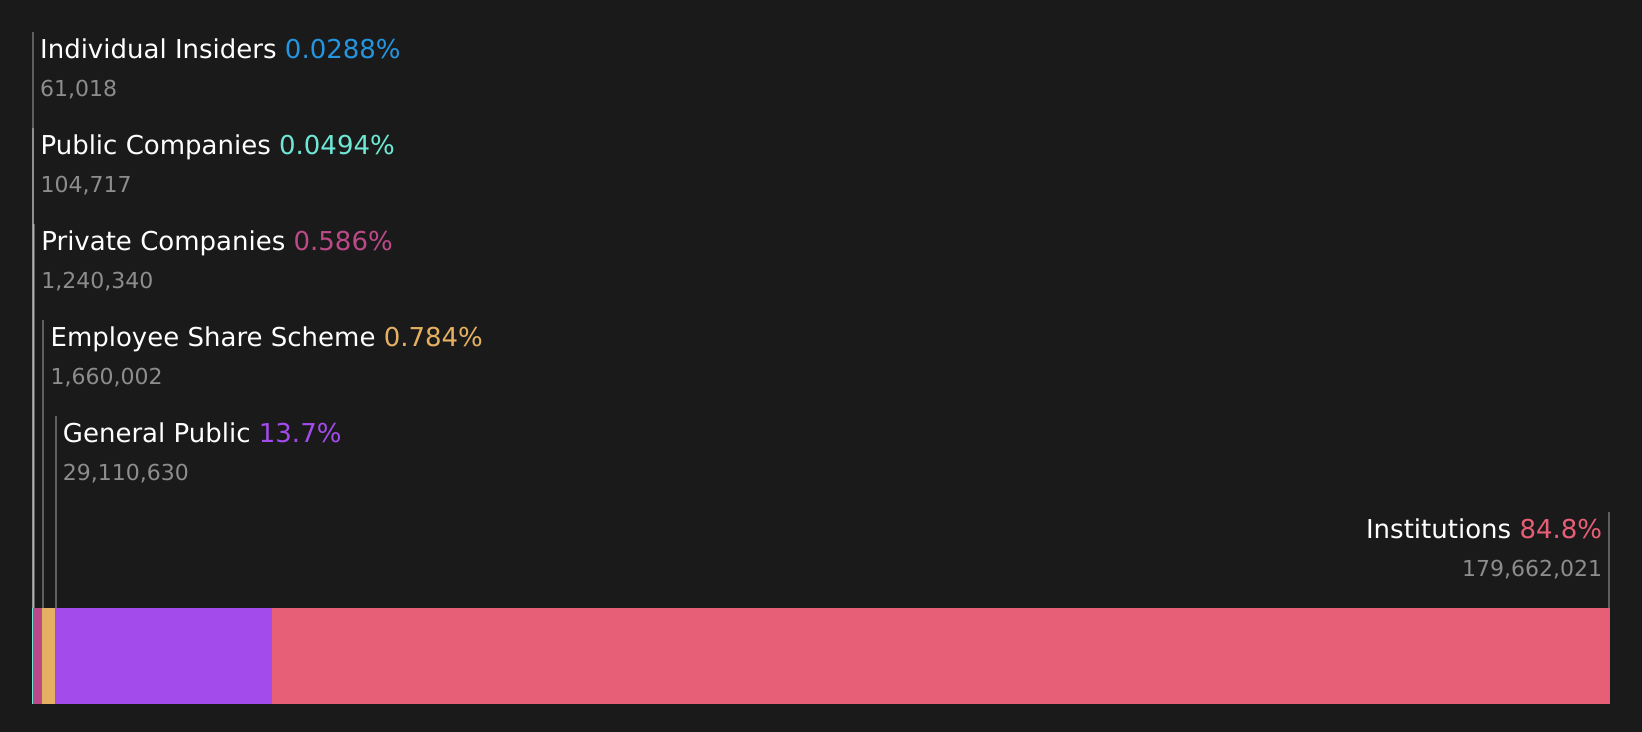
Bonesupport Holding (OM:BONEX)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Bonesupport Holding is a Swedish company specializing in the development and commercialization of injectable bioceramic bone graft substitutes, with a market capitalization of SEK 3.45 billion.
Operations: Bonesupport Holding generates revenue primarily from its pharmaceuticals segment, which reached SEK 1.29 billion. The company's cost structure includes cost of goods sold (COGS) at SEK 102.32 million and operating expenses of SEK 874.70 million, with significant allocations to sales and marketing as well as research and development. The gross profit margin stands at 92.05%.
PE: 78.4x
Bonesupport Holding is drawing attention as a promising small company with growth potential, highlighted by insider confidence through Director Björn Odlander's purchase of 4,000 shares worth approximately SEK 790,000 in September 2026. The company's innovative CERAMENT V product has made strides with the FDA and is supported by clinical studies like SOLARIO, published in NEJM. With sales rising to SEK 355 million in Q2 2026 from SEK 284 million the previous year, Bonesupport's regional expansion into Australia and New Zealand further underscores its strategic growth ambitions.

Summing It All Up
- Click through to start exploring the rest of the 36 Undervalued European Small Caps With Insider Buying now.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com