


What Astera Labs (ALAB)'s AI Infrastructure Launch Means For Shareholders
- Astera Labs recently launched Orion, a modular rack-scale reference design for AI inference, and expanded its Aries PCIe 7 signal conditioning portfolio, targeting hyperscalers, neoclouds, OEMs, and enterprises that need flexible, production-grade AI data center connectivity.
- The combination of compute agnostic rack architectures and a broad PCIe 7 copper to optical platform strengthens the link between Astera Labs’ hardware and its COSMOS software, which can deepen customer reliance on its ecosystem across multi-rack AI deployments.
- We will now assess how Astera Labs’ compute agnostic Orion rack design could influence the existing investment narrative around AI infrastructure.
Astera Labs Investment Narrative Recap
To own Astera Labs, you need to believe AI data centers keep demanding more flexible, open standard connectivity and that this business can keep a meaningful role in that buildout. The key near term swing factor is how quickly its newer rack level and fabric products translate into scaled deployments with hyperscalers and neoclouds. The Orion launch is directionally aligned with that, but it does not instantly change near term demand.
The biggest risk is still concentration and technology churn. A few cloud customers drive a lot of volume, and larger chipmakers are pushing their own fabrics and interconnect standards. Orion’s compute agnostic pitch may help relevance, yet it also raises execution pressure around interoperability, delivery timing into 2027, and capital intensity for supporting full rack solutions.
The Orion rack scale reference design is the clearest operational signal in this news flow. It ties Astera Labs hardware to COSMOS software in a single composable system that reaches from boards and trays up to multi rack pods. For the existing narrative around Scorpio switches and UALink, Orion appears designed to make those pieces easier for customers to deploy at scale.
For catalysts, Orion’s scheduled availability starting in the first quarter of 2027 matters because it sets a concrete window when design activity today could convert into revenue later. The risk is that hyperscalers or OEMs lean harder into rival fabrics or more integrated solutions before Orion racks ship in volume. In that case, the company would be working to defend attach rates in a more competitive AI infrastructure market.
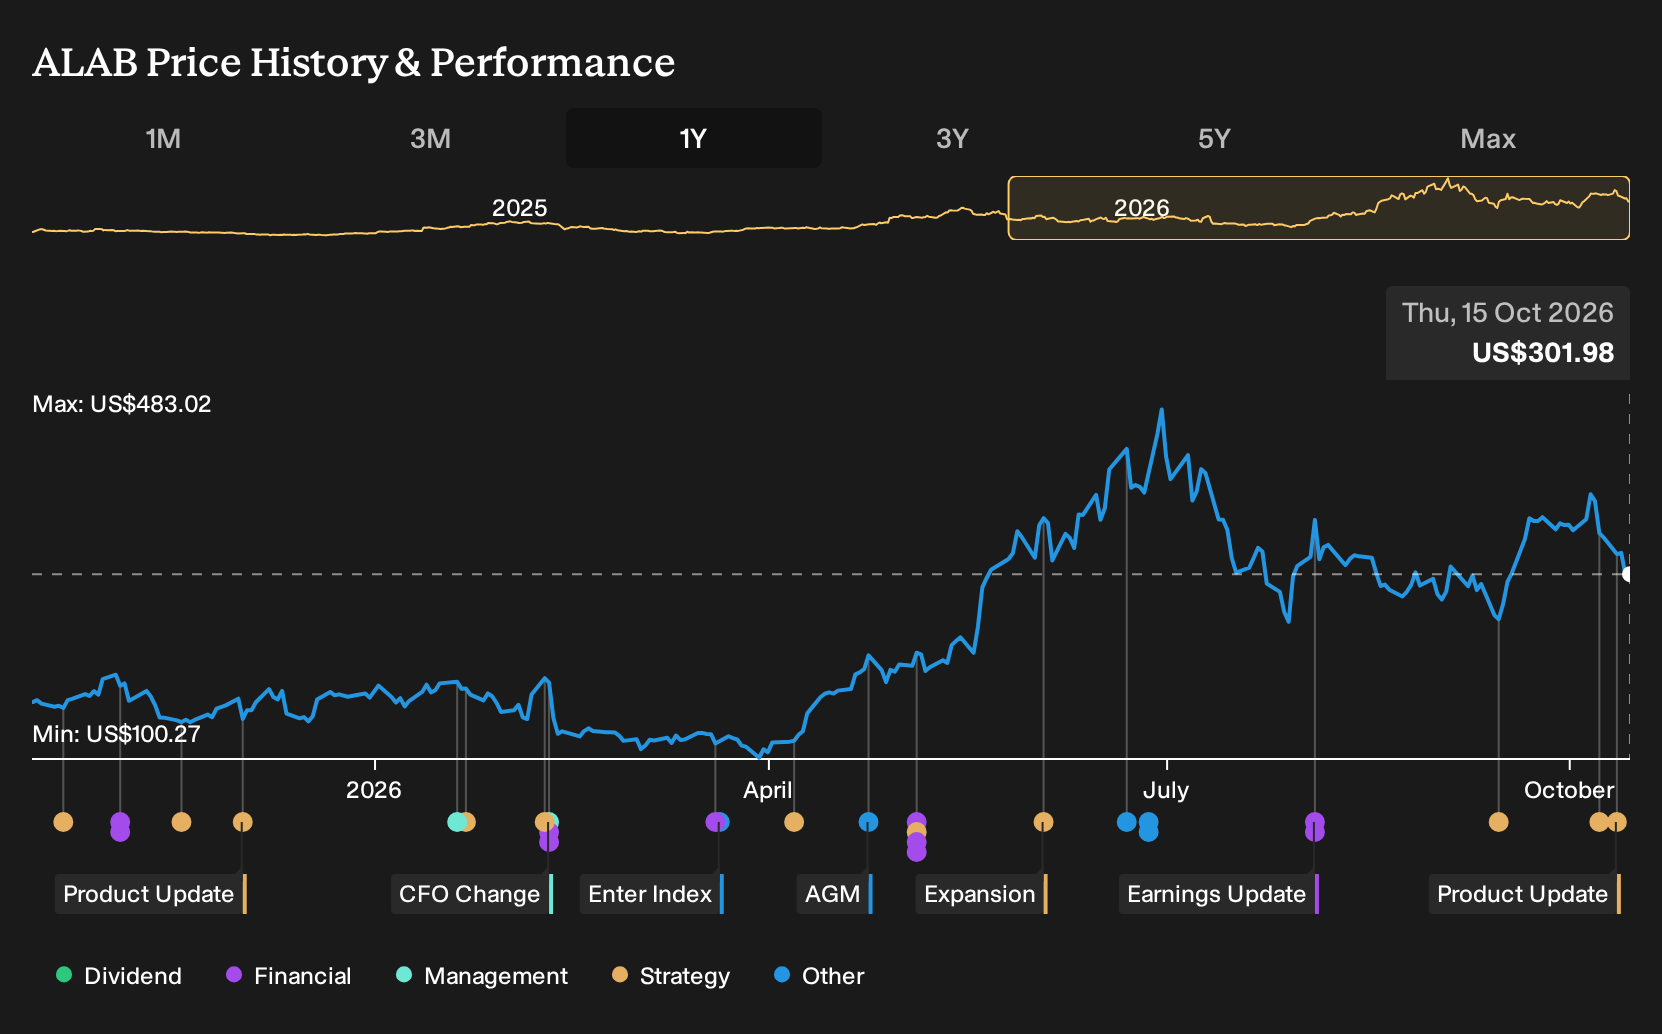
Astera Labs' current consensus narrative points to revenues of US$3.8b and earnings of US$1.1b by 2029. That profile assumes revenue growth of 46.3% per year and an earnings increase of roughly 3x from US$369.5m today.
Uncover why Astera Labs' fair value indicates a 30% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view zooms in on margin pressure. The most pessimistic analysts see Astera Labs earning about US$707.7m by 2029 on roughly US$3.3b of revenue and a 21.1% margin, well below consensus. Those estimates were set before the Orion news, so you may see them shift as rack scale plans sink in.
Explore 7 other Astera Labs fair value estimates, including one that suggests as much as 26% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Astera Labs research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Astera Labs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astera Labs' overall financial health at a glance.
Looking for more investment ideas beyond Astera Labs?
If the Astera Labs story has you thinking about where else AI infrastructure demand and cash flow resilience might intersect, the Simply Wall St Screener can help you cast a wider net without losing focus on quality fundamentals.
- For investors who care most about valuation support and financial strength, the 33 high quality undervalued stocks can highlight companies where cash generation and balance sheets line up with a more conservative entry profile.
- If capital preservation and a smoother ride matter to you, the 32 resilient stocks with low risk scores can surface businesses with lower risk scores that may better fit a steadier portfolio core.
- When you want to go beyond the usual watchlists and seek fresher ideas, the 20 high quality undiscovered gems can spotlight underfollowed stocks that still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com