


How Investors May Respond To Yum! Brands (YUM) Pizza Hut Sale Plan
- Yum! Brands is reshaping its business by planning the sale of Pizza Hut, deepening long term supplier relationships, and expanding AI driven tools such as Taco Bell’s automated drive thru ordering across hundreds of locations.
- The shift toward unified supplier partnerships and higher margin digital orders at KFC and Taco Bell reflects a focus on restaurant level economics and operational efficiency, rather than on footprint growth alone.
- We will now look at how Yum! Brands' refocused portfolio and AI driven operations could reshape the existing investment narrative.
Yum! Brands Investment Narrative Recap
To own Yum! Brands, you need to be comfortable with a business that leans heavily on its franchise model, Byte digital platform, and AI tools to keep restaurant level returns healthy even when traffic is choppy. The key near term swing factor is Taco Bell and KFC digital throughput, because higher margin online orders and better cost control can offset weaker Pizza Hut earnings while the divestiture plays out.
The biggest risk right now is that U.S. demand softness and Cyclospora related traffic pressure at Taco Bell linger, while heavy investment into AI, digital infrastructure, and supplier unification does not translate into the expected efficiency gains. Recent earnings forecast cuts tied to weaker Taco Bell sales and Pizza Hut disposal highlight how execution missteps on these projects could weigh on restaurant profitability and keep earnings under strain.
The most relevant recent update for this story is the expansion of Omilia Voice AI in Taco Bell drive thrus and Yum! Brands’ broader AI rollout. Management links this to higher employee retention because automated ordering removes some repetitive tasks, which can help with staffing stability and training costs at the store level.
For you as an investor, the operational question is whether these AI tools and unified supplier agreements actually lift order accuracy, speed, and digital mix enough to offset near term headwinds in Taco Bell traffic and Pizza Hut earnings drag. The same technology push that underpins the growth catalyst also carries execution risk if adoption slows or if the systems fail to support the expected restaurant level economics.
Yum! Brands' current analyst narrative connects a forecast for revenues of US$9.7b and earnings of US$2.1b by 2029 with an assumed 3.6% yearly revenue growth rate and an earnings decrease of US$0.1b from current earnings of US$2.2b.
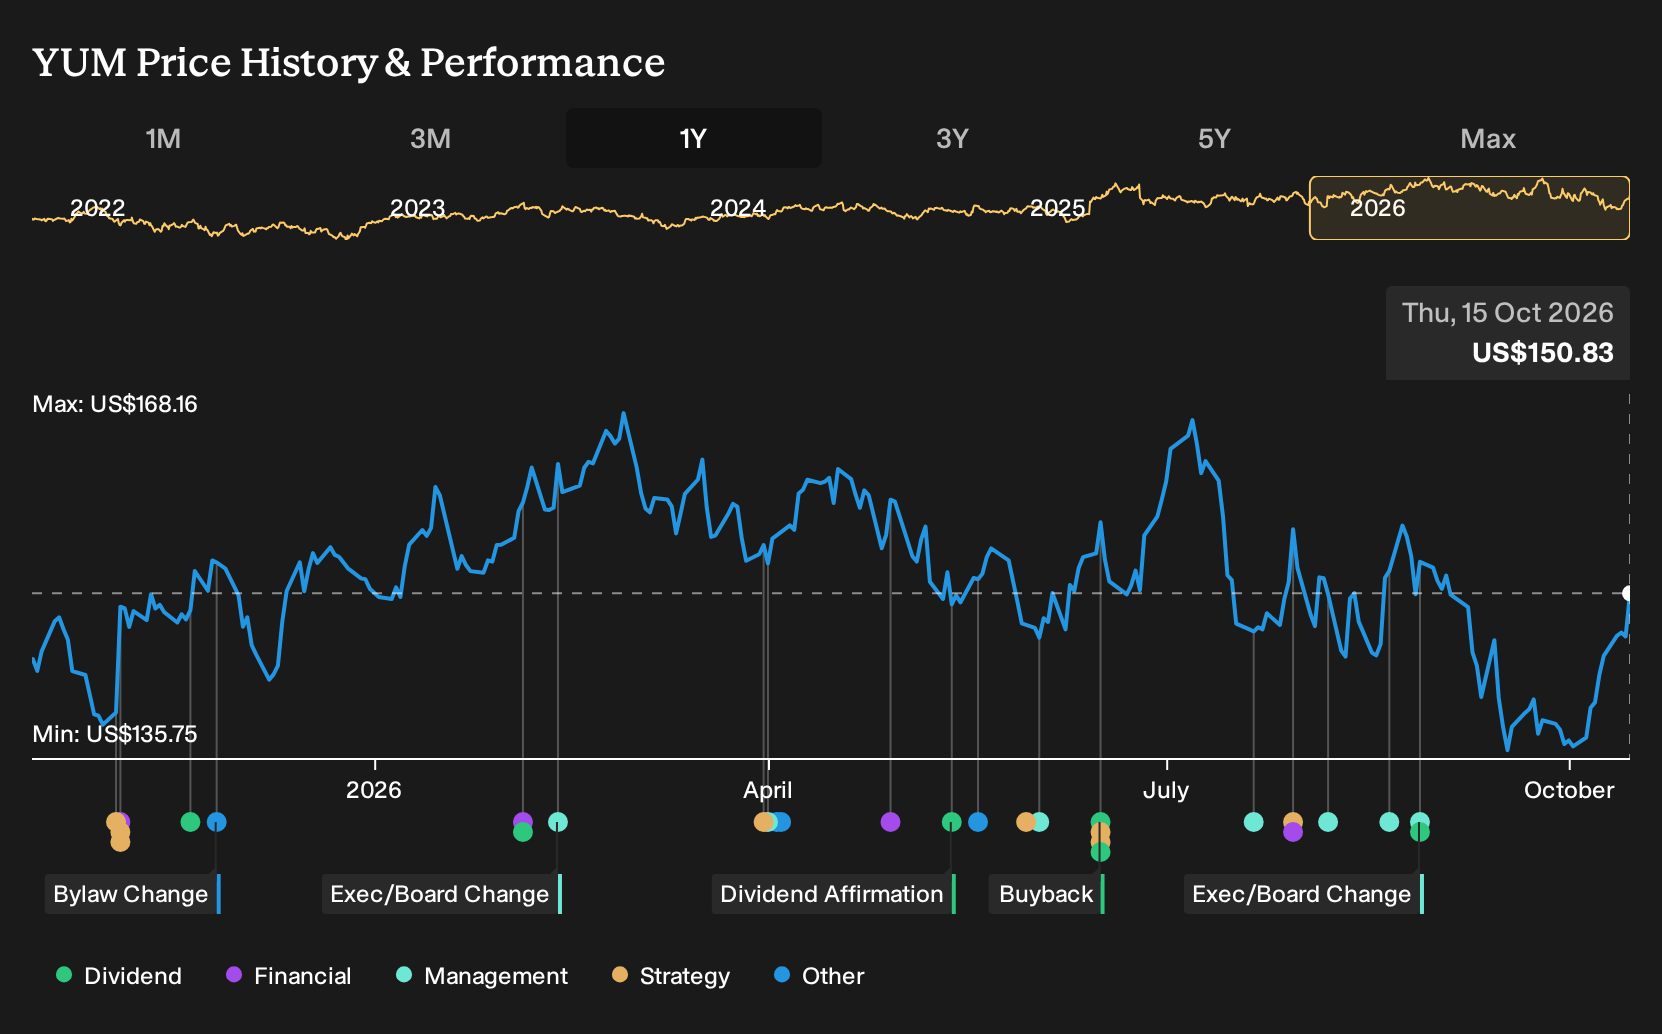
Uncover why Yum! Brands' fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community cluster between about US$171 and US$183, so you are looking at a tight band rather than wild disagreement. Those views were formed before the latest Taco Bell traffic weakness and Pizza Hut sale plans, which could reshape how different investors judge Yum! Brands’ earnings resilience and AI driven upside.
Explore 3 other Yum! Brands fair value estimates, including one that suggests it could be worth just $171.06.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Yum! Brands research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Yum! Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yum! Brands' overall financial health at a glance.
Looking For More Ideas Beyond Yum! Brands?
Once you have a view on Yum! Brands, it can help to compare that thesis with other opportunities that share similar quality traits or different risk profiles. The Simply Wall St Screener lets you scan for these kinds of stocks quickly so you can build a watchlist that fits your goals instead of relying on a single story.
- If you want to focus on steadier profiles with a tilt toward capital preservation, consider resilient candidates from the 32 resilient stocks with low risk scores.
- For readers who prefer quality at a reasonable price, filter for potential bargains using the 33 high quality undervalued stocks.
- If you are hunting for strong fundamentals and balance sheet strength to support long term compounding, start with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com