


Is Newmont (NEM) Undervalued On Earnings Hopes And Newcrest Synergies?
Upcoming earnings and Newcrest integration move into focus
Newmont (NEM) heads into its upcoming October 22 earnings release with expectations for higher quarterly earnings and revenue, as investors weigh Newcrest Mining acquisition synergies against ongoing operational and capital spending risks.
Recent trading has been choppy for Newmont, with the 1-month share price return down 6.76% even as the 90-day move is up 29.09% and the year-to-date share price return sits at 14.39%. That short-term pullback follows a very strong 3-year total shareholder return of 210.97% and 5-year total shareholder return of 132.38%. This pattern indicates that momentum has cooled ahead of earnings as investors reassess both the potential upside from Newcrest integration and the risks around higher capital spending and mine performance.
Compare Newmont's earnings setup and acquisition story with a curated list of other gold producers that could be gearing up for their own breakouts via 35 elite gold producer stocks.
Newmont now appears to be a much larger, more diversified miner after acquiring Newcrest. However, the share price has only recently cooled off from a strong run. Is this still a quality business at a fair price, or is it already fully priced in?
Most Popular Narrative: 16% Undervalued
Newmont's most followed narrative pegs fair value at $137.07, which sits above the recent $115.79 close. This suggests the market is treating Newcrest integration, capital returns, and gold exposure with some caution despite strong historical returns.
The realization of synergies and increased production scale following the Newcrest Mining acquisition, together with ongoing asset optimization and the ramp-up of expansion projects (such as Ahafo North and Tanami), should support long-term revenue growth and cash flow stability.
See why 165 investors see Newmont as 16% undervalued.
Result: Fair Value of $137.07 (UNDERVALUED)
Still, Newmont's story can change quickly if lower grade ore at key sites or higher sustaining and development capex weaken the thesis on margins and free cash flow.
Find out about the key risks to this Newmont narrative.
Another View: Newmont Through A Cash Flow Lens
The narrative crowd leans on a fair value of $137.07, yet the SWS DCF model paints a cooler picture. On that framework, Newmont at $115.79 trades above an estimated future cash flow value of $98.28, which points to an overvalued verdict instead of a clear bargain. For investors, the question is simple: Which story matters more, earnings multiples or hard cash generation?
Look into how the SWS DCF model arrives at its fair value.
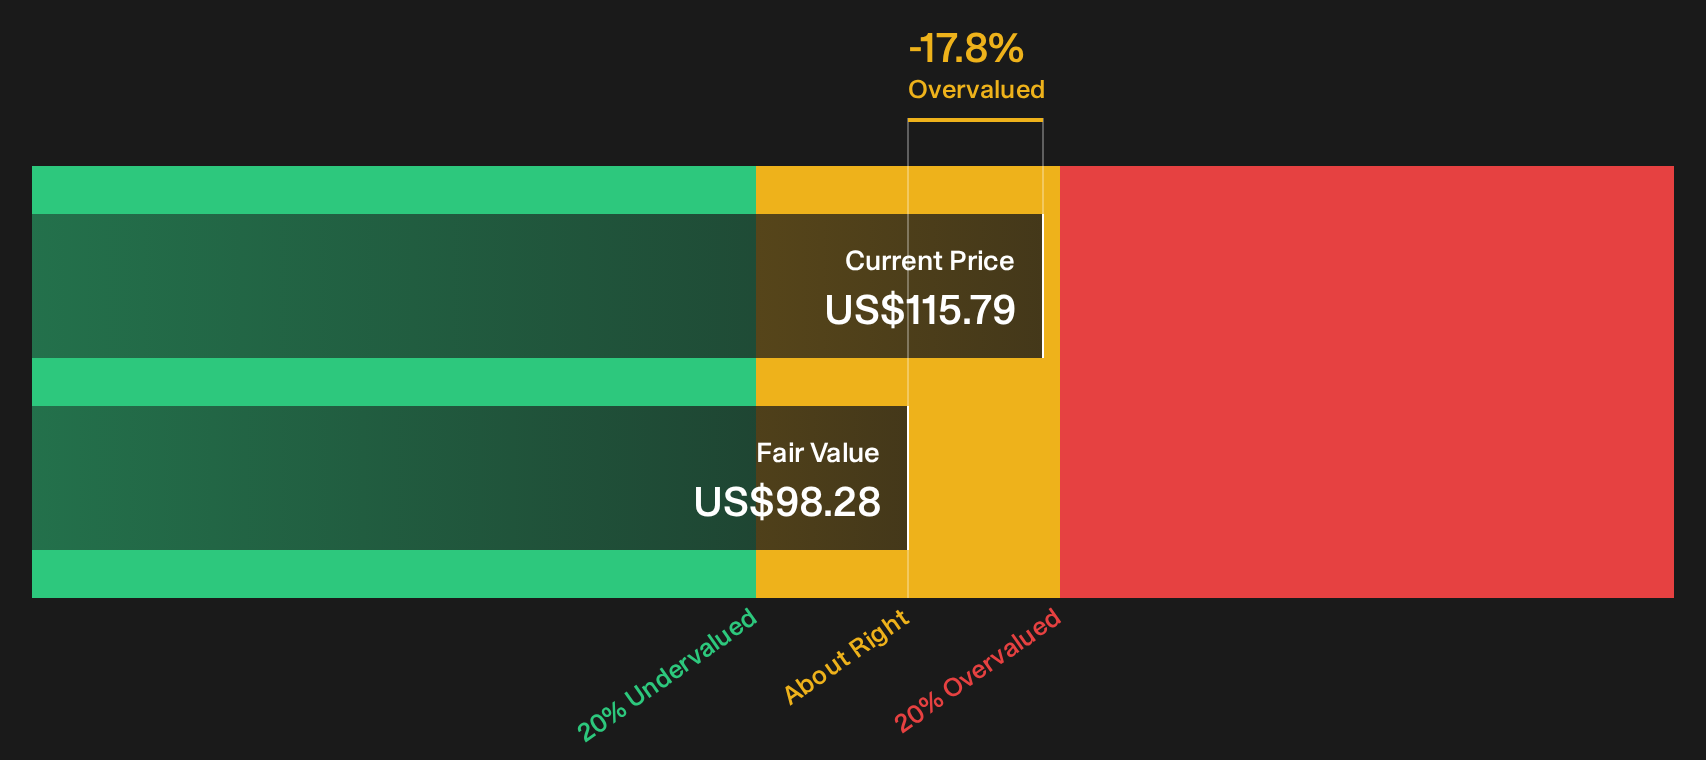
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Newmont for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Newmont so far. If you want to move fast and evaluate the balance between risk and reward for yourself, start with the 4 key rewards and 1 important warning sign.
Looking for more Newmont-adjacent investment ideas?
If Newmont has sharpened your focus on quality, do not stop here. Broader opportunity often sits just beyond the obvious ticker in front of you.
Use the Simply Wall St Screener to quickly spot other potential ideas before they are crowded trades.
- Target potential value plays that pair strong fundamentals with room for a re-rate through the 33 high quality undervalued stocks.
- Secure potential income ideas that combine higher yields with resilience in tough conditions via the 8 dividend fortresses.
- Prioritize resilience first and seek companies with sturdier finances using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com