


Asian Penny Stocks: Axelum Resources And 2 Other Notable Picks
Amid the backdrop of fluctuating oil prices and evolving geopolitical tensions, Asian markets have shown resilience, with indices reflecting a mix of cautious optimism and strategic shifts. In such a climate, discerning investors often look beyond the usual headlines to identify opportunities in lesser-known corners of the market. Penny stocks, though sometimes viewed as relics from earlier trading days, remain relevant for their potential to offer growth at accessible price points. This article explores three standout penny stocks in Asia that combine strong financials with promising prospects for those seeking hidden value.
Let's dive into some prime choices out of the screener.
Axelum Resources (PSE:AXLM)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Axelum Resources Corp. manufactures and distributes coconut products in the Philippines, the United States, and Australia, with a market cap of ₱10.64 billion.
Operations: The company generates revenue of ₱10.07 billion from the sale of coconut-based products.
Market Cap: ₱10.64B
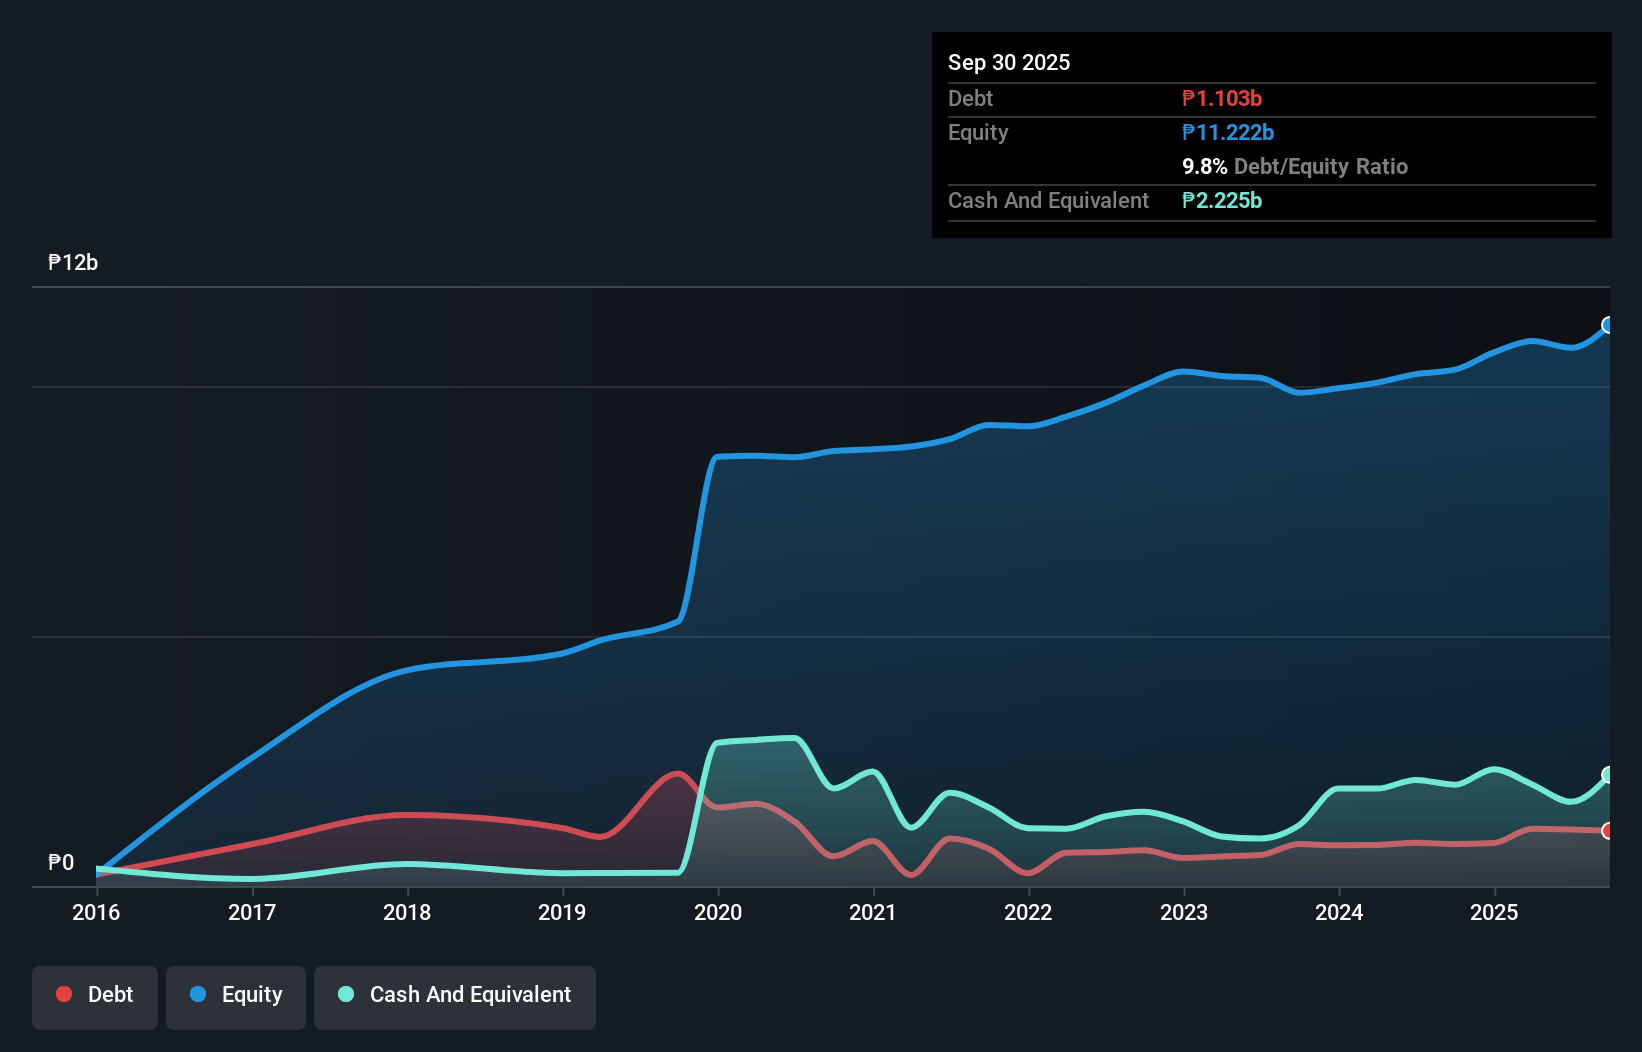
Axelum Resources demonstrates strong financial health with short-term assets exceeding both short and long-term liabilities, and cash surpassing total debt. The management team is seasoned, averaging 9.4 years in tenure, while the board averages 7.4 years. The company has achieved high-quality earnings with a notable profit margin increase from 8.1% to 10.3% over the past year, alongside a significant earnings growth of 48.6%, outperforming its industry peers' growth rate of 6.1%. Recent results showed increased net income despite a slight drop in sales, reflecting resilience amid market fluctuations.
- Jump into the full analysis health report here for a deeper understanding of Axelum Resources.
- Gain insights into Axelum Resources' historical outcomes by reviewing our past performance report.
Tian Tu Capital (SEHK:1973)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Tian Tu Capital Co., Ltd. is a private equity and venture capital firm that invests in small and medium-sized companies across various stages, with a market cap of approximately HK$2.11 billion.
Operations: The company's revenue is primarily derived from its Private Equity Investment segment, totaling CN¥350.18 million.
Market Cap: HK$2.11B
Tian Tu Capital has recently become profitable, with its price-to-earnings ratio of 9.4x indicating a valuation below the Hong Kong market average. The company announced an interim dividend of RMB 1.50 per 10 shares, reflecting shareholder returns despite earnings declining by an average of 36.2% annually over five years. Tian Tu's short-term assets (CN¥2 billion) surpass its short-term liabilities (CN¥679.5 million), but long-term liabilities remain uncovered by these assets. Cash reserves exceed total debt, and interest payments are well covered by EBIT at a multiple of 7.3x, highlighting financial stability amidst high share price volatility.
- Click to explore a detailed breakdown of our findings in Tian Tu Capital's financial health report.
- Gain insights into Tian Tu Capital's past trends and performance with our report on the company's historical track record.

Wing Lee Development Construction Holdings (SEHK:9639)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Wing Lee Development Construction Holdings Limited is an investment holding company that operates as an infrastructure contractor in Hong Kong, with a market cap of HK$1.02 billion.
Operations: The company's revenue is primarily derived from its civil engineering segment at HK$344.41 million, followed by electrical and mechanical engineering at HK$225.51 million, and new energy projects contributing HK$42.80 million.
Market Cap: HK$1.02B
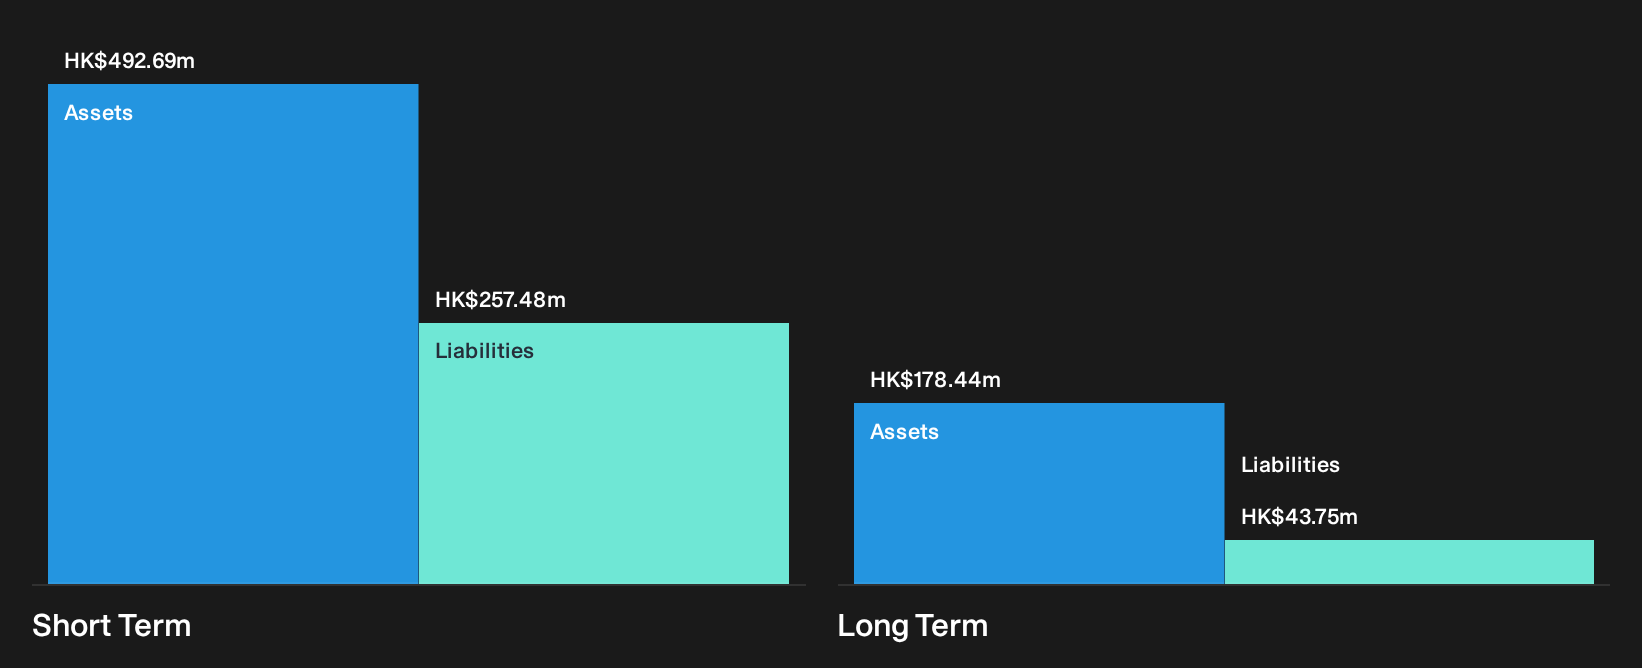
Wing Lee Development Construction Holdings faces challenges with its declining earnings, which have decreased by 14.5% annually over the past five years and 66.8% in the last year alone, highlighting a struggle to outperform industry averages. The company's net profit margin has also dropped from 7.7% to 3%, indicating profitability pressures despite satisfactory debt management with a net debt to equity ratio of 0.4%. While short-term assets of HK$492.7 million comfortably cover both short-term and long-term liabilities, negative operating cash flow raises concerns about covering debts effectively, even as interest payments remain well covered at a multiple of 6.2x EBIT.
- Navigate through the intricacies of Wing Lee Development Construction Holdings with our comprehensive balance sheet health report here.
- Review our historical performance report to gain insights into Wing Lee Development Construction Holdings' track record.
Summing It All Up
- Embark on your investment journey to our 1,061 Asian Penny Stocks selection here.
- Searching for a Fresh Perspective? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com