


Himax Technologies (HIMX) Could Be 60% Undervalued On Alibaba Smart Glasses Win
Himax Technologies (NasdaqGS:HIMX) drew fresh attention after Alibaba integrated its WiseEye HX6538 ultralow power AI processor into the new Qwen Glasses N1, enabling an always-on visual sensing system with tightly controlled energy use.
In the short term, Himax Technologies has given back some ground, with the 7-day share price return down 8.7% and the 30-day share price return down 8.4%. However, the year-to-date share price return of 42.0% and 3-year total shareholder return of 132.0% indicate momentum that has been building over a longer period as investors reassess the risk and opportunity around partnerships such as the Alibaba smart glasses launch.
Scan beyond Himax Technologies and Alibaba’s smart glasses partnership by lining up other AI-focused hardware plays in our curated list of 94 AI infrastructure stocks.
After a sharp year-to-date climb and a recent pullback, Himax Technologies now poses a simple question for anyone on the sidelines: Does the current valuation still leave the risk reward tilted toward buyers?
Most Popular Narrative: 60% Undervalued
On the most followed view, Himax Technologies screens as undervalued, with a narrative fair value of $30.20 against a last close of $12.11. This puts the Alibaba smart glasses news into a much bigger earnings and product mix story.
Rising contribution from non driver, AI and optical products, which reached 20.2% of Q2 2026 revenue and are targeted to approach 30% of sales in 2027, gives Himax Technologies more exposure to higher margin categories and can gradually shift the earnings mix away from traditional driver ICs.
See why 57 investors see Himax Technologies as 60% undervalued.
Result: Fair Value of $30.20 (UNDERVALUED)
Still, the bullish Himax Technologies story relies heavily on optimistic analyst forecasts and rich current P/E assumptions. These could unwind quickly if sentiment or earnings projections reset.
Find out about the key risks to this Himax Technologies narrative.
Another View: Himax Technologies Looks Expensive On Earnings
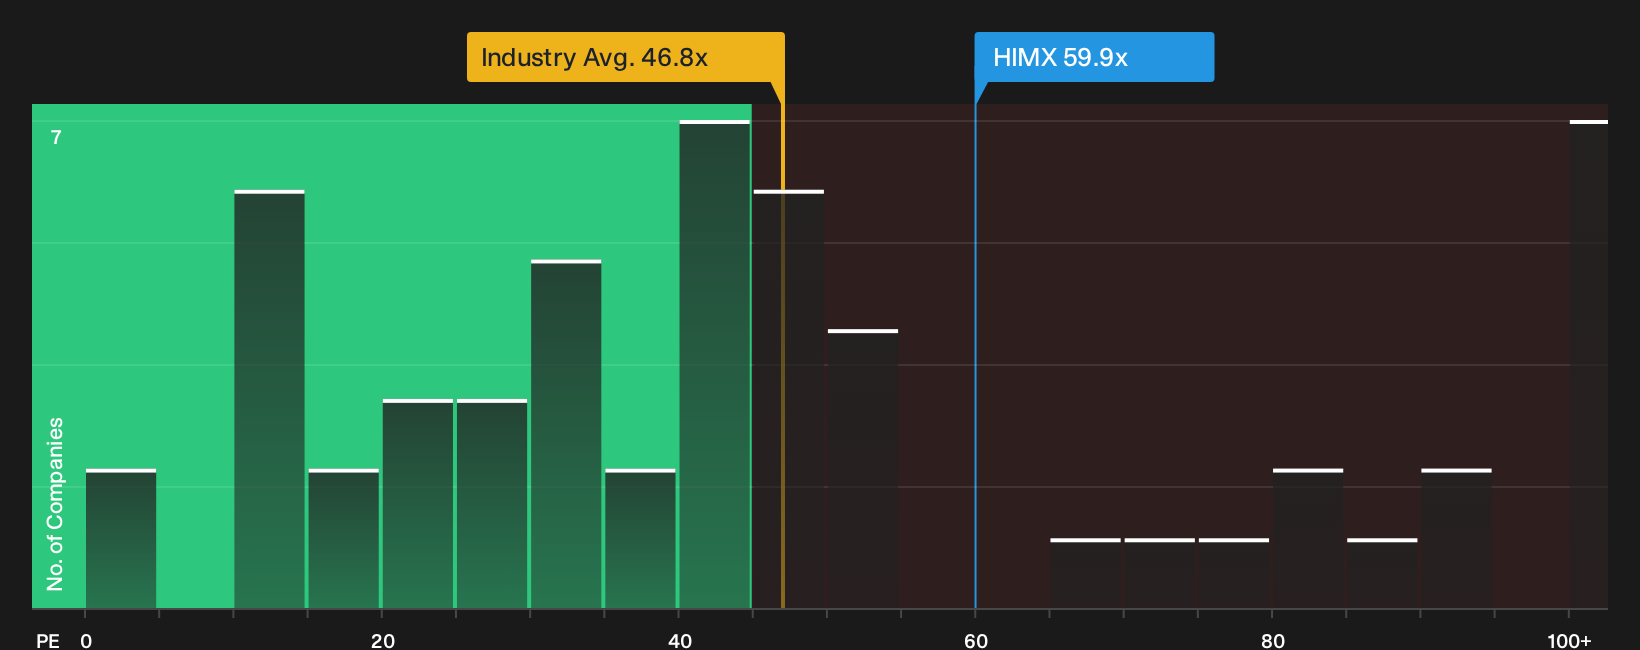
That $30.20 narrative fair value leans heavily on long range analyst forecasts. On more basic P/E maths, Himax Technologies looks stretched, trading on 59.9x earnings versus 46.8x for the wider US Semiconductor group, 46.3x for peers, and a fair ratio of 49x that the market could gravitate toward.
If the share price drifts closer to that fair ratio, the re rating risk would sit with existing holders rather than fresh buyers. Valuation tools can disagree, so which signal do you trust most for your own process: price targets based on narratives or current earnings multiples?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like this rarely stay unresolved for long, so check the numbers yourself and decide where Himax Technologies truly sits on your watchlist. To balance your own assessment, weigh the 1 key reward and 2 important warning signs
Looking for more Himax Technologies style investment ideas?
Himax Technologies highlights how quickly a fresh theme can move, so do not stop here. Use the Simply Wall Street Screener to spot the next setups before they break into the mainstream.
- Target quality at a discount by scanning a focused pool of 32 high quality undervalued stocks that combine solid fundamentals with prices that lag underlying business strength.
- Prioritise staying power and sleep better at night by concentrating on a list of solid balance sheet and fundamentals (25 results) that can better absorb shocks when conditions change.
- Hunt for tomorrow’s leaders early by filtering for 20 high quality undiscovered gems that have strong financial profiles but limited current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com