


3 Japanese Growth Stocks With At Least 23% Earnings Growth
Hotter than expected US inflation data has hit tech shares hard and pushed investors to rethink what they are willing to pay for growth. For Japanese high growth stocks, sharp selloffs can create a rare window to buy quality businesses that still have strong internal ambitions and supportive analyst views. This article highlights three high conviction names from that universe and outlines what makes each story worth watching.
The three stocks below are a small sample of the ideas that cleared the bar, with the full screen surfacing 25 more Japanese high growth companies that analysts and management teams are backing with equally strong narratives.
To identify and analyze those extra opportunities right away, head straight into the High Growth High Conviction screener
Sansan (TSE:4443)
Overview: Sansan is a Tokyo based software company that digitizes business cards, contacts, invoices and contracts to help enterprises grow sales efficiently.
Operations: Sansan generates about ¥48.9b in revenue mainly from its Sansan and Bill One segment, with all ¥56.2b of sales coming from Japan.
Market Cap: ¥238.7b
Sansan aligns closely with the High Growth High Conviction theme because its contact management SaaS and enterprise digitization tools sit directly on top of corporate sales pipelines. For investors, a key consideration is how changes in enterprise adoption could affect the business.
That adoption question is exactly what the analyst forecasts for Sansan are built around, highlighting where expectations may be accelerating ahead of the story or lagging it.

Micronics Japan (TSE:6871)
Overview: Micronics Japan develops and sells semiconductor probe cards, wafer probers, and inspection equipment that support chip manufacturing and testing growth worldwide.
Operations: Micronics Japan generates about ¥86.3b in revenue, with roughly ¥84.9b from the Probe Card Business and demand spread across Japan and Asia.
Market Cap: ¥511b
Micronics Japan sits squarely in the High Growth High Conviction theme, with its semiconductor test equipment tied directly to expanding chip manufacturing and forecast earnings growth of around 24.88% per year as capacity ramps for memory and AI related demand. The key consideration for investors is how much that guidance and high ROE can hold up if a single key assumption shifts.
That single shift can be material, so pull up the 2 key rewards and 1 important major warning sign to see where Micronics Japan’s upside story could decouple from its assumptions.

Kasumigaseki CapitalLtd (TSE:3498)
Overview: Kasumigaseki Capital develops real estate projects while running higher growth solar power, logistics, hotel, and healthcare facility operations across Japan.
Operations: Kasumigaseki Capital generates ¥163,756m in revenue from its Real Estate Consulting Business, with all sales currently coming from Japan.
Market Cap: ¥171.2b
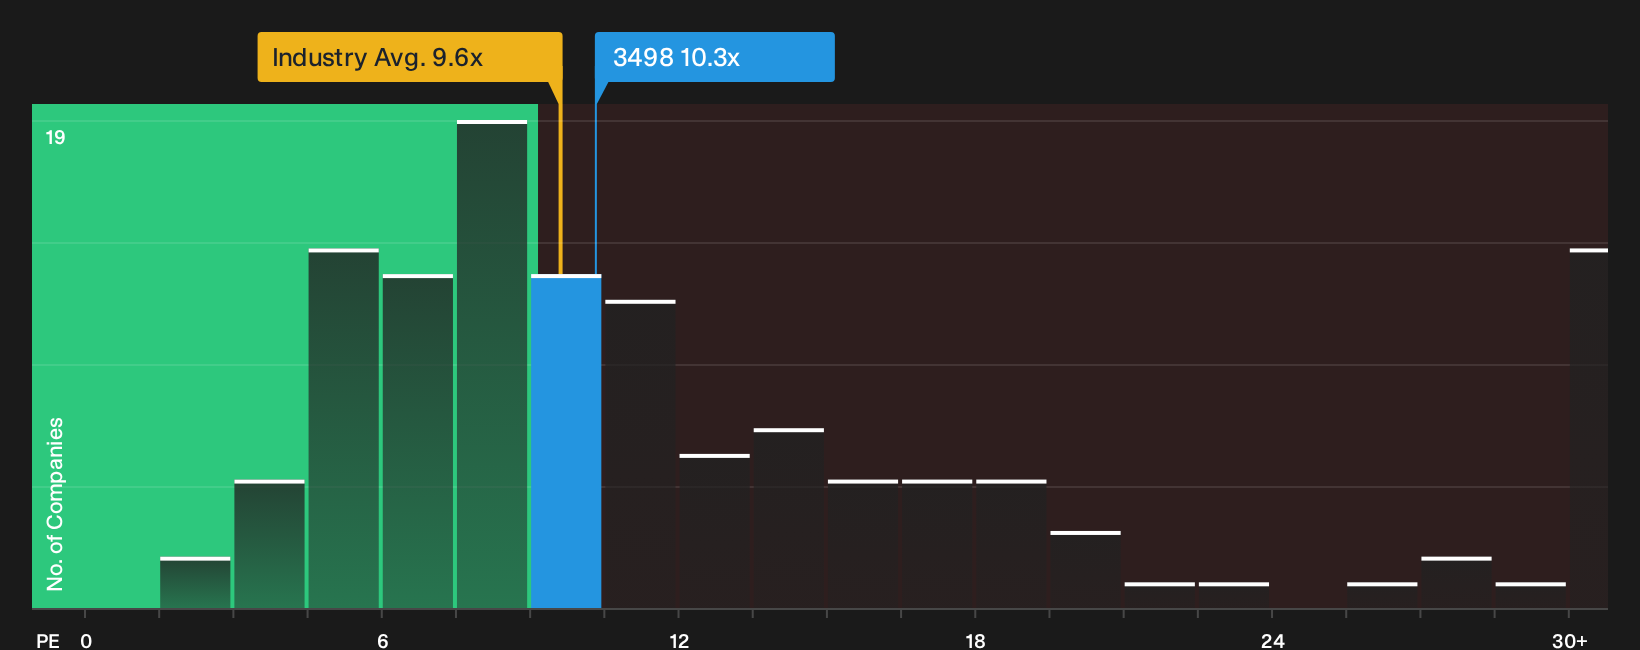
Investors watching High Growth High Conviction ideas may pay attention to Kasumigaseki Capital’s combination of earnings expansion and management backed solar development, on top of a P/E around 10.3x against sector peers near 13.5x and expectations of earnings rising above 20% a year, while also considering how conditions could change if one underlying funding pressure tightens.
If that funding lever moves, go straight to the 4 key rewards and 5 important warning signs (2 are major!) for Kasumigaseki CapitalLtd to see where optimism could collide with pressure.
Seeking Alternatives Before Momentum Flies
Fresh ideas often move first, and late money can get caught chasing someone else’s breakout. Scan new momentum while it matters and is still under the radar, and consider acting earlier in the move.
- Identify cash-rich market leaders before the broader market focus shifts to them by running the list of solid balance sheet and fundamentals (21 results) and centering your watchlist on businesses designed to handle shocks.
- Look for income opportunities that aim to do more than simply keep pace with basic benchmarks by checking the 32 dividend fortresses and narrowing in on companies targeting stronger yields with resilience.
- Monitor automation trends that some competitors may overlook by scanning the 91 robotics and automation stocks and concentrating on operators aligned with long term productivity shifts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com