


Higher Treasury Yields Raise Questions For Bandwidth Stock
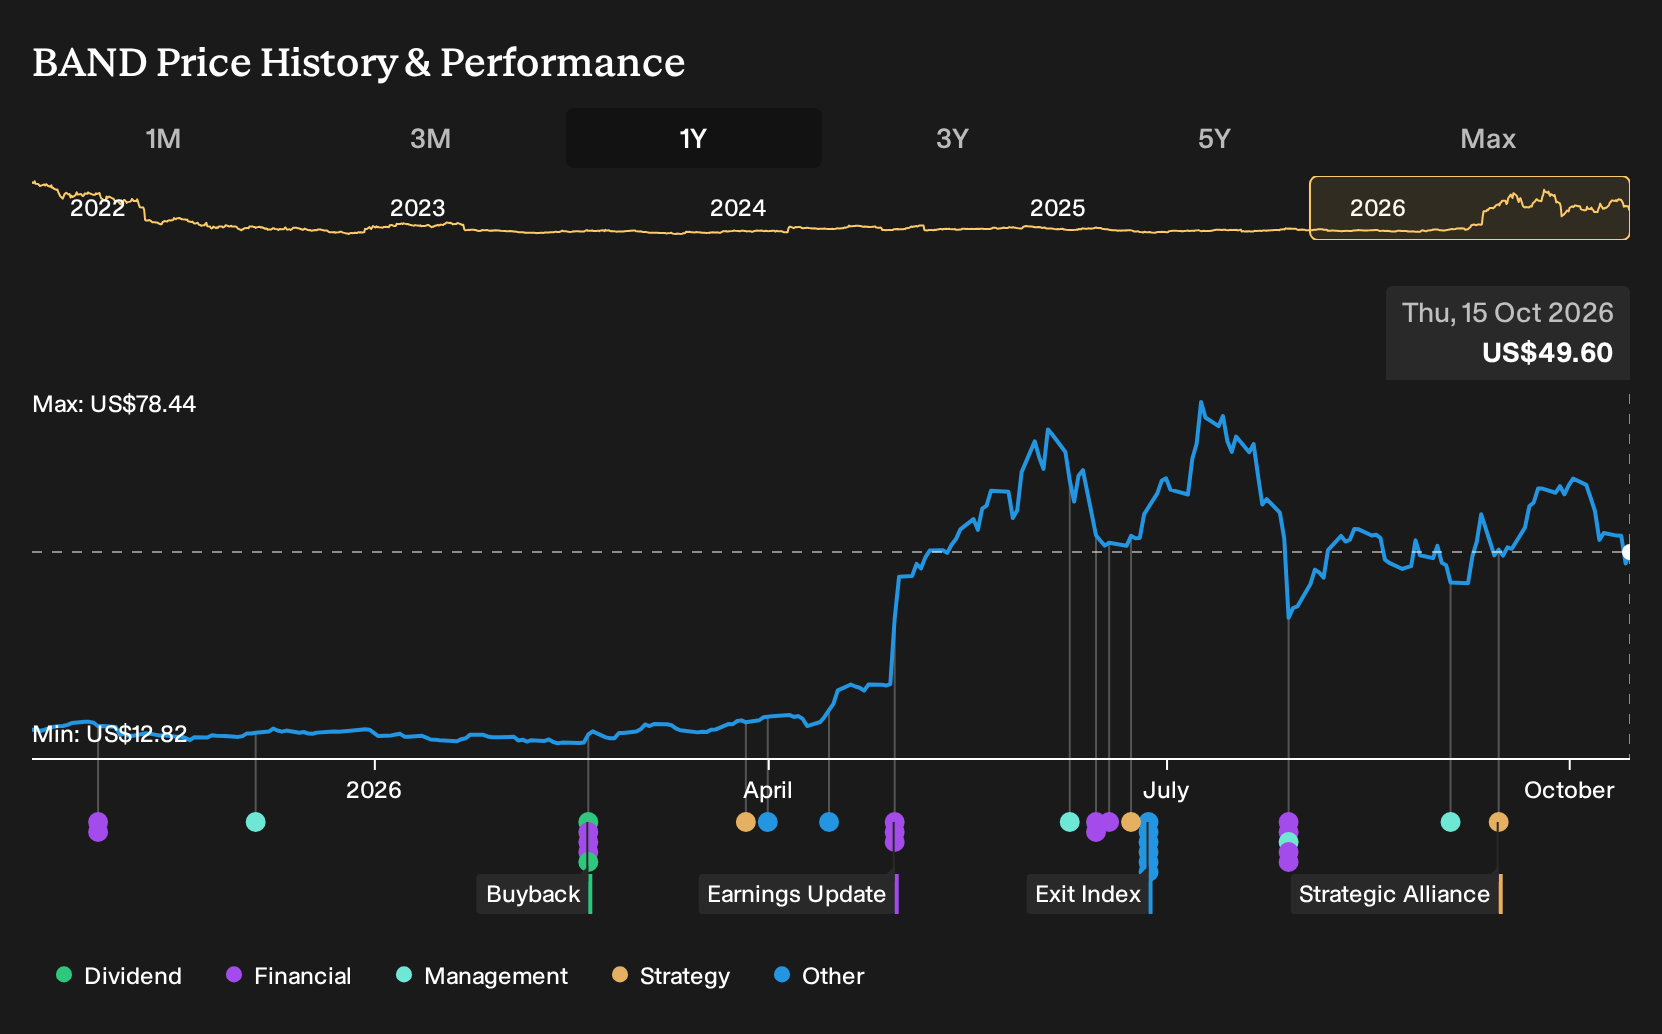
- Bandwidth shares recently declined 6.4% after a hotter September inflation reading pushed Treasury yields higher, putting pressure on richly valued technology companies along with much of the broader market.
- The move highlights how Bandwidth’s fundamentals, oriented toward AI, cloud communications, and large enterprise contracts, can still be heavily influenced by macro forces such as interest rates and inflation.
- We will now explore how Bandwidth's investment narrative could be influenced by rising Treasury yields that followed the September inflation surprise.
Scan how other interest rate sensitive tech stories compare by running the same lens over our hand picked 94 AI infrastructure stocks after this Bandwidth move.
Bandwidth Investment Narrative Recap
To own Bandwidth, you need to believe large enterprises will keep leaning into cloud communications and AI powered voice, and that Maestro can stay central to that shift. The recent inflation surprise and yield spike mainly hit the share price, not the day to day operations. Unless higher rates start to crimp customer IT budgets, the core adoption story looks largely intact.
The key near term swing factor is execution on big enterprise deals and keeping AI use cases scaling on the platform. The biggest risk is concentration in large, regulated customers combined with heavy investment needs. If adoption slows or big clients push back on pricing or contracts, revenue visibility and margin improvement could come under pressure.
Recent commentary that earnings are forecast to grow 87.49% per year has become more relevant as the stock reacts to macro data. A hotter inflation print and higher Treasury yields put extra scrutiny on whether Bandwidth can move from modest profitability and a 0.6% return on equity toward cleaner, less one off driven earnings.
With Bandwidth now profitable and revenue at about US$828.2m, the task is turning that scale into more durable cash generation while carrying a high level of debt. For readers, the link between macro driven multiple pressure and this earnings ramp is simple: execution on Maestro, enterprise migrations, and cost discipline will likely matter more than day to day moves in yields.
Bandwidth's current earnings of US$2.3 million are projected by analysts to reach US$72.9 million by 2029. This implies earnings would rise by about 31x. The same forecasts point to revenue of US$1.1b by that year, supported by an assumed 11.2% yearly revenue growth rate over the next few years.
Uncover why Bandwidth's fair value indicates a 36% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Higher rate sensitivity is the big swing factor in the alternate, more optimistic view. The most bullish analysts were penciling in revenue of about US$1.2b and earnings of US$91.2 million by 2029, compared with US$1.1b and US$72.9 million in the baseline. After this inflation surprise, those bolder assumptions may face a rethink.
Explore 3 other Bandwidth fair value estimates, including one that suggests as much as 278% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A useful starting point for your Bandwidth research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bandwidth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which allows you to evaluate Bandwidth's overall financial health at a glance.
Looking for more investment ideas beyond Bandwidth?
Once you have a view on Bandwidth, it often helps to compare it with other companies that share some of the same themes, whether that is quality fundamentals, balance sheet strength, or income potential.
The Simply Wall St Screener can surface different types of opportunities quickly, so you can pressure test your Bandwidth thesis against a wider watchlist.
- If you care most about resilient balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without relying heavily on new funding.
- For readers hunting for mispriced quality, filter for potential value ideas using a 32 high quality undervalued stocks that combine stronger financials with more modest expectations.
- Income focused investors who want cash returns from day one can search for companies offering reliable payouts through a 8 dividend fortresses that may suit a yield oriented portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com