


Rubicon Research And 2 Other Indian Growth Stocks With Insider Backing
Hotter than expected US inflation has hit rate sensitive sectors and knocked confidence in many growth stories, yet Indian companies that already show strong expansion with meaningful insider ownership look different. Management teams with significant skin in the game can be less tempted to chase short term hype. This article highlights three fast growing Indian stocks where insiders hold sizeable stakes and explains why that mix may appeal to some investors in the current environment.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily invested alongside you. However, if you want the names that matter most, these 40 high growth high conviction stocks are the strongest companies we've found.
Rubicon Research (NSEI:RUBICON)
Overview: Rubicon Research is a Mumbai based specialty pharmaceutical group that develops proprietary drug delivery formulations using its RubiReten and RubiSRL platforms across several therapy areas.
Operations: Rubicon Research generates ₹19,358 million in revenue from pharmaceutical products and related services, primarily through generics and specialty formulations.
Market Cap: ₹244.5 billion
Rubicon Research fits this fast growing, high insider alignment theme through its focus on proprietary drug delivery platforms that aim for higher value formulations in complex therapies, all supported by management backing ongoing expansion.
"Expansion of US manufacturing capacity through the New Jersey facility and preparation of the Pithampur site in India is expected to support a higher own manufacturing share and can support gross margin resilience and operating EBITDA over time."
What really matters now is how one quiet shift in product mix ultimately filters through to pricing power and long term margin strength.
That margin question is exactly what the full narrative for Rubicon Research tackles, mapping how capacity shifts, pricing power and insider alignment could interact if expansion really starts to accelerate.

Atlanta Electricals (NSEI:ATLANTAELE)
Overview: Atlanta Electricals manufactures and sells power, solar and industrial transformers across India, supplying equipment for transmission, infrastructure and renewable projects.
Operations: The business generates about ₹20,027 million in revenue from manufacturing power and special duty transformers, with all reported sales coming from India.
Market Cap: ₹131.6 billion
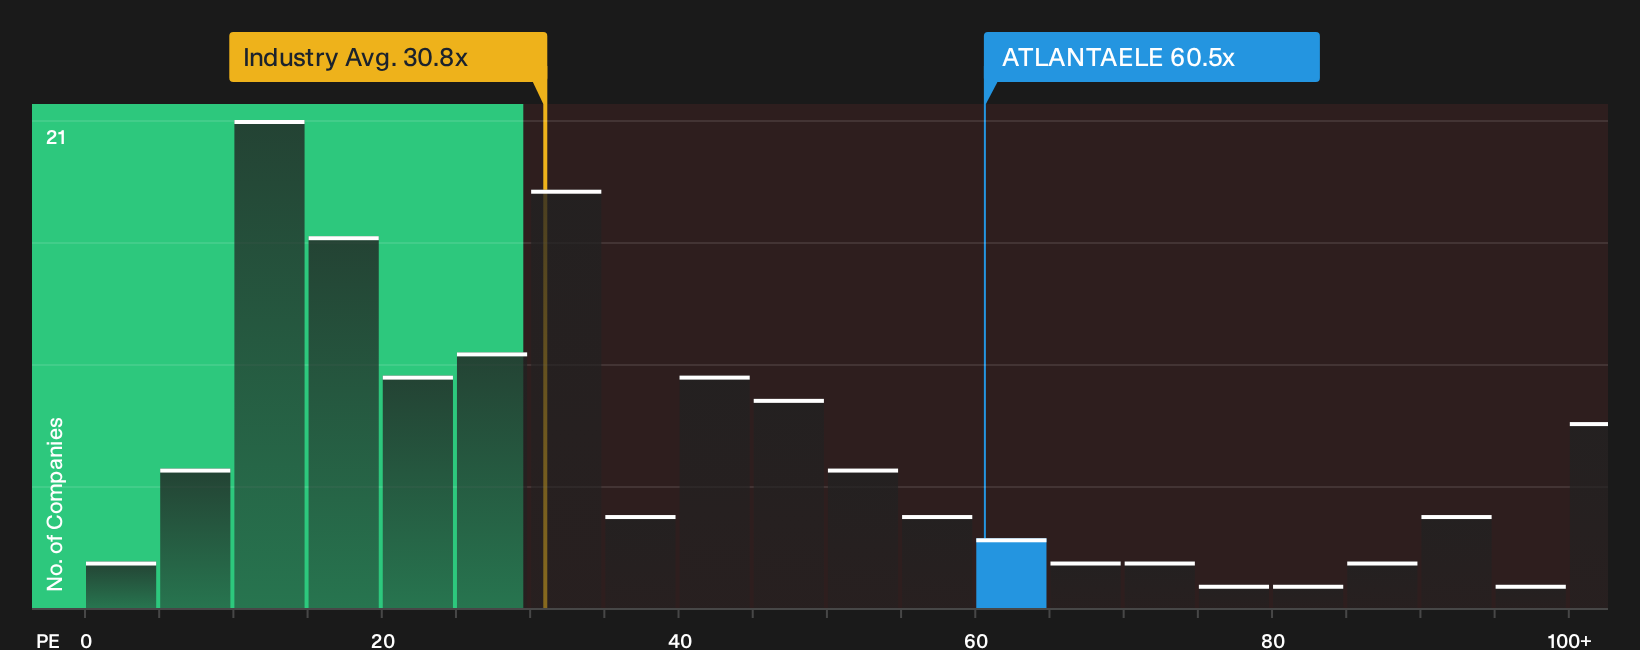
Atlanta Electricals plugs directly into the screener theme because its transformer manufacturing ties into power grid upgrades, solar rollout and infrastructure build. Earnings growth of 74.1% and a 23.2% revenue growth forecast support a high growth label, while a premium 60.5x P/E leaves a lot riding on what happens if a single key assumption breaks.
If that premium 60.5x P/E has your attention, use the analysis report for Atlanta Electricals to see what could keep Atlanta Electricals’ growth story on track or cause it to stall.
Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects delivers turnkey EPC solutions for high voltage power transmission and distribution infrastructure, including lines, substations and underground cabling.
Operations: The business generates about ₹27,508 million in revenue from power transmission and power distribution EPC work.
Market Cap: ₹18.2 billion
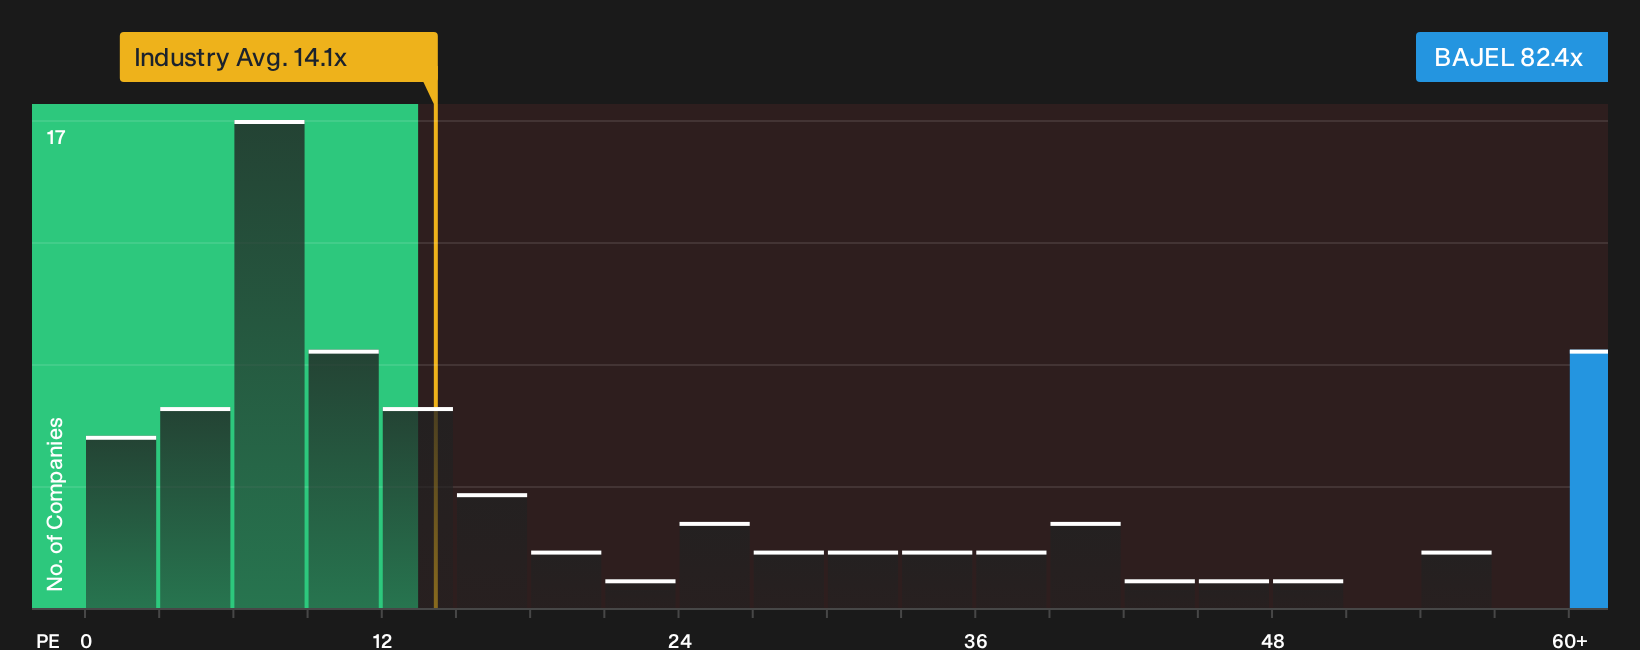
Bajel Projects combines high voltage transmission EPC work with earnings growth forecast at 57.67% and revenue forecast to increase 27% a year, backed by sizeable domestic and overseas orders. Investors who focus on higher forecast growth and management optimism may view the rich 82.4x P/E as either acceptable or concerning, depending on how a currently uncertain funding pressure develops.
If that funding squeeze is what you are watching, go straight to the analysis report for Bajel Projects where Bajel Projects’ high multiple meets its order book reality
Seeking Fresh Alternatives Before Others
Markets move fast and the freshest ideas do not stay under the radar for long. Spot potential breakouts, shifting momentum and still grounded valuations before the crowd, then act now.
- Consider resilient potential compounders by scanning the 225 resilient stocks with low risk scores and see which businesses are still quietly building strength while headlines chase louder stories.
- Look for cash generative AI opportunities through the 38 profitable AI stocks that aren't just burning cash and focus on companies already funding their own progress instead of relying on constant new capital.
- Explore developing power infrastructure themes using the 41 power grid technology and infrastructure stocks and find builders of the backbone tech that helps keep electrification rollouts from getting caught short.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com