


Clarivate Stock And Its AI Patent Workflow Partnership】【。
- In October 2026, Sterne, Kessler, Goldstein & Fox announced a co-development partnership with Clarivate to build AI-driven patent workflow tools, with the first release for Rowan Patents targeted for the first half of 2027.
- The focus on embedding AI into patent drafting workflows points to Clarivate prioritising deeper workflow integration and data-driven productivity gains for IP clients over stand-alone analytics tools.
- This article examines how Clarivate's investment narrative is shaped by this AI patent workflow partnership and its push into embedded workflows.
Scan how Clarivate's AI patent push compares with other potential breakouts in IP rich and data heavy businesses by reviewing the hand picked 38 profitable AI stocks that aren't just burning cash list.
Clarivate Investment Narrative Recap
To stay invested in Clarivate, you need to believe the company can turn its data assets and AI products into steadier, higher quality recurring revenue while managing a heavy balance sheet and restructuring costs. The AI patent partnership fits that belief because it leans into workflow tools where Clarivate already has strong content and customer relationships.
The key near term swing factor remains execution on portfolio simplification and cost discipline after multiple divestitures, with the Life Sciences and Healthcare sale cutting reported revenue and testing customer retention. The biggest risk is that shrinking top line and high funding costs restrict investment in AI products just as competition in research and IP data intensifies.
The partnership with Sterne, Kessler, Goldstein & Fox around AI patent workflows looks most relevant because it directly touches Clarivate's IP segment, which some analysts associate with global patent filing trends. By bringing AI into Rowan Patents drafting flows, Clarivate is trying to make its tools feel less like databases and more like everyday infrastructure for IP professionals.
That matters for catalysts because better workflow integration can support subscription stickiness and potential pricing power if customers see time savings and better decision support. It also speaks to execution risk. Clarivate is unprofitable today and facing forecast revenue declines, so delivering useful, trusted AI tools on time and at controlled cost is central to whether this shift improves earnings quality.
Clarivate AI Thesis Versus The Numbers
Clarivate's AI patent push only really matters for investors if the financial trajectory lines up with the story. Analysts are currently baking in a revenue decline of 6.9% a year over the next three years, which is a tough backdrop for any turnaround narrative. At the same time, the firm is loss making today, with earnings of a loss of $334.0 million, so the AI workflow strategy is running alongside a broader repair job on margins and cash generation.
Consensus estimates effectively treat the next few years as a bridge to 2029. Forecasts assume profit margins could eventually match the wider US Professional Services group at 6.9%, which would lift earnings to $133.8 million by that year. For someone looking at Clarivate as an AI workflow and data platform, the key question is whether these margin shifts come from deeper integration into customer processes, like the Rowan Patents partnership, or mostly from cost cutting and portfolio trimming.
On the top line, the valuation work implies around $2.0b of revenue by 2029 paired with that $133.8 million of earnings. The implied future P/E of 18.8x on those projected earnings is below the current sector multiple of 22.0x, which suggests analysts are not treating Clarivate as a premium AI play despite the patent tooling focus. That gap matters for anyone asking whether embedded AI workflows in IP and research can eventually justify a higher quality, more predictable earnings profile.
Clarivate's narrative projects $2.0b revenue and $133.8 million earnings by 2029. This sits against a forecast yearly revenue decline of 6.9% and would require an earnings improvement of about $467.8 million from a loss of $334.0 million today.
Uncover how Clarivate's fair value indicates a 70% potential upside to its current price, which could narrow quickly if sentiment around Clarivate's AI execution improves.
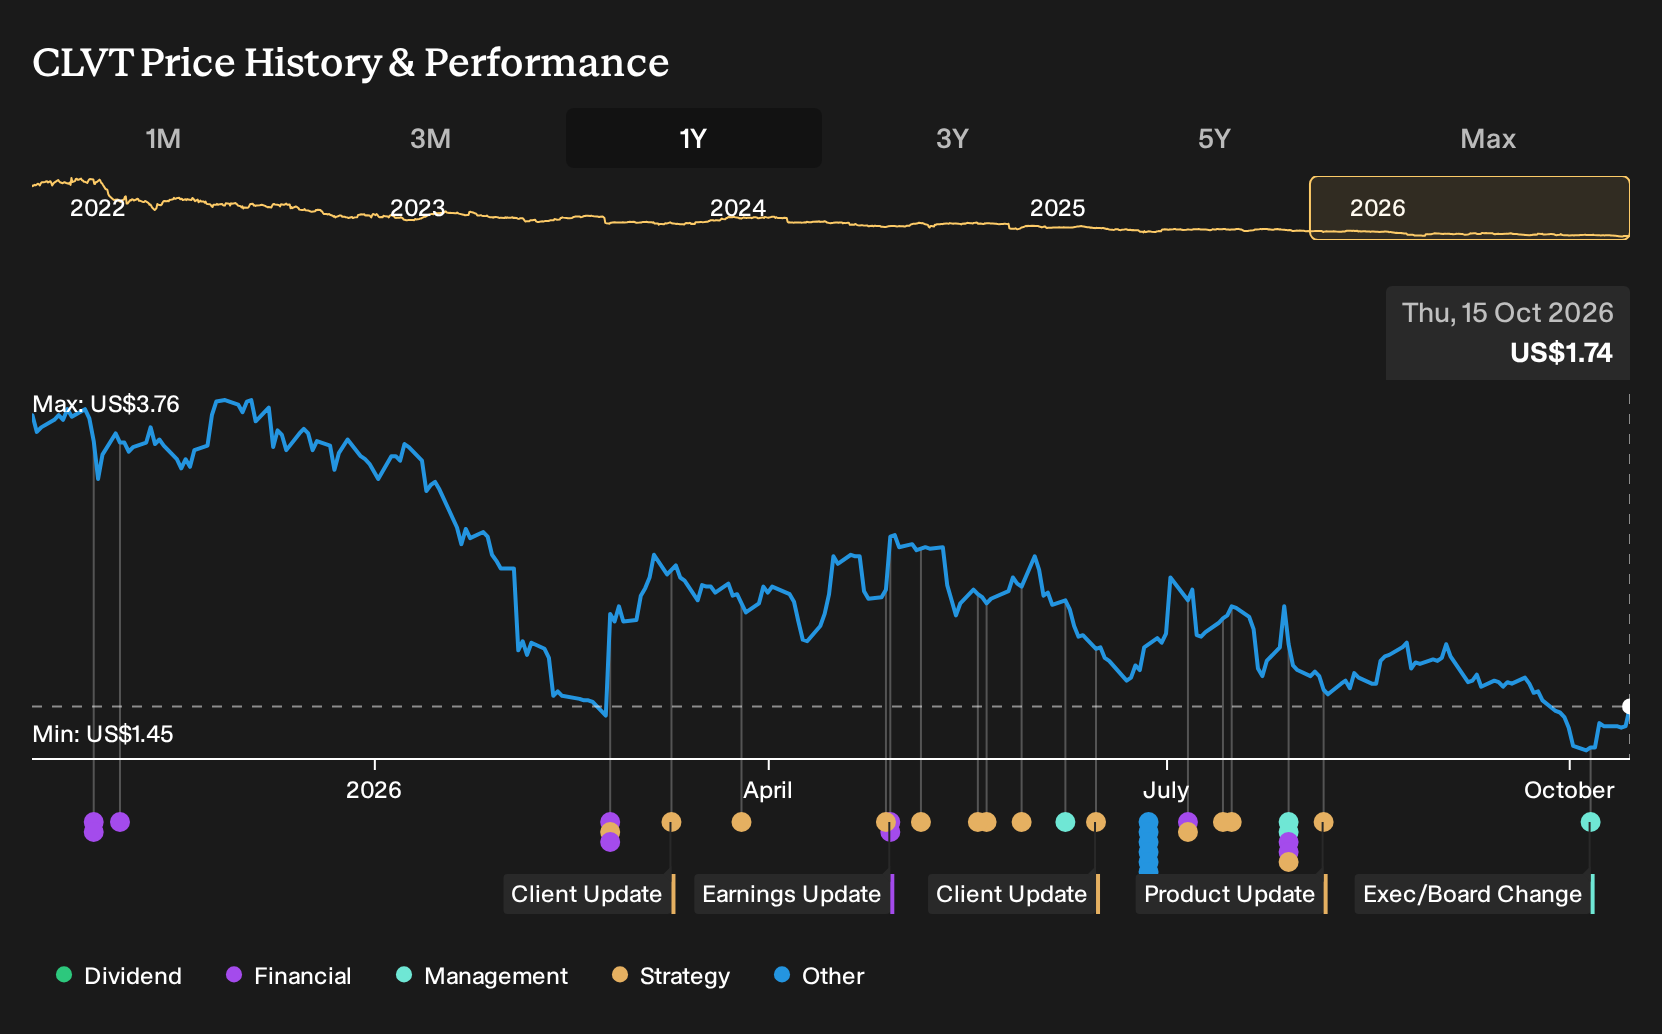
Exploring Other Perspectives
Some of the most optimistic analysts frame Clarivate very differently. They focus on AI as a route to organic growth, with forecasts that imagine revenue at about US$2.0b and earnings of US$19.1 million by 2029, even before this Rowan Patents news. You can compare that upbeat view with your own expectations and see how this partnership might shift them.
Explore 3 other Clarivate fair value estimates, including one that suggests potential upside of up to 142% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Clarivate research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Clarivate. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Clarivate's overall financial health at a glance.
Looking For More Ideas Beyond Clarivate?
If Clarivate's AI patent story has your attention but you want a broader watchlist, it can help to scan other businesses with very different balance sheets, income profiles, and risk levels. The Simply Wall St Screener gives you a way to filter for those traits quickly instead of relying on headlines.
- If capital preservation sits near the top of your priorities, focus on resilience by reviewing a set of 32 resilient stocks with low risk scores that tend to show steadier risk scores.
- For investors who care about financial strength first, build a watchlist around companies with stronger funding positions and fundamentals using the list of solid balance sheet and fundamentals (25 results).
- If you want potential upside but do not want to ignore quality, look through the 20 high quality undiscovered gems to see businesses with solid foundations that the market may not be fully pricing in yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com