


CBIZ (CBZ) Tests Fair Value After Marcum Integration Costs Cloud The Bigger Growth Story
CBIZ (CBZ) drew attention after its recent trading session, with the stock closing at US$54.73. Investors are weighing that price against the firm’s mix of advisory, insurance, and financial services.
Recent trading tells a mixed story for CBIZ. Short term share price returns over the past week were slightly negative. However, the 90 day share price return of 29.02% and 5 year total shareholder return of 54.13% point to stronger momentum building over longer periods.
Compare CBIZ's recent momentum with a handpicked set of resilient companies using the 32 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier fundamentals.
After a 90 day climb of 29.02% and a share price now close to the latest analyst target, CBIZ looks less obviously cheap. Does the current balance of risk and reward still tilt toward buyers?
Most Popular Narrative: Fairly Valued
With CBIZ last closing at $54.73 against a widely followed fair value of $55, the pricing sits almost exactly on the narrative line and puts the focus on what could shift the story rather than on any obvious discount or premium.
Although the Marcum acquisition has created a much larger platform with year to date revenue of US$2.2b and a broader mid market client base, the integration plan still carries US$89 million of 2025 integration costs and additional 2026 costs that could limit the flow through of revenue into earnings if execution slips.
See why 0 investors see CBIZ as 0% undervalued.
Result: Fair Value of $55 (ABOUT RIGHT)
Still, the CBIZ story could shift quickly if Marcum integration costs overrun or if higher talent expenses compress margins more than analysts currently factor in.
Find out about the key risks to this CBIZ narrative.
Another View: CBIZ Through The P/E Lens
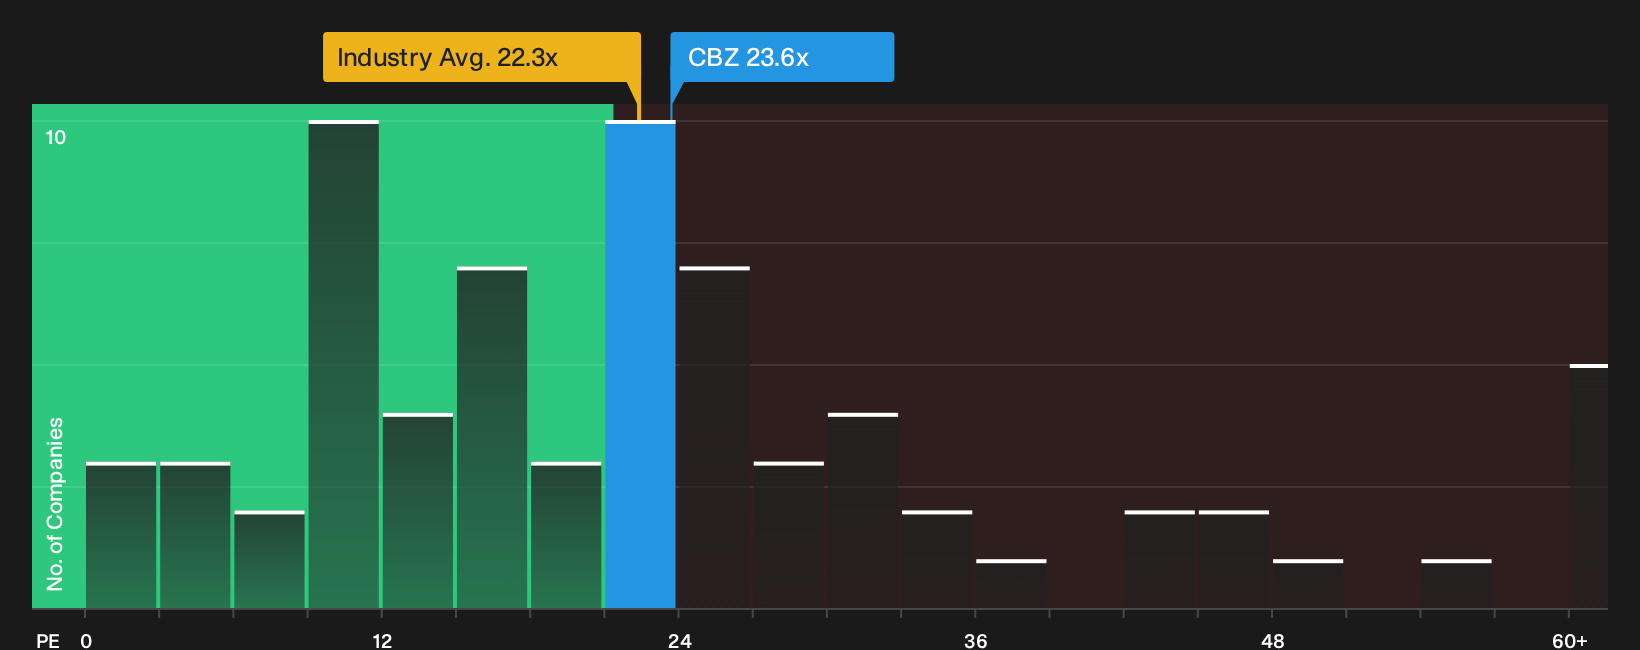
The earlier fair value story leans on analyst targets and cash flow expectations. A simple P/E check tells a different story. CBIZ trades on 23.6x earnings versus 23x for peers and 22.3x for the wider US Professional Services group, yet the fair ratio points to 24x.
That leaves CBIZ priced slightly richer than the sector today but close to where the market could move if it leans toward the fair ratio. For an investor, that raises a practical question: is this a small valuation cushion or a thin margin for error if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on CBIZ so far. If you want to move quickly and base your stance on the full picture of both concerns and bright spots, review the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CBIZ?
CBIZ gives useful context, but you do not want your next move resting on a single stock when smarter options might be sitting in plain sight.
- Target stronger value by scanning companies that pair resilient balance sheets with pricing that still looks undemanding using the 32 high quality undervalued stocks.
- Build a sturdier core by focusing on businesses with cleaner finances and fewer weak spots through the list of solid balance sheet and fundamentals (25 results).
- Hunt for off-the-radar potential where quality metrics already line up by running the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com