


3 Memory Stocks Riding The NAND Price Cycle Investors Should Watch
Memory chips rarely sit still in the headlines, yet this latest mix of U.S. export rules, AI data center demand and Solidigm’s potential New York fab plus a possible 2027 IPO suddenly puts NAND at the center of the conversation. That mix can shift pricing power and risk in ways investors might not expect. This article walks through 3 stocks exposed to this news and how each could be positioned.
The three stocks covered next are only a starter pack, and the full screen surfaced 19 more listed memory chipmakers with equally compelling stories that do not fit into a short article. If you want to identify patterns across peers and analyze which ones best fit your thesis, head straight into the NAND-Focused Memory Chipmakers screener
Winbond Electronics (TWSE:2344)
Overview: Winbond Electronics is a Taiwan based specialist in DRAM, NOR flash, and NAND related memory chips used across consumer, automotive, and industrial devices.
Operations: Winbond generates about NT$65.4b from customized memory solutions, NT$49.5b from flash memory products, and NT$29.8b from logic products, with smaller unallocated income.
Market Cap: NT$697.5b
Winbond Electronics ties directly into the NAND focused theme through its flash and NAND related memory lines, which sit alongside its DRAM and specialty memory business. The company operates within the same pricing cycle that TrendForce expects to support margins, especially where embedded and consumer storage use NAND. What happens when that pricing cycle moves even a little faster or slower than current expectations is an important consideration.
That pricing curve is already shaping today’s set up for Winbond Electronics, so it is worth scanning the 4 key rewards and 1 important major warning sign before pricing surprises show up in earnings.
GigaDevice Semiconductor (SHSE:603986)
Overview: GigaDevice Semiconductor designs and sells flash memory, including SPI NOR and SPI NAND, alongside microcontrollers, sensors, and analog chips for global electronics.
Operations: GigaDevice Semiconductor currently generates about CN¥16.6b from integrated circuit products, tying its flash memory and controller portfolio directly into end markets.
Market Cap: CN¥195.5b
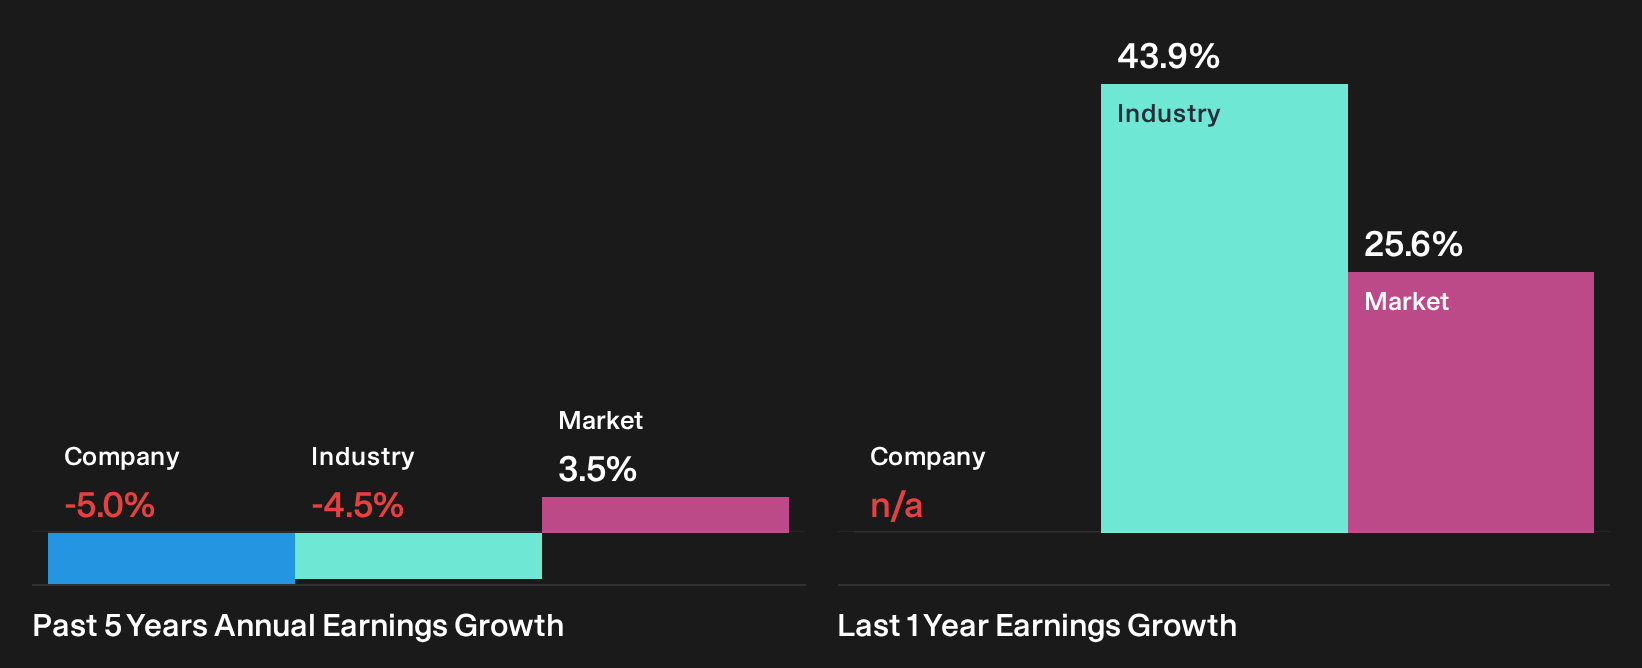
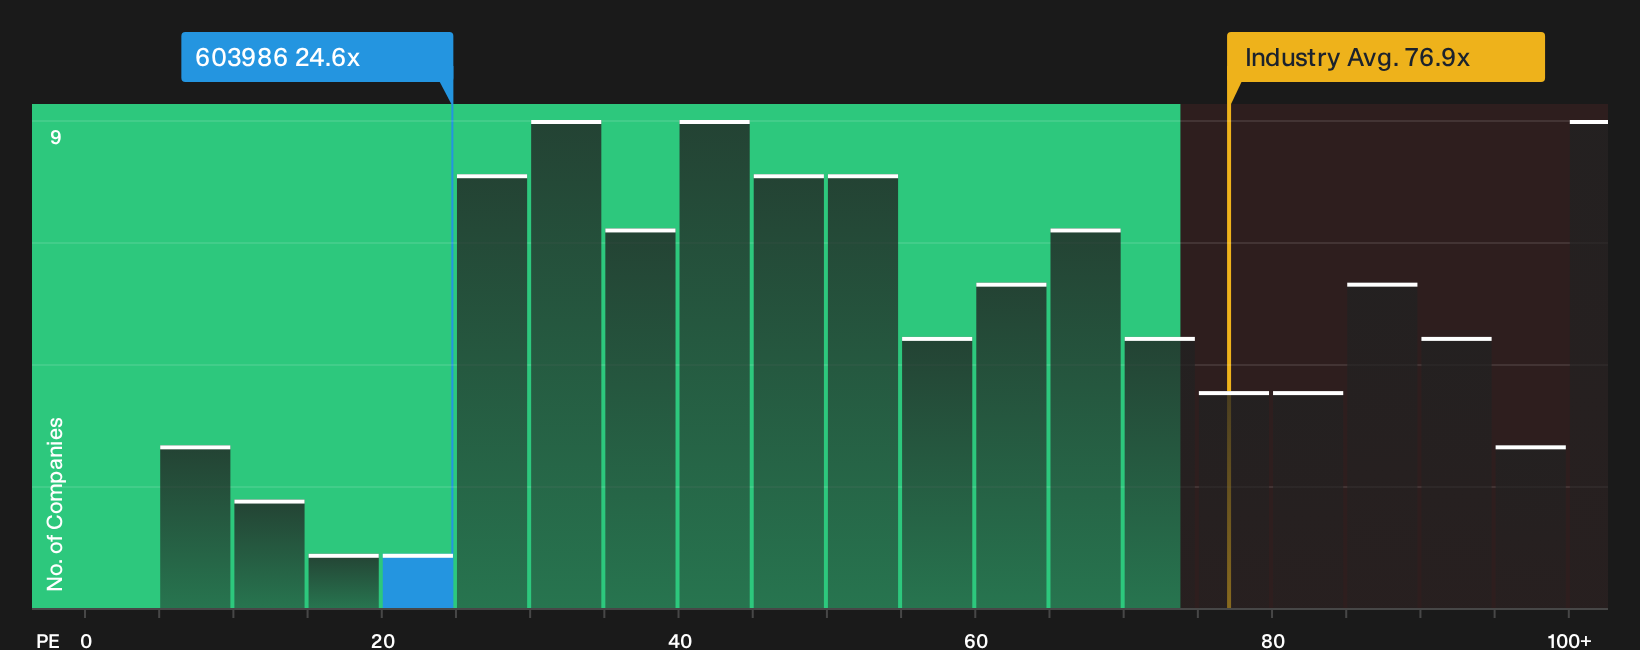
GigaDevice Semiconductor provides focused exposure to flash memory and NAND-adjacent storage while also spreading risk across MCUs and analog chips. The P/E of 24.6x sits below the wider China market multiple, and profitability is currently strong. The key consideration for investors is how sensitive that margin profile may be if a single key assumption changes.
That margin question makes the next step clear. Go straight to the 4 key rewards and 2 important warning signs to see what could accelerate or pressure GigaDevice Semiconductor next.
eMemory Technology (TPEX:3529)
Overview: eMemory Technology develops embedded flash memory and hardware security IP that underpins chips linking directly into NAND based storage growth.
Operations: eMemory Technology records NT$4.2b from memory chips, with revenue concentrated in Taiwan, Asia, and other international markets.
Market Cap: NT$198.3b
eMemory Technology matters for this NAND focused screen because it sells the embedded flash and security blueprints that other chipmakers rely on. This means its royalty stream can move differently from volume based memory manufacturers when demand shifts.
"Progress on 1T NeoFlash with several foundries and fabless customers, where the technology can support embedded and stand alone NOR and 2D NAND architectures on standard logic processes without extra masks, opens up a path for eMemory Technology to participate in portions of the standalone flash market and potentially extend royalty revenue beyond traditional embedded use cases."
What happens if a single assumption about how quickly those higher value royalties scale ends up even slightly off either way?
If that timing risk matters to you, read the full narrative for eMemory Technology to see how eMemory Technology’s royalty engine could accelerate or stall relative to broader NAND demand shifts.

Seeking Alternatives Before The Crowd?
Fresh opportunities do not wait around. New themes gather momentum, laggards get caught, and quiet winners can start flying while it still matters. Scan these ideas and get in early.
- Spot potential breakout miners before gold fever goes mainstream by reviewing the curated 35 elite gold producer stocks that investors are only starting to talk about.
- Ride structural demand for electricity and grid upgrades by checking the focused 41 power grid technology and infrastructure stocks that filters for companies aligned with long term infrastructure spending.
- Target real businesses behind the crypto headlines by studying the hand-picked 19 cryptocurrency and blockchain stocks that link directly to blockchain adoption instead of short lived hype.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com