


SharkNinja (SN) Could Be 20% Undervalued As Earnings And Product Launches Draw Focus
SharkNinja (SN) heads into its next earnings release with investors focused on two things: expected year-over-year growth in earnings and revenue, and a recent burst of product launches across floorcare and kitchen appliances.
Recent product launches like the new corded stick vacuums and Ninja PREPi system have arrived alongside strong momentum in SharkNinja’s stock, with a 30-day share price return of 15.9%, a 70.1% year-to-date share price gain, and a 1-year total shareholder return of 106.2%. These figures point to investors reassessing both growth potential and risk around the US$193.68 share price.
Capitalize on SharkNinja’s momentum by scanning a curated set of consumer-focused compounders in the 20 high quality undiscovered gems that pair rising earnings with strong product traction.The recent jump in SharkNinja’s share price can be read two ways. Is this rally tracking the underlying appliance business, or is it mostly a reset in sentiment around US$193.68 a share as earnings approach?
Most Popular Narrative: 75% Overvalued
SharkNinja’s most followed narrative pegs fair value at $110.73, well below the recent $193.68 close. This frames today’s rally as pricing in a richer future than that view supports.
My view assumes revenue growth moderating gradually from 12% today toward 6% by 2030, net margins improving modestly to 11% as direct to consumer scale offsets tariff pressure, and a 21x future earnings multiple which is above the appliance industry average, but below what pure-growth investors are currently paying. At a 9% discount rate, that gives a fair value of US$110.73, below today's price of around $123.
See why 8 investors see SharkNinja as 75% overvalued.
Result: Fair Value of $110.73 (OVERVALUED)
Still, SharkNinja’s story could shift quickly if consumer spending weakens further or if tariffs and input costs compress the current US$695.2m profit base.
Find out about the key risks to this SharkNinja narrative.
Another View On SharkNinja’s Value
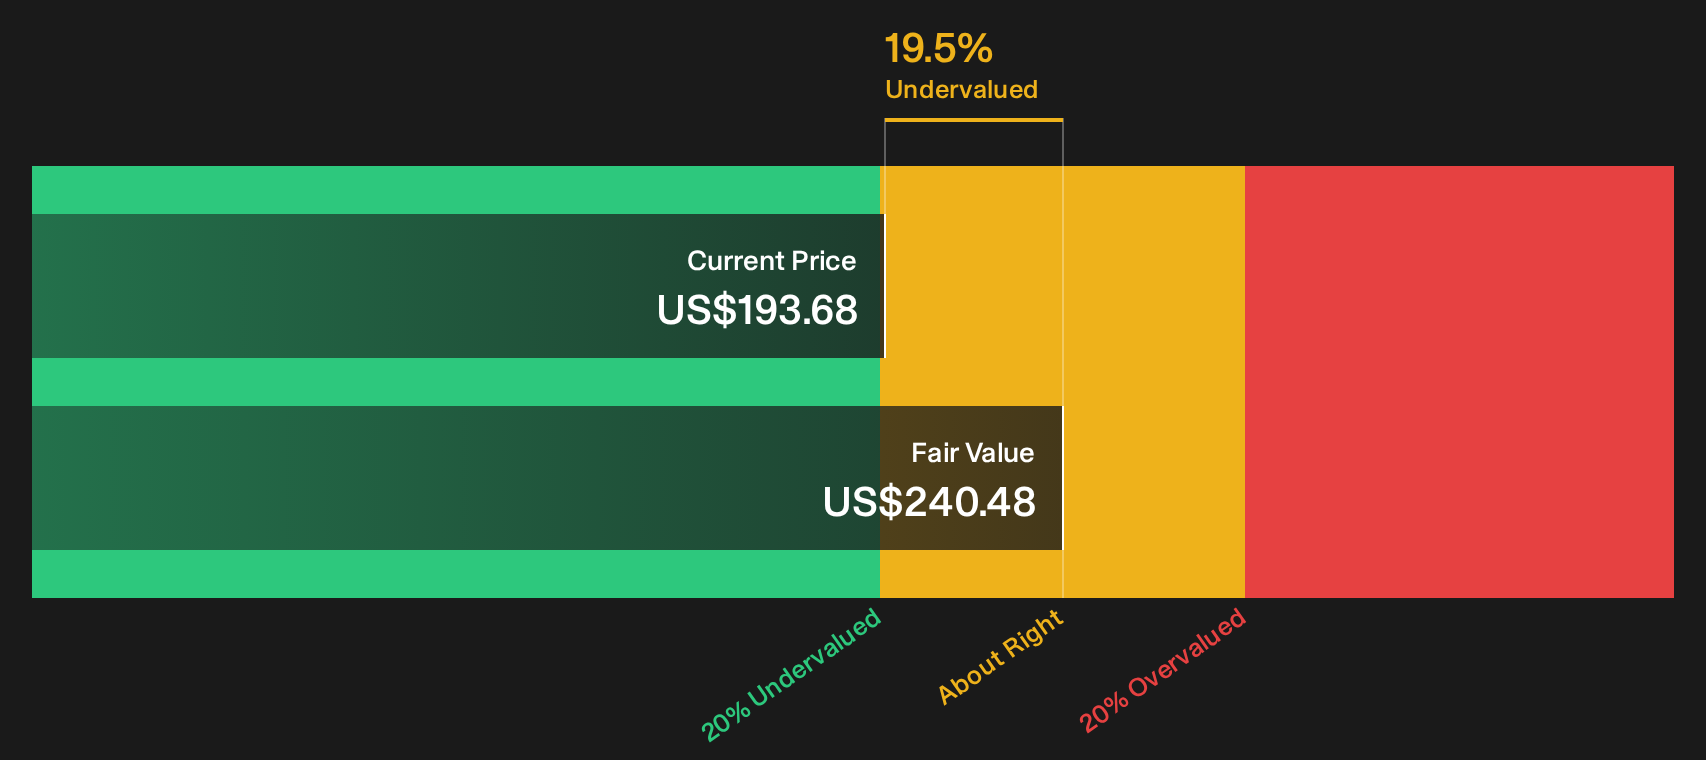
While a widely discussed SharkNinja narrative describes the stock as overvalued at a fair value of $110.73, our DCF model suggests a different view. Under that approach, SN at $193.68 trades about 19.5% below an estimated future cash flow value of $240.48, which presents the current price as discounted rather than stretched.
The gap between a DCF that suggests undervaluation and a narrative that calls the stock expensive raises a straightforward question for you: Which set of assumptions about SharkNinja’s future cash flows appears more reasonable to you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SharkNinja for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around SharkNinja is clearly split, with strong returns on one side and valuation questions on the other. Move quickly to review the underlying data, pressure test the assumptions, and weigh both 3 key rewards and 1 important warning sign.
Looking for more SharkNinja investment ideas?
Do not stop your work at SharkNinja alone. Use the Simply Wall Street Screener to spot other opportunities that fit your style before the next move happens.
- Target reliable cash generators by reviewing companies in the list of solid balance sheet and fundamentals (25 results) that pair sturdy finances with room for future decisions.
- Hunt for mispriced opportunities through the 32 high quality undervalued stocks that combine quality fundamentals with share prices that lag underlying business strength.
- Protect your downside by scanning the 32 resilient stocks with low risk scores focused on resilient operations and more measured risk profiles when markets turn choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com