


What Is Drawing Fresh Attention To Hancock Whitney (HWC)?
Hancock Whitney event sets the stage
Hancock Whitney (HWC) is heading into its upcoming Q3 report with expectations for higher earnings per share and revenue, while the stock recently moved against a backdrop of slightly trimmed forecasts.
Recent trading tells a mixed story. Hancock Whitney’s share price has risen 13.3% year to date to US$73.03, while the 1 month share price return is down 3.8% and the 3 month share price return is down 6.9%. At the same time, the 1 year total shareholder return of 37.8% and 3 year total shareholder return of about 13x suggest longer term momentum. The upcoming Q3 report and the refreshed Community Development Advisory Council are likely to influence how investors reassess both growth potential and risk around the bank’s community focused model.
Compare Hancock Whitney’s setup to a hand-picked 32 high quality undervalued stocks that pairs stronger balance sheets and cash flows with similar earnings catalysts.
Hancock Whitney now trades well below both analyst targets and intrinsic value estimates. The real puzzle is where fair value sits inside that gap as Q3 numbers and community plans reset expectations.
Most Popular Narrative: 14% Undervalued
On the narrative math, Hancock Whitney screens as undervalued, with a fair value estimate of $84.53 against the last close at $73.03, which puts fresh focus on whether execution can catch up to expectations.
The main factor is that Hancock Whitney continues to execute on organic growth, balance sheet repricing, and the integration of One Florida Bank while keeping credit quality and operating efficiency within its current ranges.
The acquisition of One Florida Bank, which closed in August 2026 and is expected to deliver full cost savings by early 2027, combined with new locations and banker hires in Texas and Florida, creates scope for higher loan and deposit volumes that can lift total revenue and operating leverage.
See why 4 investors see Hancock Whitney as 14% undervalued.
Result: Fair Value of $84.53 (UNDERVALUED)
Still, the sharp 24.16% revenue drop and 60.28% net profit decline in the latest reported quarter could push investors to question the efficiency story at Hancock Whitney.
Find out about the key risks to this Hancock Whitney narrative.
Another View: What Hancock Whitney’s P/E Is Really Saying
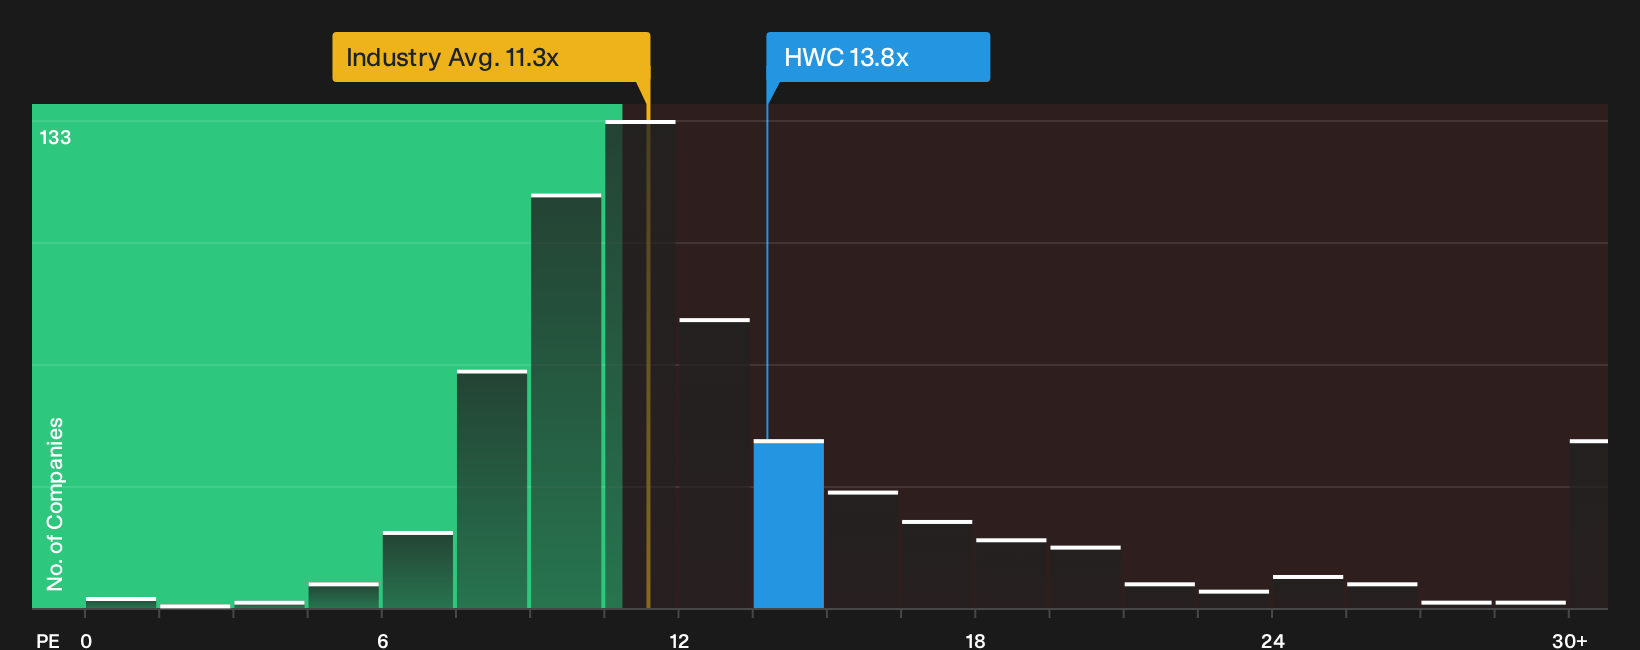
The first narrative presents Hancock Whitney as undervalued based on fair value math. The P/E picture is harsher. At 13.8x earnings, HWC trades at a higher multiple than the US Banks industry at 11.3x and above peers at 11.2x, while its fair ratio is also 13.8x. That mix points to limited potential for multiple expansion and suggests the current rating already aligns with what the fair ratio implies. For anyone weighing that against the Q3 catalyst story, the key question is whether earnings can provide sufficient support if the P/E does not change.
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Hancock Whitney so far. If you want to move quickly and rely on data instead of headlines, review the 3 key rewards and 1 important warning sign.
Ready for more ideas beyond Hancock Whitney?
Do not stop at one opportunity. Use the Simply Wall Street Screener to line up fresh candidates that match your approach before the next move passes you by.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that highlights businesses with sturdier finances backing their operations.
- Hunt for mispriced opportunities through the 20 high quality undiscovered gems that focuses on quality companies many investors may not be watching yet.
- Stack your watchlist with steadier profiles using the 32 resilient stocks with low risk scores that filters for lower risk scores without losing sight of fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com