


Earnings Report Might Change The Case For Investing In Independent Bank (INDB)
- Independent Bank Corp. reported Q3 2026 net charge offs of US$1,161,000, compared with US$1,836,000 for the same quarter last year, ahead of its after market earnings release scheduled for October 15, 2026.
- The combination of lower reported credit losses and an upcoming quarter that previously followed a revenue and earnings miss puts Independent Bank’s loan quality and earnings mix in sharp focus for anyone tracking how its franchise is evolving.
- We will now look at how Independent Bank’s Q3 net charge off disclosure might affect the broader investment narrative around credit discipline.
Scan how Independent Bank’s credit discipline compares with that of its peers by running the curated 32 resilient stocks with low risk scores as you weigh this latest net charge off update.
Independent Bank Investment Narrative Recap
To own Independent Bank, you need to be comfortable with a community focused lender that is trying to shift its book toward relationship C&I loans, low cost deposits, and more fee income from wealth management. The latest Q3 net charge off figure of US$1,161,000, which is below the prior year, does not radically change that bigger picture.
Right now the main near term swing factor is how cleanly the bank can execute its October 2026 FIS IBS core system conversion while keeping credit costs contained around office and other commercial real estate. The biggest risk remains any adverse development on criticized office credits that lifts credit costs and offsets mix shift progress.
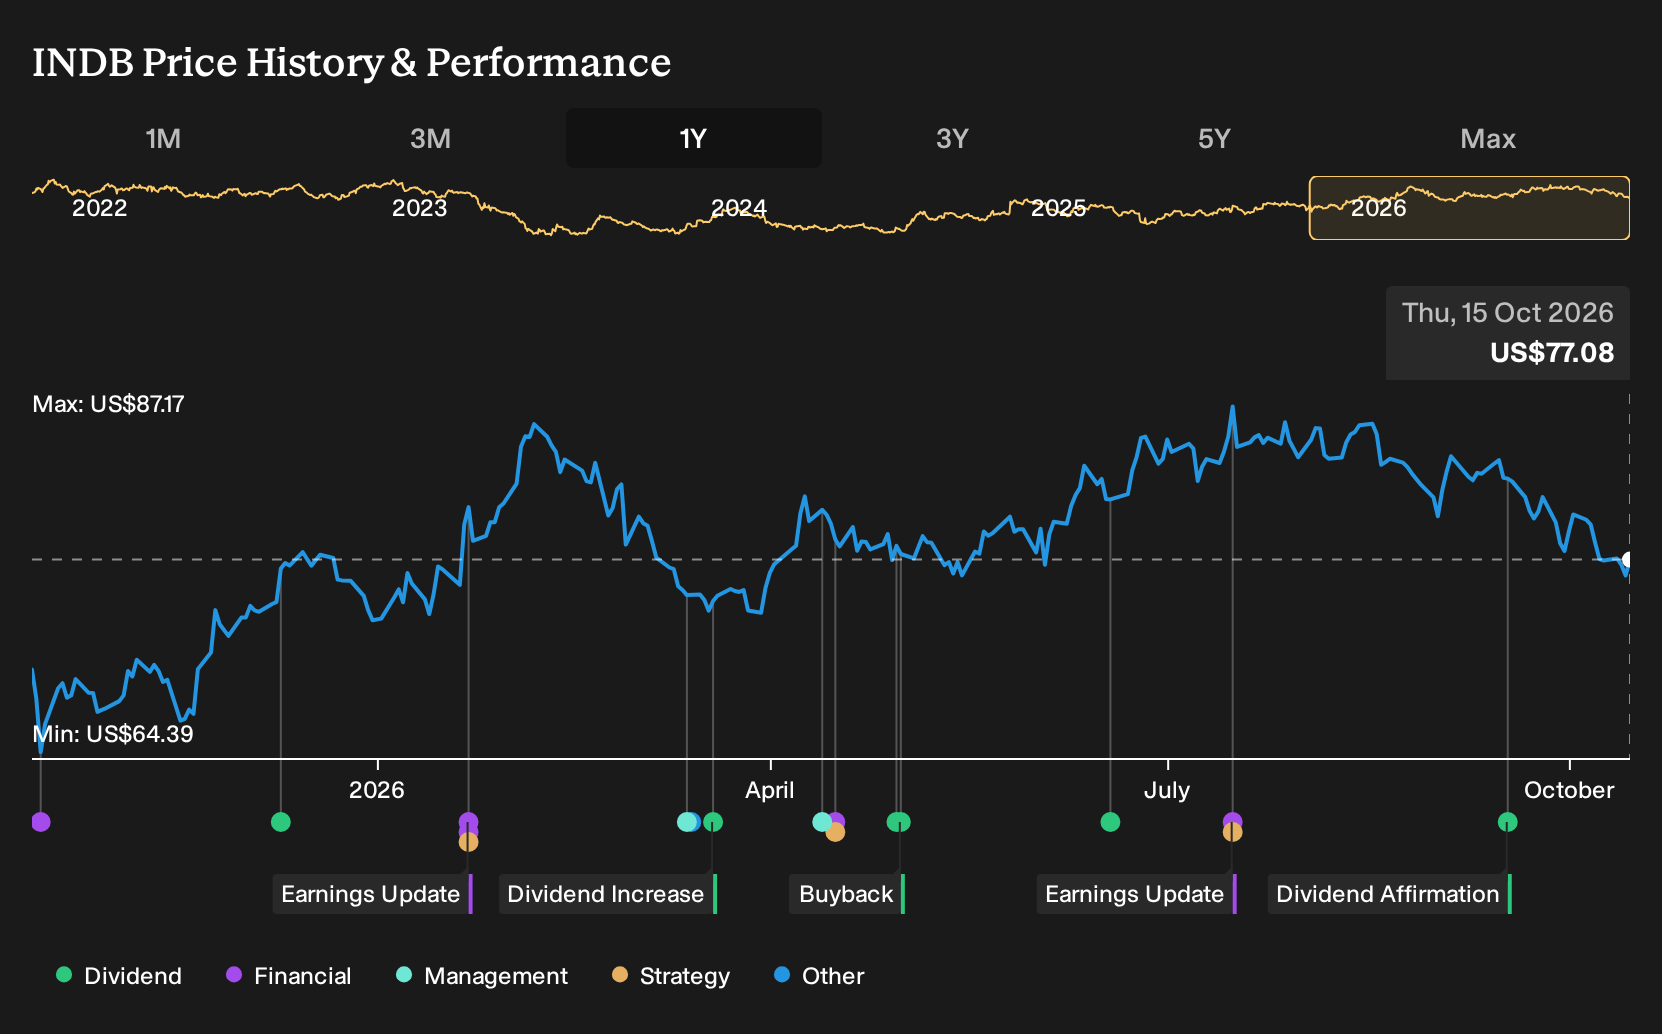
The most relevant earlier development here is the sharp miss on revenue and earnings last quarter, followed by expectations for slower Q3 revenue growth of 6.8% year on year. In that context, this latest net charge off disclosure is especially important for anyone monitoring how Independent Bank balances growth initiatives with credit discipline.
It may be useful to think of the upcoming Q3 release as a checkpoint. Investors will likely focus on how credit costs, office exposure, deposit pricing, and core conversion expenses interact. The key question is whether Independent Bank can keep charge offs controlled while reweighting toward C&I and fee income, without allowing execution or funding pressures to erode profitability.
What The Long Term Analyst Model Implies For Independent Bank
Independent Bank's current analyst framework points to revenues of US$1.2b and earnings of US$441.6m by 2029. That profile is built on 8.0% yearly revenue growth and an earnings step up of about US$170m from US$271.4m today.
Uncover why Independent Bank's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Independent Bank investors on the Simply Wall St Community currently post only two fair value estimates, stretching from about 93 to 204, which shows just how far apart private views can be. Before you anchor on either extreme, weigh those forecasts against live risks around office exposure and the upcoming core conversion, and then explore several contrasting viewpoints.
Explore another Independent Bank fair value estimate, including one that suggests it could be worth just $93.43!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Independent Bank research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Independent Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Independent Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond Independent Bank?
Independent Bank may be your starting point, but your portfolio will often benefit from a broader bench of ideas. Use the Simply Wall St Screener to line up other candidates that match the kind of risk, income, or quality profile you want to pair with a regional lender.
- If capital protection is your priority, scan for companies with historically resilient profiles using our curated 32 resilient stocks with low risk scores to see which ones meet your comfort level.
- For income focused investors, check out dependable payers and their track records through the 8 dividend fortresses and see which yields and payout patterns line up with your goals.
- If you want to broaden your watchlist with underfollowed opportunities, run the 20 high quality undiscovered gems and compare their fundamentals with what you see at Independent Bank.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com