


APA Group (ASX:APA), Why Is It Back In The Spotlight?
The New South Wales Government’s plan for 1,500MW of new firming capacity, largely gas peaking plants, has put APA Group (ASX:APA) back in focus for investors watching Australia’s energy transition.
Recent trading has been upbeat, with APA Group’s share price at A$11.19 after a 1-day share price return of 1.36% and a 7-day move of 4.68%. The year-to-date share price return of 23.78% and 1-year total shareholder return of 30.66% point to momentum building alongside policy tailwinds such as the NSW firming tender.
Scan for other infrastructure plays benefiting from similar policy support by moving through the hand picked 42 power grid technology and infrastructure stocks tied to grid reliability and energy transition themes.
APA Group’s price has run hard while consensus valuation still sits lower, even as some intrinsic models point far above the screen. Where does fair value really land in that kind of spread?
Most Popular Narrative: 16% Overvalued
APA Group last closed at A$11.19 while the most followed narrative pegs fair value closer to A$9.69. This puts recent strength against a more cautious valuation anchor built on a 7.18% discount rate and detailed earnings assumptions.
The ongoing global emphasis on energy security and infrastructure resilience is creating tailwinds for APA's core pipelines and storage assets, contributing to long-term contracted volumes and pricing power, and supporting earnings visibility and margin stability. APA's expansion of its organic growth pipeline (from $1.8bn to $2.1bn) in projects supporting LNG exports, domestic supply, and midstream gas-fired power generation positions the company to participate in industry and regulatory support for modernized, reliable gas infrastructure, and this may influence EBITDA and margin performance over multiple years.
See why 73 investors see APA Group as 16% overvalued.
Result: Fair Value of A$9.69 (OVERVALUED)
Still, faster renewable uptake or tighter climate rules could pressure APA Group’s long term gas volumes and contract renewals, and this may unsettle today’s valuation story.
Find out about the key risks to this APA Group narrative.
Another View: APA Group Through A Cash Flow Lens
The analyst narrative tags APA Group as 16% overvalued at A$9.69, yet the Simply Wall St DCF model points in a very different direction. On that framework, APA Group’s current A$11.19 price sits far below an estimated future cash flow value of A$27.34, which implies a wide valuation gap that investors need to reconcile for themselves.
Put simply, the market price, the analyst consensus and the SWS DCF model are telling three different stories about APA Group’s worth. The question is which story you trust most, and what would make you change your mind if the inputs shift.
Look into how the SWS DCF model arrives at its fair value.
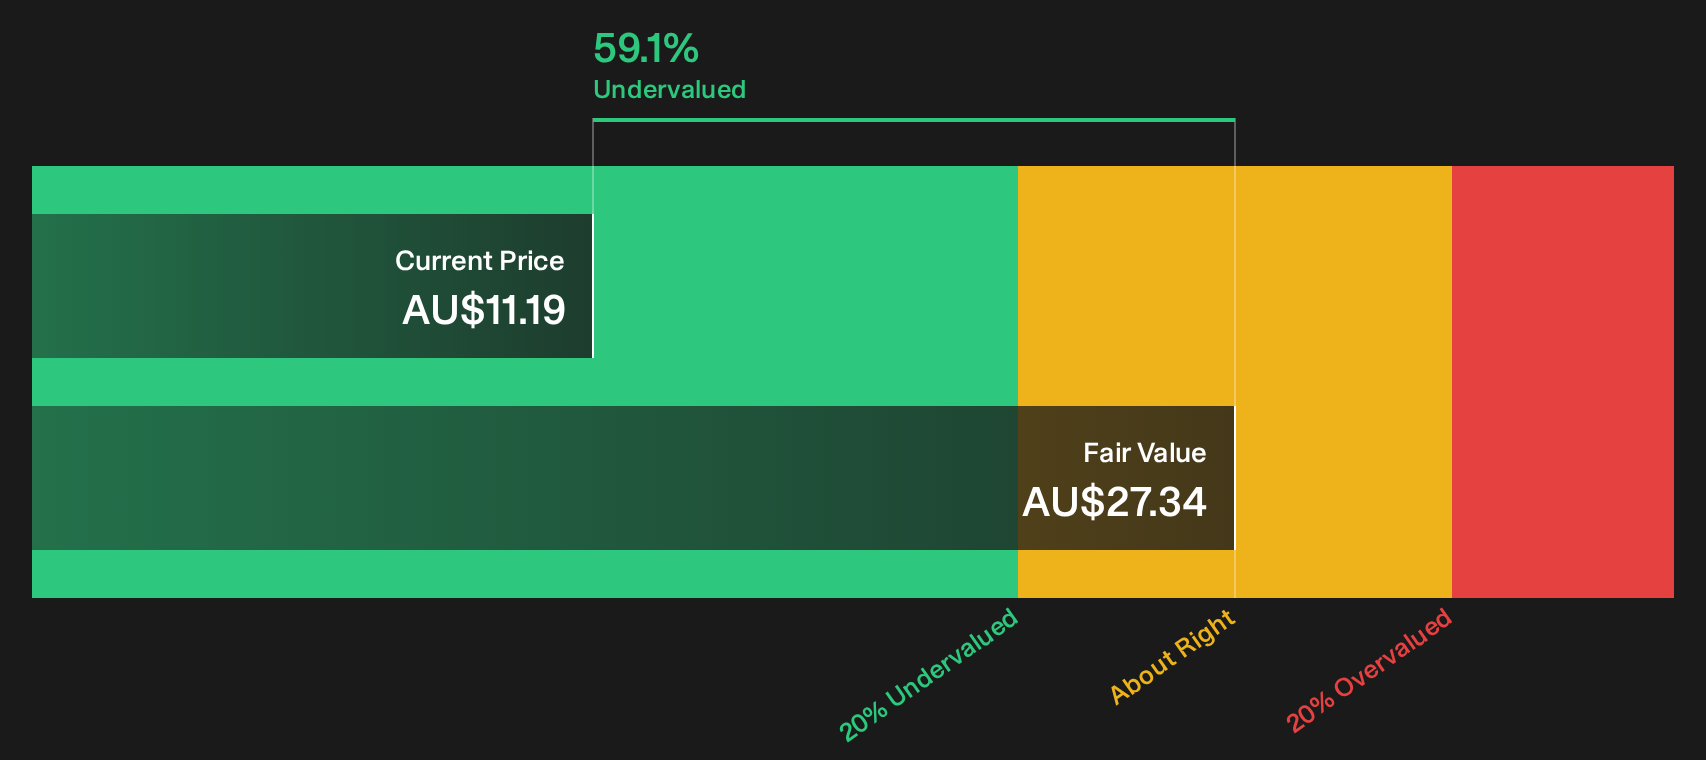
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out APA Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split signals in APA Group leave you undecided, look at the numbers yourself now so you can build your own view from the ground up. To weigh both sides of the story in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond APA Group?
Do not stop with one stock. Use the Simply Wall St screener to surface fresh opportunities that fit your risk tolerance and income goals before the crowd notices.
- Target strong cash flow potential by scanning for companies trading on compelling valuations through the 4 high quality undervalued stocks.
- Lock in income ideas by filtering for resilient payers using the 3 dividend fortresses.
- Dial down volatility by focusing on resilient businesses with healthier balance sheets through the 6 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com