


Did EV Program Changes Just Shift Magna International's (TSX:MG) Investment Narrative?
- Magna International has moved into focus after fresh commentary on global auto production, EV program adjustments and supplier profitability, alongside its push into EV battery enclosures and driver-assistance components.
- What really matters for investors is how Magna International’s ongoing restructuring and cost discipline intersect with changing vehicle production schedules and capital spending priorities.
- Next, the investment narrative for Magna International will be tested against its restructuring push and the renewed focus on electrification programs.
Scan beyond Magna International and compare how other auto and electrification suppliers are positioned on balance sheet strength and cash generation by using our curated list of solid balance sheet and fundamentals (8 results).
Magna International Investment Narrative Recap
To own Magna International, you need to be comfortable with a global auto supplier that is reshaping its cost base while production schedules and EV programs keep shifting. The basic belief is that restructuring, operational discipline and a heavier tilt to battery enclosures and driver assistance can support healthier margins even if volume growth stays muted.
The recent commentary around production forecasts and EV program changes matters because it touches both sides of that equation. The key near term catalyst is evidence that restructuring actually lifts margins and free cash flow. The biggest risk is that weaker volumes, mix and tariffs dilute that operating progress and keep margins stuck.
One announcement that lines up closely with the latest headlines is Magna International’s emphasis on operational excellence and restructuring actions targeted at margin expansion. Investors are now judging every update on global production, EV launch timing and supplier pricing against that plan, because lower volumes or softer EV demand can blunt the benefits of any efficiency gains.
The same message applies to free cash flow. Management has described a path where capital spending normalizes after heavy investment in battery enclosure assembly, which potentially creates more room for cash generation even if revenue only edges higher. Execution on those battery and ADAS programs, alongside managing tariffs and foreign exchange swings, remains central to how powerful that cash flow story becomes.
Magna International’s current earnings of $761.0 million are projected in analyst models to reach $1.9 billion by 2029, implying an earnings increase of about $1.1 billion. Revenues tied to that outlook are pegged at $43.9 billion in the same year and are expected to remain fairly flat over the next 3 years.
Uncover why Magna International's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
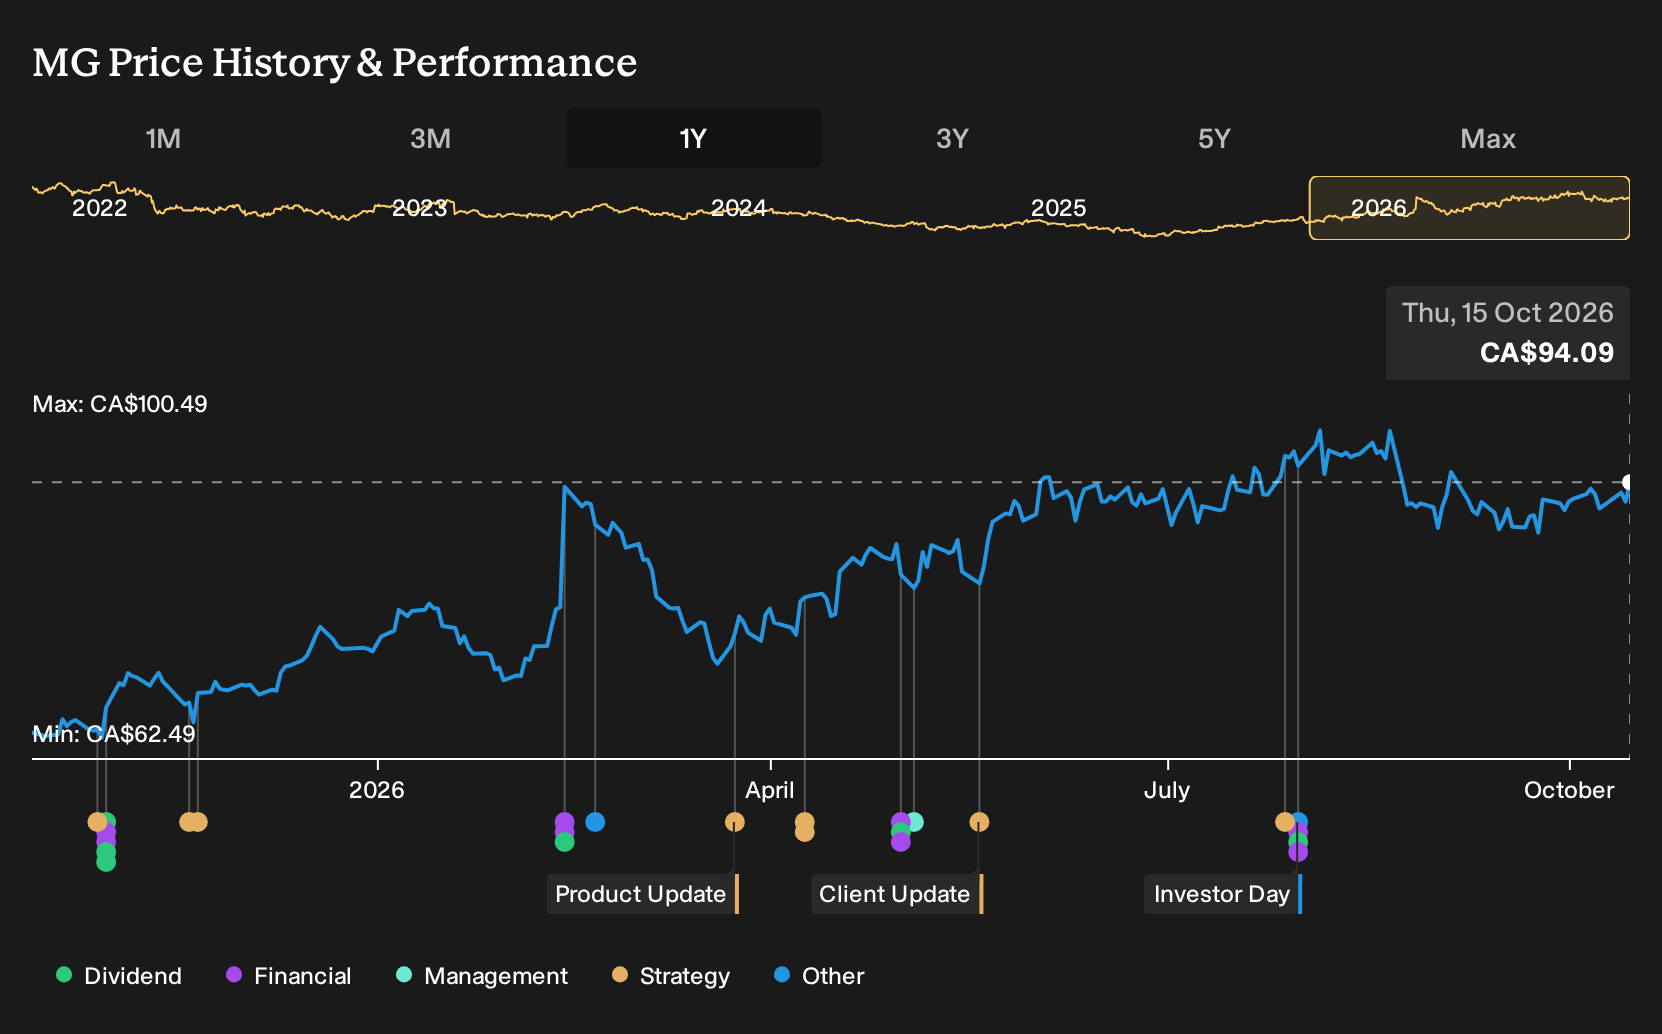
Exploring Other Perspectives
One alternate view on Magna International puts electrification risk front and center. The most cautious analysts assumed revenue of about $42.3b and earnings of $1.6b by 2029, versus the consensus $43.9b and $1.9b. That more pessimistic script could shift again once the latest production and EV headlines are fully absorbed.
Explore 3 other Magna International fair value estimates, including one that suggests it could be worth just CA$91.60.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Magna International research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Magna International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Magna International's overall financial health at a glance.
Looking for more investment ideas beyond Magna International?
If Magna International has sharpened your thinking about auto suppliers and electrification, it can help to stack it up against other opportunities with different risk and income profiles by using the Simply Wall St Screener.
- For investors who want income front and center, scan for resilient payers offering strong yields through the 3 dividend fortresses.
- If capital preservation sits high on your list, narrow the field to steadier businesses by starting with a 8 resilient stocks with low risk scores.
- For those hunting for potential mispriced opportunities, cast a wider net across quality companies trading below their implied worth using the 6 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com