


DFS Furniture (LSE:DFS) Stock Looks Cheap as Margins Recover
DFS Furniture stock has edged up in recent weeks, yet at around £1.48 it still trades below a trailing P/E of 10 and at a discount to some valuation models that sit closer to £1.70. The market is treating this as a cautious recovery story. The headline from these full year numbers is margin repair. Net profit margin over the last twelve months is 3.3%, compared with 2.3% a year earlier, and that shift matters more for the long term than any single quarter of sales noise.
Like the margin repair story at DFS Furniture but concerned that a low P/E could still mask balance sheet or cash flow risks? Check out our hand picked list of resilient businesses in the list of solid balance sheet and fundamentals stocks (9 results).
FY 2026 Earnings Summary
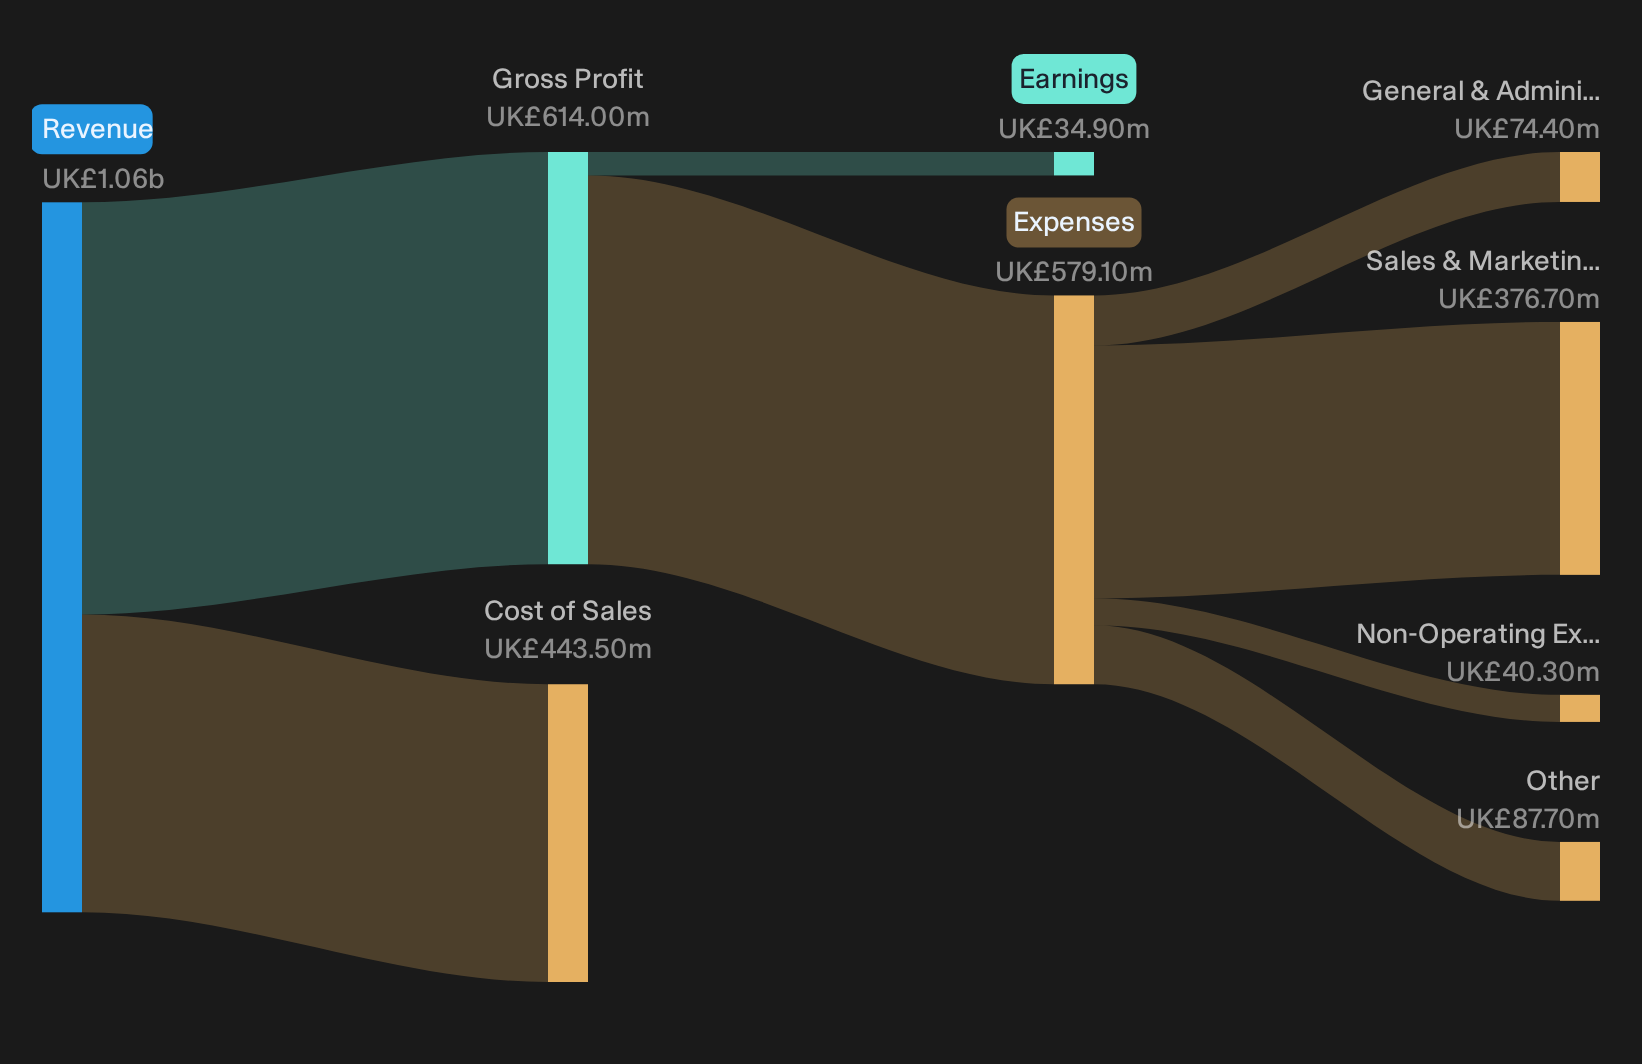
- Revenue (FY 2026 vs FY 2025): £1,057.5m vs £1,030.3m (reported 2.6% top line increase)
- Net Income, Excl. Extra Items (FY 2026 vs FY 2025): £34.9m vs £24.2m (reported improvement in profitability)
- Basic EPS, Earnings Per Share (FY 2026 vs FY 2025): £0.1509 vs £0.1048 (reported earnings per share uplift)
- Net Profit Margin, Trailing 12 Months vs Prior Year: 3.3% vs 2.3% (margin repair continues from the prior year level)
If you prefer clear charts to dense tables and raw earnings figures, explore DFS Furniture's full financial picture, including a clear view of its valuation and recent margin repair, in the company report for DFS Furniture.
DFS Furniture: Margins, Cash, And The Bullish Angle
For anyone leaning positive on DFS Furniture, the latest year gives some support. Revenue edged higher to £1,057.5m while net income excluding extra items rose to £34.9m and basic EPS reached £0.1509. Net profit margin moved from 2.3% to 3.3%, which fits the margin repair story more than a one off bounce. Strong free cash flow of about £40.3m, lower net debt at £69m and leverage at 0.9x all point to a cleaner balance sheet that supports that recovery narrative.
Cyclical Risks, Volume Softness, And The Bearish Angle
More cautious investors still find ammunition. Group order intake fell 1% with softer trading in the second half and Q1 FY27 orders declined 2.5%, which keeps the cyclical demand worry alive. Underlying operating costs increased about 3% and included higher employment expenses and extra marketing, so cost inflation remains a grind. Management also talks about a relatively flat market as the planning base. That framing keeps the consumer and housing sensitivity front of mind, even as margins and cash flow move in the right direction.
After cost inflation, softer orders and a mixed dividend record, review our independent risk analysis for DFS Furniture which shows 1 important warning sign to see whether hidden structural issues lurk.Turn Your Research Into Action
If DFS Furniture's margin repair story and low P/E have caught your eye, register for free with Simply Wall St and add it to a Watchlist so you can track the share price against fair value and watch how future results shape the thesis. When you decide to build or adjust a position, use the Portfolio Command Center to cut through market noise and focus only on the key developments that matter to your holdings. For longer term context and fresh angles, tap into the collective insights inside the Community and see how other investors are interpreting the same data. By spotting hidden catalysts and potential risks early, you give yourself a better chance of staying a step ahead of the market.
Seeking Fresh Alternatives Beyond DFS Furniture
Opportunities move fast. Fresh ideas can gain momentum, lose steam or get caught flying under the radar for now. Scan these curated shortlists before the crowd and act now.
- Target resilient income streams by reviewing hand picked businesses in the 4 dividend fortresses while yields still look compelling and before payout trends start dropping off investor radars.
- Spot early breakout potential by scanning curated growth stories in the 5 high quality undiscovered gems while they remain under the radar for now and pricing still reflects limited attention.
- Track market shifts by analysing cash generative companies in the list of solid balance sheet and fundamentals stocks (9 results) before fresh demand sends quality balance sheets flying up investors' priority lists.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com