


NCR Voyix Stock Gets Fresh Client Wins Across Restaurants And Retail
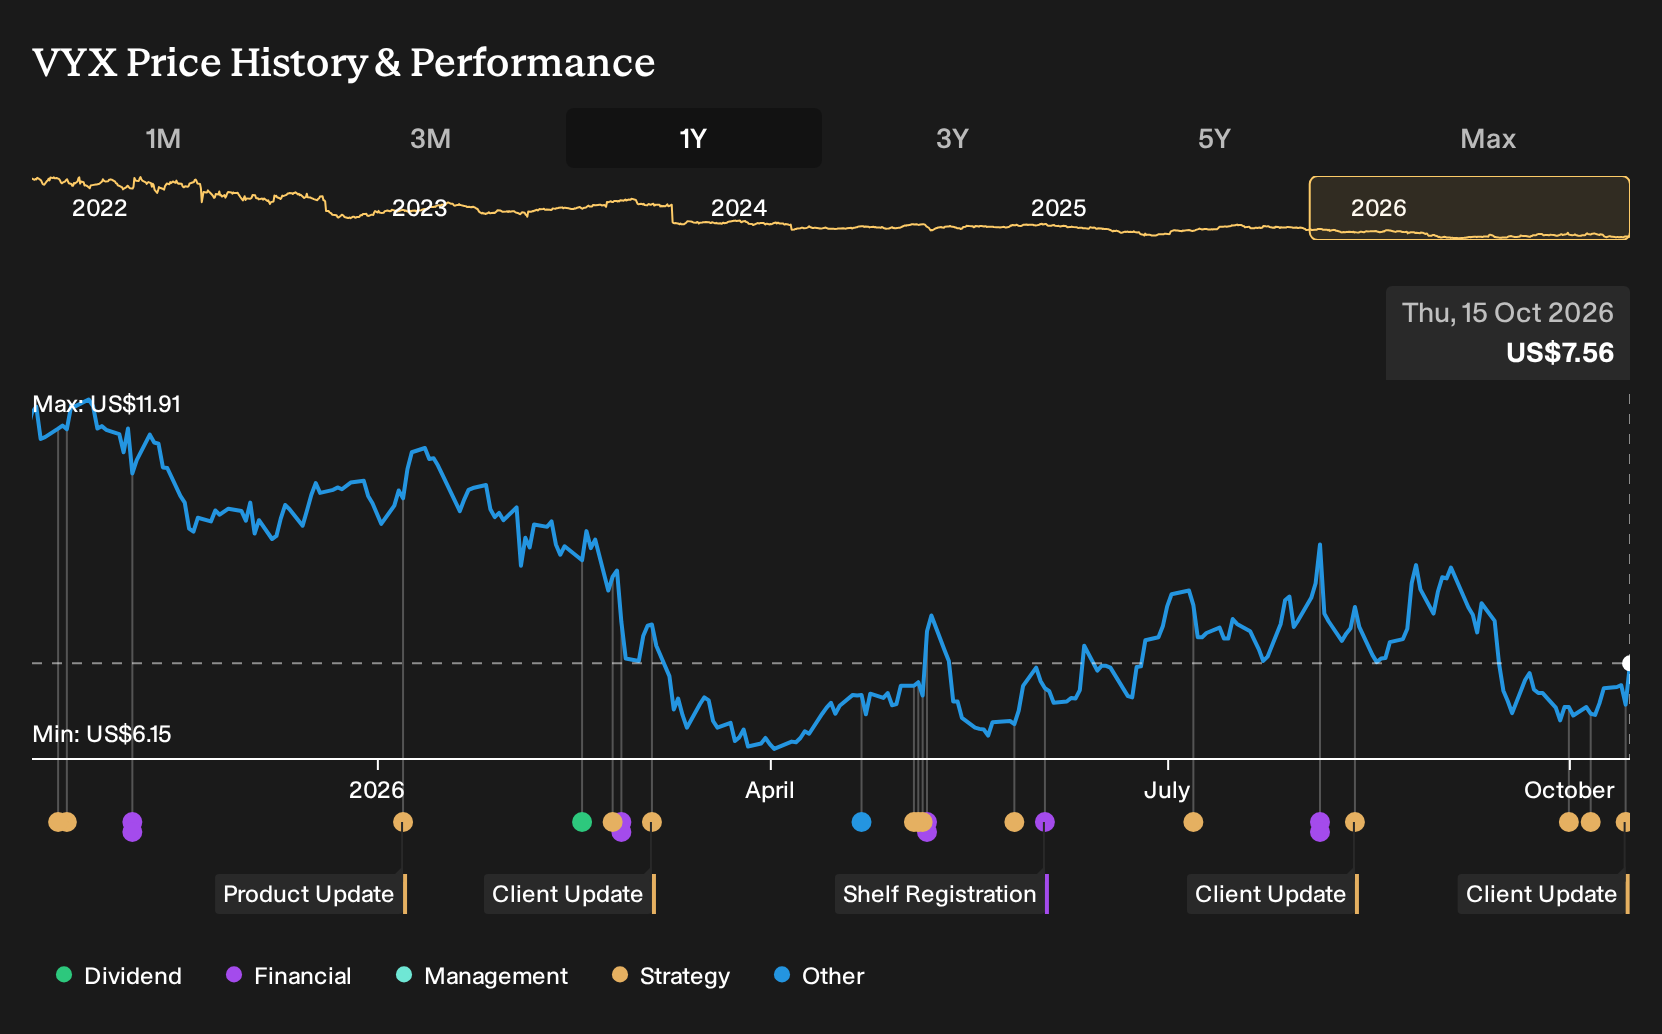
- NCR Voyix reported several new client deals, including Sbarro adopting Aloha Next POS and Voyix Pay across nearly 300 U.S. locations and a multi-year enterprise agreement with Rutter’s to deploy the Voyix Commerce Platform.
- These agreements point to broader adoption of NCR Voyix’s software, payments and forecourt solutions by multi-site retailers that are seeking more unified, standardized technology across store networks.
- We now examine how NCR Voyix’s investment narrative is influenced by Sbarro’s rollout of Aloha Next and Voyix Pay.
NCR Voyix Investment Narrative Recap
To own NCR Voyix, you need to believe the shift toward software, payments and recurring revenue can offset pressure on legacy hardware and weak recent share performance. The short term swing factor is whether new platform wins translate into steadier transaction and subscription streams. These client announcements help narrative confidence but do not, on their own, change it.
The biggest near term risk still sits in execution and balance sheet strain. Earnings are forecast to decline, interest coverage is tight, and hardware headwinds remain real. New contracts help utilization of existing platforms, yet do not fully resolve margin pressure, elevated investment needs or the risk of losing large enterprise customers.
The Sbarro rollout of Aloha Next and Voyix Pay across almost 300 U.S. locations appears most directly tied to the story investors are watching. It shows NCR Voyix winning both software and payments share in restaurants, which is where the higher margin recurring mix sits. That matters more than a one off hardware order.
What investors may focus on next is execution quality. Smooth deployment, stable uptime and reliable data integration would support the case that NCR Voyix can scale similar multi year agreements without heavy one time costs that drag on margins. Any operational issues, by contrast, would add to concerns about earnings pressure and customer concentration risk.
NCR Voyix's current earnings are $42.0 million, with analysts projecting revenue to decline 10.1% per year and earnings to reach $5.6 million by 2029. That path implies an earnings decrease of $36.4 million from earnings today and is presented alongside analyst forecasts that call for $2.0 billion of revenue in the same 2029 estimate year.
Uncover why NCR Voyix's fair value indicates a 70% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Pricing power is where the most optimistic analysts push hardest on NCR Voyix. Before this Sbarro deal, the bullish camp was modeling 2029 earnings of about $11.9 million on $2.0b of revenue, while the most cautious were closer to $4.9 million. You can see how far opinions stretch. Use this news to test which story you find more convincing.
Explore 3 other NCR Voyix fair value estimates, including one that suggests as much as 436% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your NCR Voyix research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NCR Voyix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCR Voyix's overall financial health at a glance.
Looking for more NCR Voyix style investment ideas?
If the NCR Voyix story has you thinking about where else recurring revenue, balance sheet strength and risk control might intersect, the Simply Wall St screener can surface other companies that fit those themes in a few clicks.
- For investors who want potential mispricing with quality on their side, scan a curated set of 32 high quality undervalued stocks that pair solid fundamentals with appealing valuations.
- If income stability is your priority, narrow the field to companies offering reliable cash returns to shareholders through our focused view on 8 dividend fortresses.
- When capital preservation comes first, concentrate on defensiveness by filtering for 32 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com