


Eversource Energy (ES) Lands Federal Grid Funding As Valuation Debate Stays Open
Eversource Energy (ES) just secured up to $47.7 million in federal funding to deploy dynamic line rating technology across its 4,000 mile transmission grid. Investors are weighing what this means for long term capital needs and returns.
Eversource Energy’s shares trade at US$65.99 after a 1 day share price return that slipped 1%, capping a 90 day decline of about 11.6%. This comes even as the 3 year total shareholder return of roughly 40.6% points to a much stronger longer term record.
Recent headlines around the federal funding award, pressure from Massachusetts officials to speed up ratepayer refunds, and localized power surge inspections in Connecticut give investors fresh information to reassess risk. This helps explain why short term share price momentum has faded even though longer horizon returns still look more resilient.
Scan a curated set of grid and infrastructure plays that align with the Eversource Energy story through our 42 power grid technology and infrastructure stocks
Eversource Energy looks like a solid regulated utility with electricity, gas and water all under one roof, yet the share price has slid over the past quarter. After that kind of pullback, do the current numbers argue for fair, rich or still demanding pricing?
Most Popular Narrative: 10% Undervalued
Eversource Energy’s most followed valuation story pegs fair value around $73.58, which sits above the recent $65.99 share price and presents the current pullback as a discount rather than a premium.
Balance sheet strengthening and a more limited equity financing plan are backed by US$1.7b of Aquarion sale proceeds, US$1.5b of junior subordinated notes, and up to US$1.8b of expected storm cost securitizations. These factors support FFO to debt metrics and reduce expected share issuance, which is likely to be relevant for per share earnings and cost of capital.
See why 17 investors see Eversource Energy as 10% undervalued.
Result: Fair Value of $73.58 (UNDERVALUED)
Still, the Eversource Energy story could look very different if regulators tighten allowed returns further or if additional Revolution Wind charges affect reported earnings.
Find out about the key risks to this Eversource Energy narrative.
Another View: Cash Flows Paint A Tougher Picture
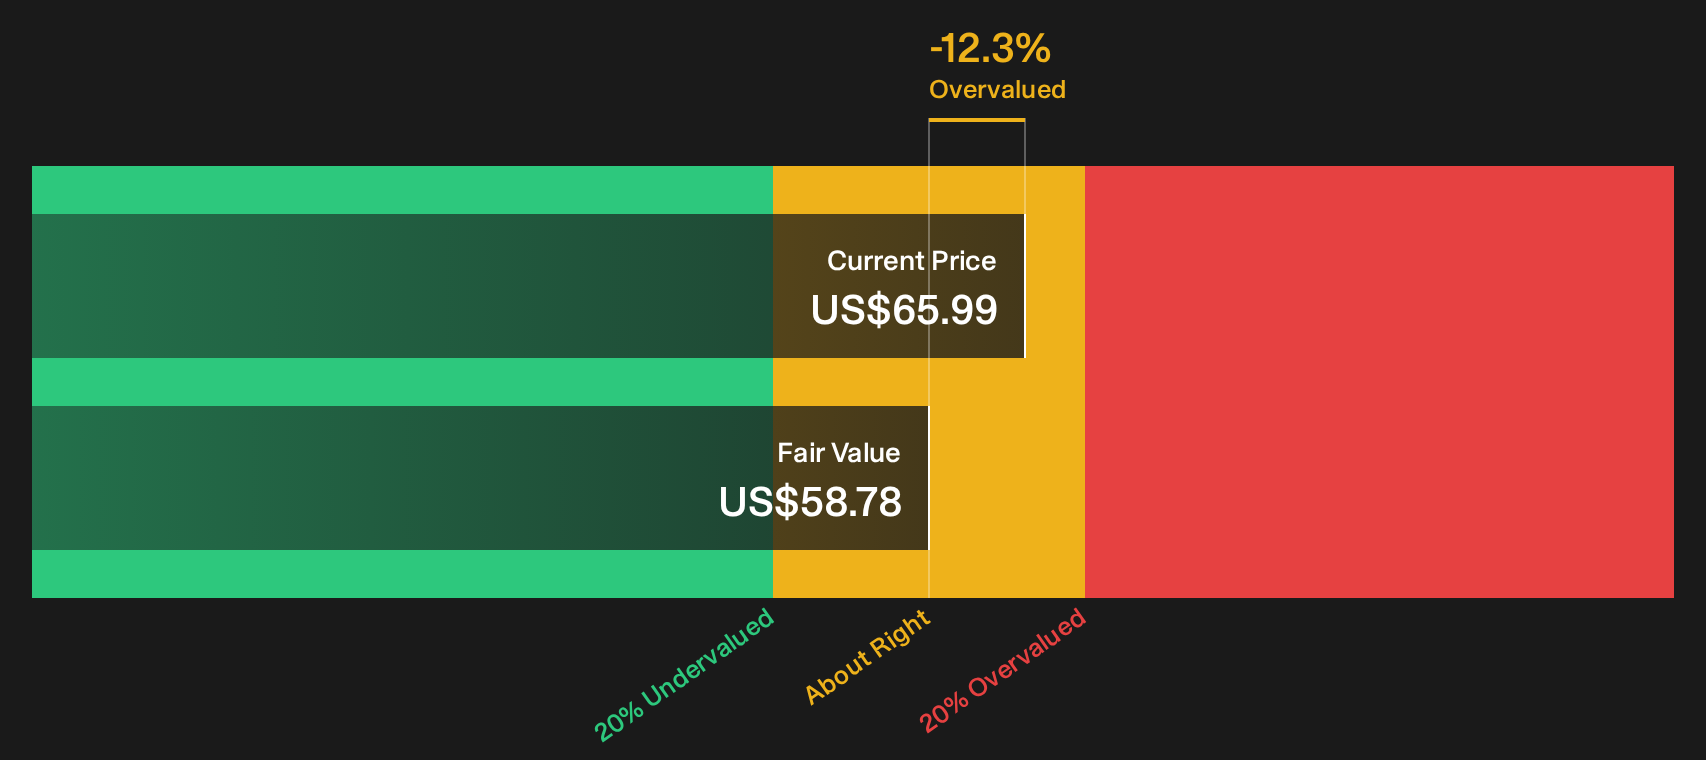
There is a catch. While earnings based narratives frame Eversource Energy as roughly 10% undervalued at $73.58 fair value, the SWS DCF model points the other way and puts future cash flow value closer to $58.78. On that view, today’s $65.99 price looks expensive rather than cheap. Which story do you rely on more for long term decisions?
For readers who lean on cash flow based work, it is worth seeing exactly how that conclusion is reached through the Look into how the SWS DCF model arrives at its fair value.
The underlying fair value path in that SWS DCF model is visualised here, which can help you compare the cash flow view against the earnings focused narrative you have just read
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eversource Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Eversource Energy is clearly split, with meaningful concerns sitting right alongside genuine bright spots that keep long term holders interested. If you want to move from headlines to hard numbers and form an independent view, start with a clean look at the 4 key rewards and 2 important warning signs.
Looking for more Eversource Energy style investment ideas?
If Eversource Energy has you thinking about grid reliability, cash flow resilience and downside protection, it makes sense to widen your lens and scan similar opportunities now.
- Target resilient income by reviewing a curated set of companies built as potential income engines through the 8 dividend fortresses.
- Hunt for quality at a reasonable price by checking companies that combine strong fundamentals with appealing valuations using the 20 high quality undiscovered gems.
- Prioritise capital preservation and steadier rides by focusing on businesses that score well for resilience through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com