


New Bobbi Brown Chief Has The Estée Lauder Stock Case Changed?
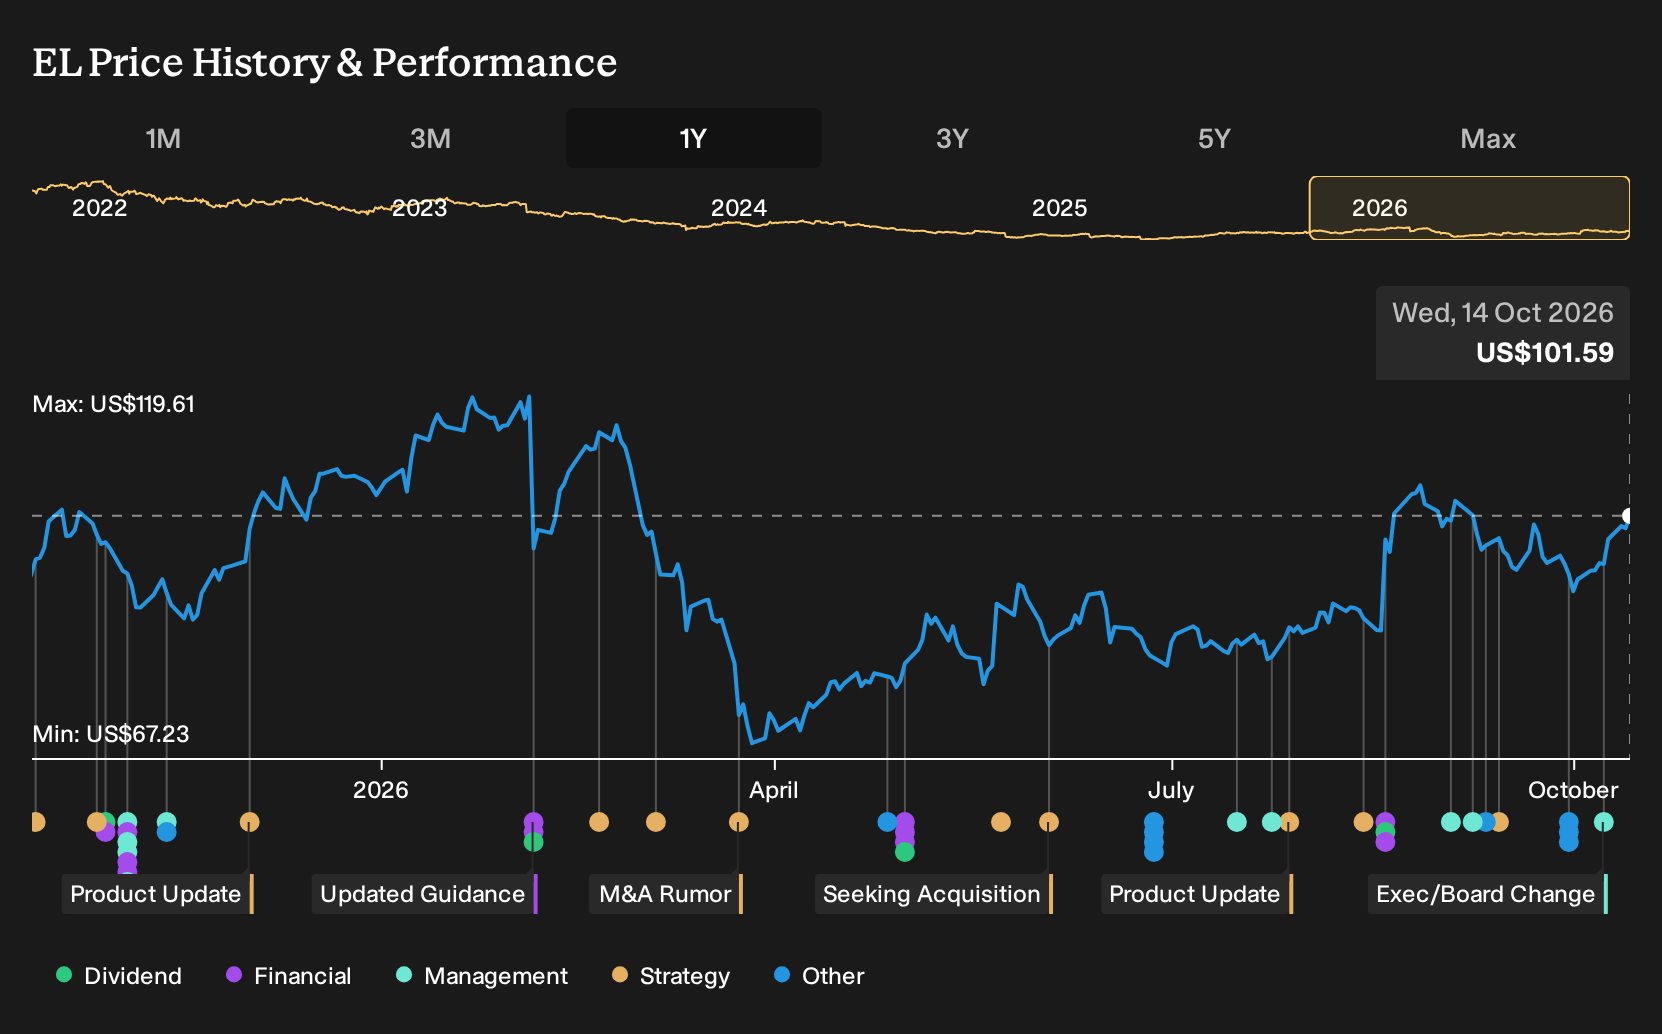
- Estée Lauder Companies appointed Gaétane Baudry as Senior Vice President and Global General Manager of Bobbi Brown on 8 October 2026, giving the makeup label a leader with extensive luxury beauty experience across Asia and global markets.
- Her background in redefining brand platforms, sharpening category strategy and strengthening omnichannel execution points directly to Bobbi Brown’s potential role in Estée Lauder Companies’ long term brand mix and execution priorities.
- We will examine how Estée Lauder Companies’ investment narrative intersects with Gaétane Baudry’s appointment to lead Bobbi Brown’s global brand strategy.
Scan how Estée Lauder Companies fits into the wider beauty and consumer space by comparing it with our handpicked 20 high quality undiscovered gems that are still flying under most investors' radars.
Estée Lauder Companies Investment Narrative Recap
To own Estée Lauder Companies, an investor needs to believe that the Profit Recovery and Growth Plan, the One ELC model and channel mix shift can steadily support higher margins on a roughly mid single digit revenue growth profile. Gaétane Baudry’s appointment at Bobbi Brown supports this brand led thesis but does not change the near term focus on execution in skin care, fragrance and core markets.
The biggest short term swing factor still sits in travel retail stability and clean implementation of workforce and door reductions. The largest risk remains that restructuring and any governance overhang disrupt consumer facing execution or add costs. This leadership change is relevant for long term brand health rather than near term profit metrics.
The multi year partnership between Reliance Foundation and The Estée Lauder Companies Charitable Foundation to support girls and young women in India is the most relevant adjacent announcement. It ties into Estée Lauder Companies’ long running exposure to emerging markets, especially Asia, and to long term brand equity in regions that matter for prestige beauty demand.
For catalysts, that program does not change earnings drivers on its own. However, it sits alongside the shift toward more balanced geographic and channel exposure. It adds another data point that the group is investing time and resources into markets like India while still managing risks in travel retail, governance questions and a high debt load.
Estée Lauder Companies’ narrative projects US$17.1b in revenue and US$1.5b in earnings by 2029, based on analyst models that assume 4.4% yearly revenue growth and an earnings increase of about US$1.3b from US$182.0m today.
Uncover why Estée Lauder Companies' fair value aligns with its current price.
Exploring Other Perspectives
One alternate view centers on Estée Lauder Companies’ cash generation. Bullish analysts were already expecting about US$17.8b of revenue and US$1.7b of earnings by 2029, compared with consensus at US$17.1b and US$1.5b. If Gaétane Baudry’s leadership at Bobbi Brown reshapes priorities, those pre news assumptions could shift. You can weigh both narratives and decide which you find more realistic.
Explore 5 other Estée Lauder Companies fair value estimates, including one that suggests up to 18% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Estée Lauder Companies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Estée Lauder Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Estée Lauder Companies' overall financial health at a glance.
Looking for more Estée Lauder Companies sized investment ideas?
Once you have formed a view on Estée Lauder Companies, it can help to line that thesis up against other opportunities that match your risk tolerance, income needs and balance sheet preferences. The Simply Wall St Screener lets you move from one stock story to a full watchlist in a few minutes by filtering for the traits that matter most to you.
- If you want potential upside with carefully filtered smaller stocks, consider using our screener focused on 13 elite penny stocks with strong financials that already show stronger balance sheets and fundamentals than many of their peers.
- For investors who care most about quality at a reasonable price, filter the market for 32 high quality undervalued stocks that combine solid cash flows with healthier financial profiles.
- If resilience matters more than excitement in your portfolio, narrow your options to a 32 resilient stocks with low risk scores that score well on our risk metrics and business durability checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com