


GoDaddy (GDDY) Stock May Still Offer Value Following Fraud Lawsuit Claims
GoDaddy has delivered a 5 year share price gain that long term holders will be very aware of. With the stock recently closing at US$107.29, the live question is whether that price still lines up with what its earnings can support.
- Over the past 5 years, GoDaddy has returned 54.3% which puts real weight on whether the current valuation is fully backed by the profit stream the business generates.
- Fresh class action securities lawsuits around alleged misstatements on promotional pricing and customer behavior may influence how investors think about the reliability and trajectory of future earnings.
- Your read on GoDaddy is one view; the desks covering it have another. See what analysts think GoDaddy's shares could be worth.
The issue now is whether GoDaddy's recent share price levels are adequately justified by its earnings power today and what investors expect those profits to look like in future years.
If you are comparing GoDaddy with alternatives that face similar AI and pricing questions, a focused starting point is a screen of 38 AI small caps
Is GoDaddy Still Cheap on Earnings?
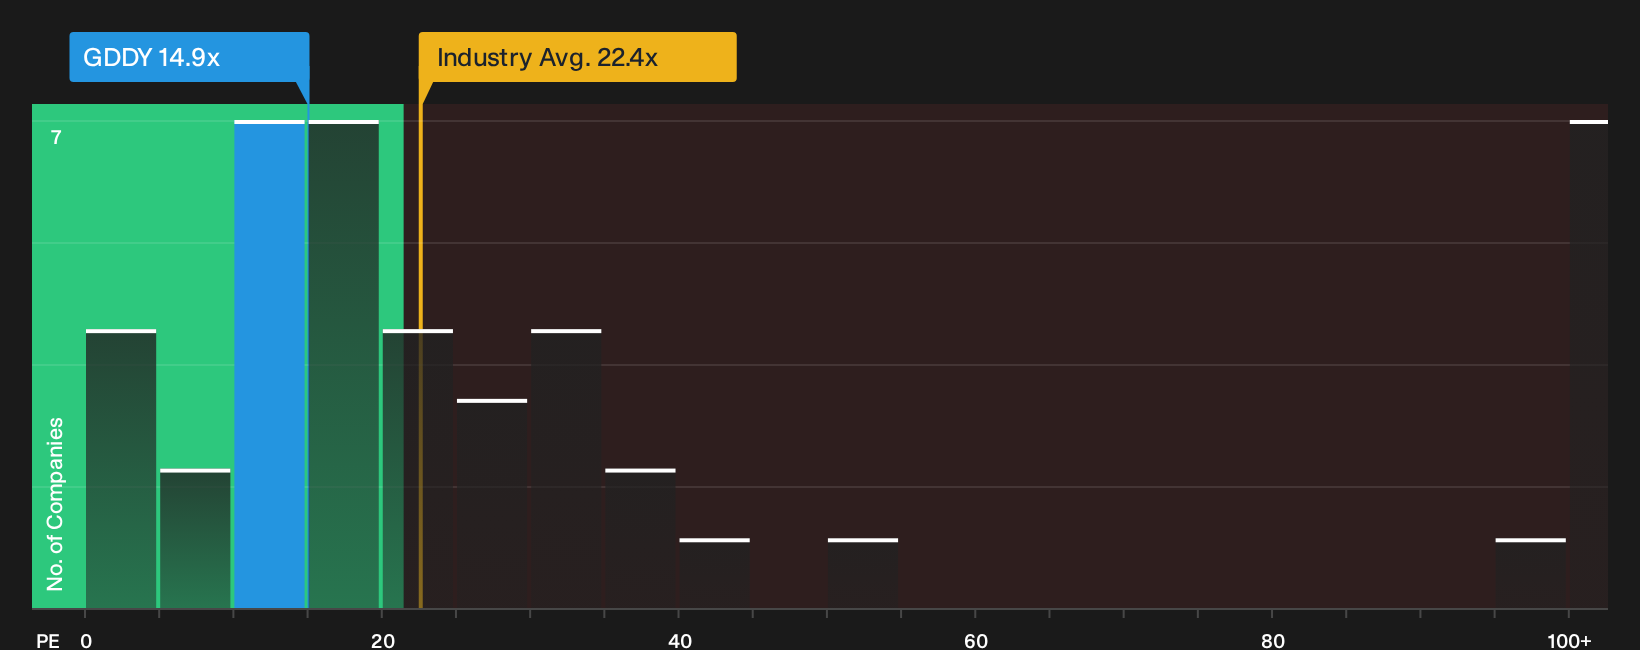
The P/E ratio is a straightforward way to assess what you are paying for each dollar of GoDaddy earnings. On this basis, GoDaddy trades on about 14.9x earnings, which is well below the broader IT sector average of roughly 22.4x and the peer group on about 32.1x.
The fair multiple implied by the valuation model, which blends the firm’s growth profile, margins, size and risk, is noticeably higher than GoDaddy’s current 14.9x. Because the recent class action allegations around promotional pricing have pressured sentiment around the business model, that gap indicates the stock currently reflects a meaningful amount of caution compared with both sector peers and what the model presents as a central case. Explore the numbers behind GoDaddy's P/E valuation.
The GoDaddy Narrative: What Would Justify Today's Price?
GoDaddy Narratives on Simply Wall St pick up where the P/E puzzle leaves off and spell out what mix of future growth, profitability and earnings resilience would need to play out for the current share price to look meaningfully high or low. Rather than leaning on a single multiple or model output, each narrative sets out the assumptions that sit behind its fair value view so you can track those against the actual numbers as results arrive.
Community views on GoDaddy split between those who see extra upside from AI execution and those who think most of that story is already in the price.
Bull case: 29% undervalued
"The current numbers, including a 33.4% normalized EBITDA margin, trailing 12 month free cash flow of US$1.73b and share repurchases that reduced the share count by 7%, indicate the stock price may not fully reflect what this business could be worth..."
Discover why this Narrative puts GoDaddy at 29% undervalued.
Bear case: roughly fairly valued
"The current view that GoDaddy is fairly valued and bullish implies the share price already reflects meaningful long term contribution from AI, multi product attachment, and high free cash flow generation..."
Explore why this Narrative puts GoDaddy at roughly fairly valued.
One more GoDaddy check that sits beside the share price
Before feeling comfortable with any conclusion on GoDaddy, it helps to know who is steering the ship, how their pay is set up and whether those incentives line up with shareholders. See who runs GoDaddy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com