


TKO Group Holdings (TKO) Raises Guidance, Is The Discount To Fair Value Warranted?
TKO Group Holdings (TKO) is back in focus after its Q2 2026 update highlighted significant revenue and adjusted EBITDA growth, a higher full year outlook, and a clear preference for execution over large acquisitions.
Recent trading tells a mixed story. The share price has climbed 2.11% over the last day to US$176.02. However, the 30 day share price return is down 7.42% and the year to date share price return has declined 14.94%. At the same time, the 3 year total shareholder return of about 136% and 5 year total shareholder return above 200% point to strong longer term momentum that recent volatility has softened rather than reversed.
Spot 20 high quality undiscovered gems that, like TKO Group Holdings, aim to turn strong event franchises and media rights into long term compounding for patient investors.After the sharp pullback and the raised outlook, TKO Group Holdings now trades at a clear gap to analyst and intrinsic value estimates. Is that discount pointing to mispricing or a justified reset as expectations cool?
Most Popular Narrative: 25% Undervalued
On the most followed view of TKO Group Holdings, a fair value of about $234 sits well above the last close at $176.02. This puts investor attention squarely on how dependable that long term cash generation story looks at an 8.96% discount rate.
Formal integration of IMG, On Location and PBR into a unified TKO platform, paired with the build-out of a dedicated site fee and partnerships team, is unlocking cost synergies and cross-property monetization such as premium hospitality and experiential packages. This should support continued free cash flow growth and margin expansion.
See why 7 investors see TKO Group Holdings as 25% undervalued.
Result: Fair Value of $234.39 (UNDERVALUED)
Still, the TKO Group Holdings story can be knocked off course if streaming partners push back on media fee escalators, or if fighter and talent costs rise faster than revenues.
Find out about the key risks to this TKO Group Holdings narrative.
Another View: TKO Group Holdings Looks Expensive On Earnings
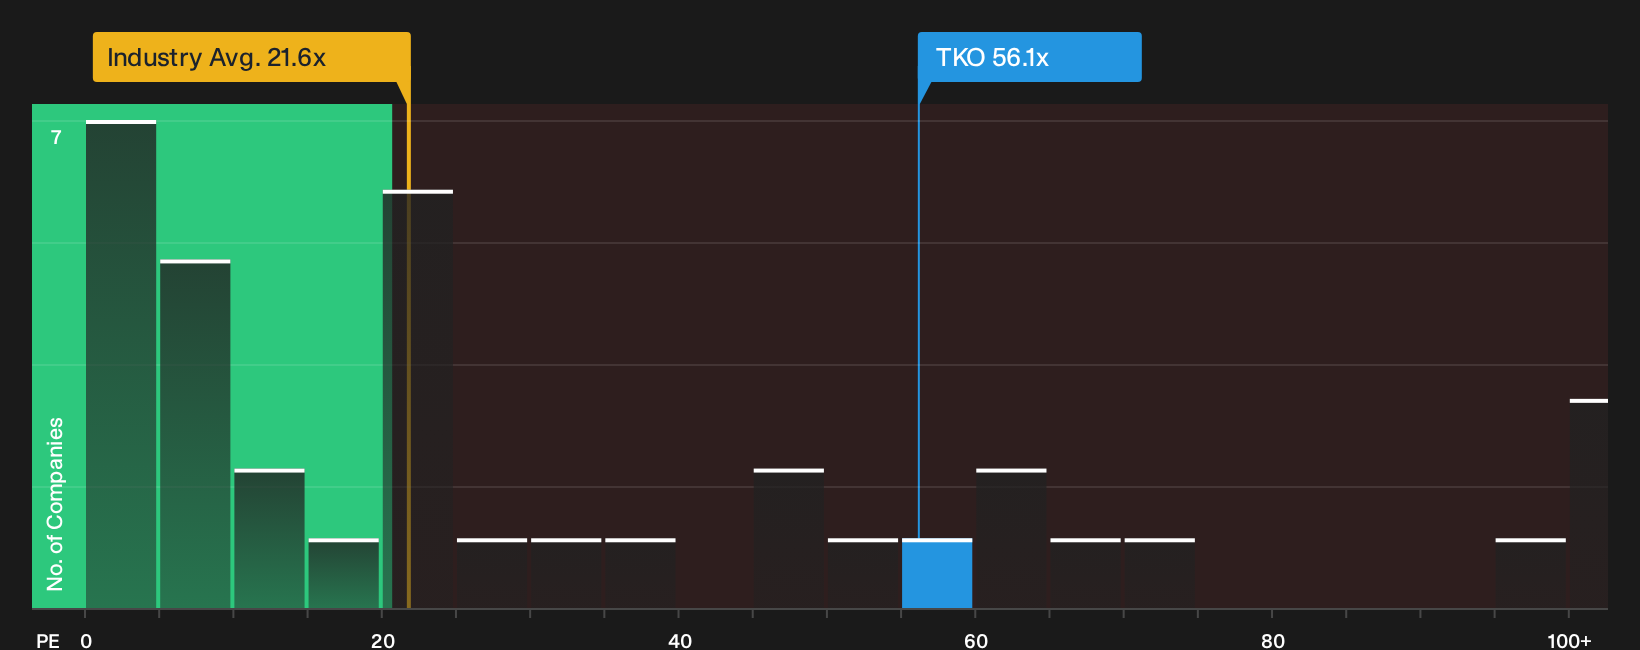
That 25% undervalued narrative leans heavily on future cash flows and long range analyst targets. On today’s numbers, TKO Group Holdings trades on a P/E of 56.1x, far above the US Entertainment industry at 21.6x, a peer average of 50.5x, and an estimated fair ratio of 32.5x.
Such a wide gap points to meaningful valuation risk if expectations cool or earnings forecasts are revised, since the share price already embeds a rich multiple. The question for you is simple: does the current premium feel like a margin of safety, or a lot of optimism priced in?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation often create real opportunity. Act while sentiment is split, and weigh both sides of the story using the 3 key rewards and 2 important warning signs.
Looking for more TKO Group Holdings style ideas?
If you stop with TKO Group Holdings, you could miss companies that better match your risk tolerance, income goals, or appetite for misunderstood opportunities ready for fresh attention.
- Target resilient balance sheets by checking the list of solid balance sheet and fundamentals (25 results) that combine financial strength with fundamentals many investors overlook.
- Hunt for mispriced opportunities through the 32 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Build a steadier income stream by reviewing the 8 dividend fortresses that focuses on generous yields backed by robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com