


3 Asian Growth Companies With Insider Ownership Up To 38%
As Asian markets navigate a landscape marked by geopolitical tensions and fluctuating energy prices, investors are increasingly focused on identifying opportunities within growth sectors. In this context, companies with high insider ownership can offer unique insights into potential growth trajectories, as insiders often possess a deep understanding of the company's strategic direction and market position.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| Meitu (SEHK:1357) | 23.1% | 26.7% |
| Meiko Electronics (TSE:6787) | 19.2% | 34% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| HUMAN MADE (TSE:456A) | 29.1% | 28.7% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Underneath we present a selection of stocks filtered out by our screen.
Shijiazhuang Shangtai Technology (SZSE:001301)
Simply Wall St Growth Rating: ★★★★★★
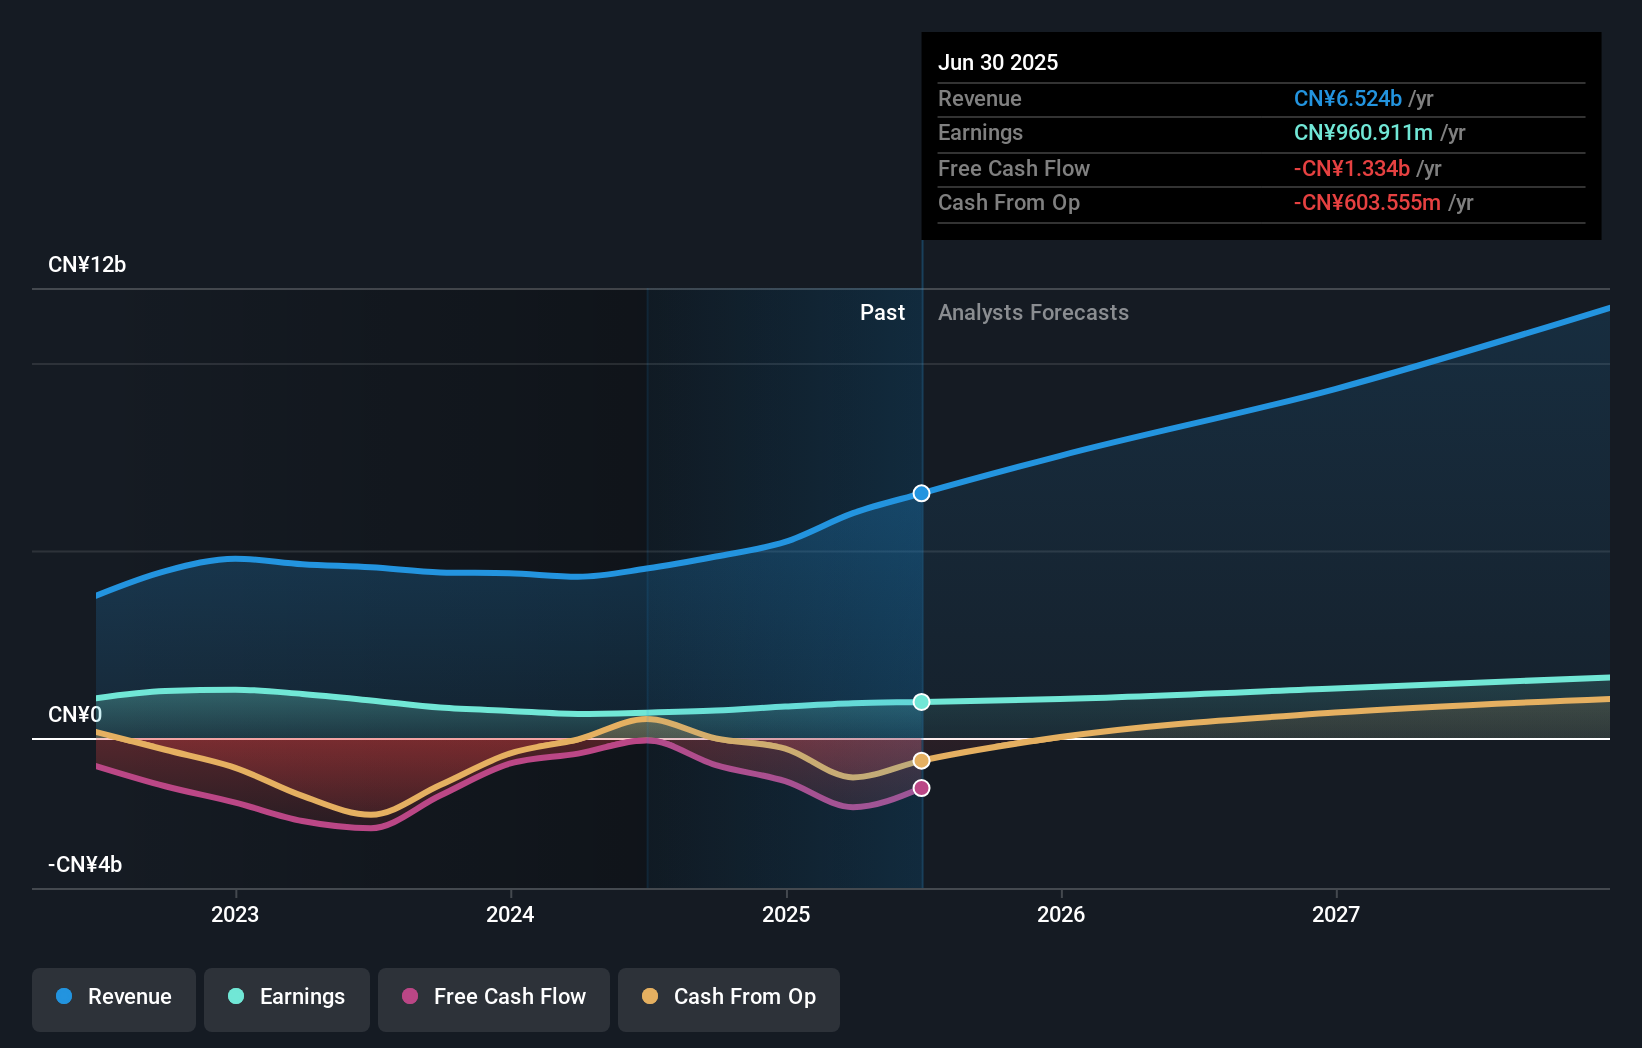
Overview: Shijiazhuang Shangtai Technology Co., Ltd. operates in the technology sector and has a market capitalization of approximately CN¥18.13 billion.
Operations: The company's revenue is primarily derived from its Negative Electrode Material segment at CN¥8.32 billion, followed by Graphitized Coke at CN¥378.45 million and Diamond Carbon Source at CN¥38.36 million.
Insider Ownership: 38.3%
Shijiazhuang Shangtai Technology is positioned for significant growth, with earnings expected to rise 43.2% annually, outpacing the Chinese market's 26.7%. Revenue growth is also strong at 31.5% per year, surpassing market averages. Despite a lower net profit margin compared to last year and a dividend not fully covered by free cash flow, the company trades at a favorable price-to-earnings ratio of 20.9x against the broader market's 39.1x, indicating good relative value amidst recent corporate governance changes.
- Click here and access our complete growth analysis report to understand the dynamics of Shijiazhuang Shangtai Technology.
- The valuation report we've compiled suggests that Shijiazhuang Shangtai Technology's current price could be quite moderate.
Hangzhou Onechance Tech Crop (SZSE:300792)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Hangzhou Onechance Tech Crop provides brand online marketing and management services and has a market cap of CN¥6.21 billion.
Operations: The company generates revenue primarily from its advertising segment, which amounts to CN¥970.46 million.
Insider Ownership: 19.6%
Hangzhou Onechance Tech Crop. is poised for substantial growth, with earnings expected to rise by 27% annually, outpacing the Chinese market's 26.7%. Despite a recent decline in revenue and net income, the company trades slightly below its estimated fair value. Recent amendments to its articles of association and registered capital may signal strategic shifts. However, its low forecasted return on equity and unstable dividend track record present potential challenges for investors.
- Unlock comprehensive insights into our analysis of Hangzhou Onechance Tech Crop stock in this growth report.
- Insights from our recent valuation report point to the potential overvaluation of Hangzhou Onechance Tech Crop shares in the market.

Digital Garage (TSE:4819)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Digital Garage, Inc. is a context company in Japan with a market capitalization of approximately ¥114.65 billion.
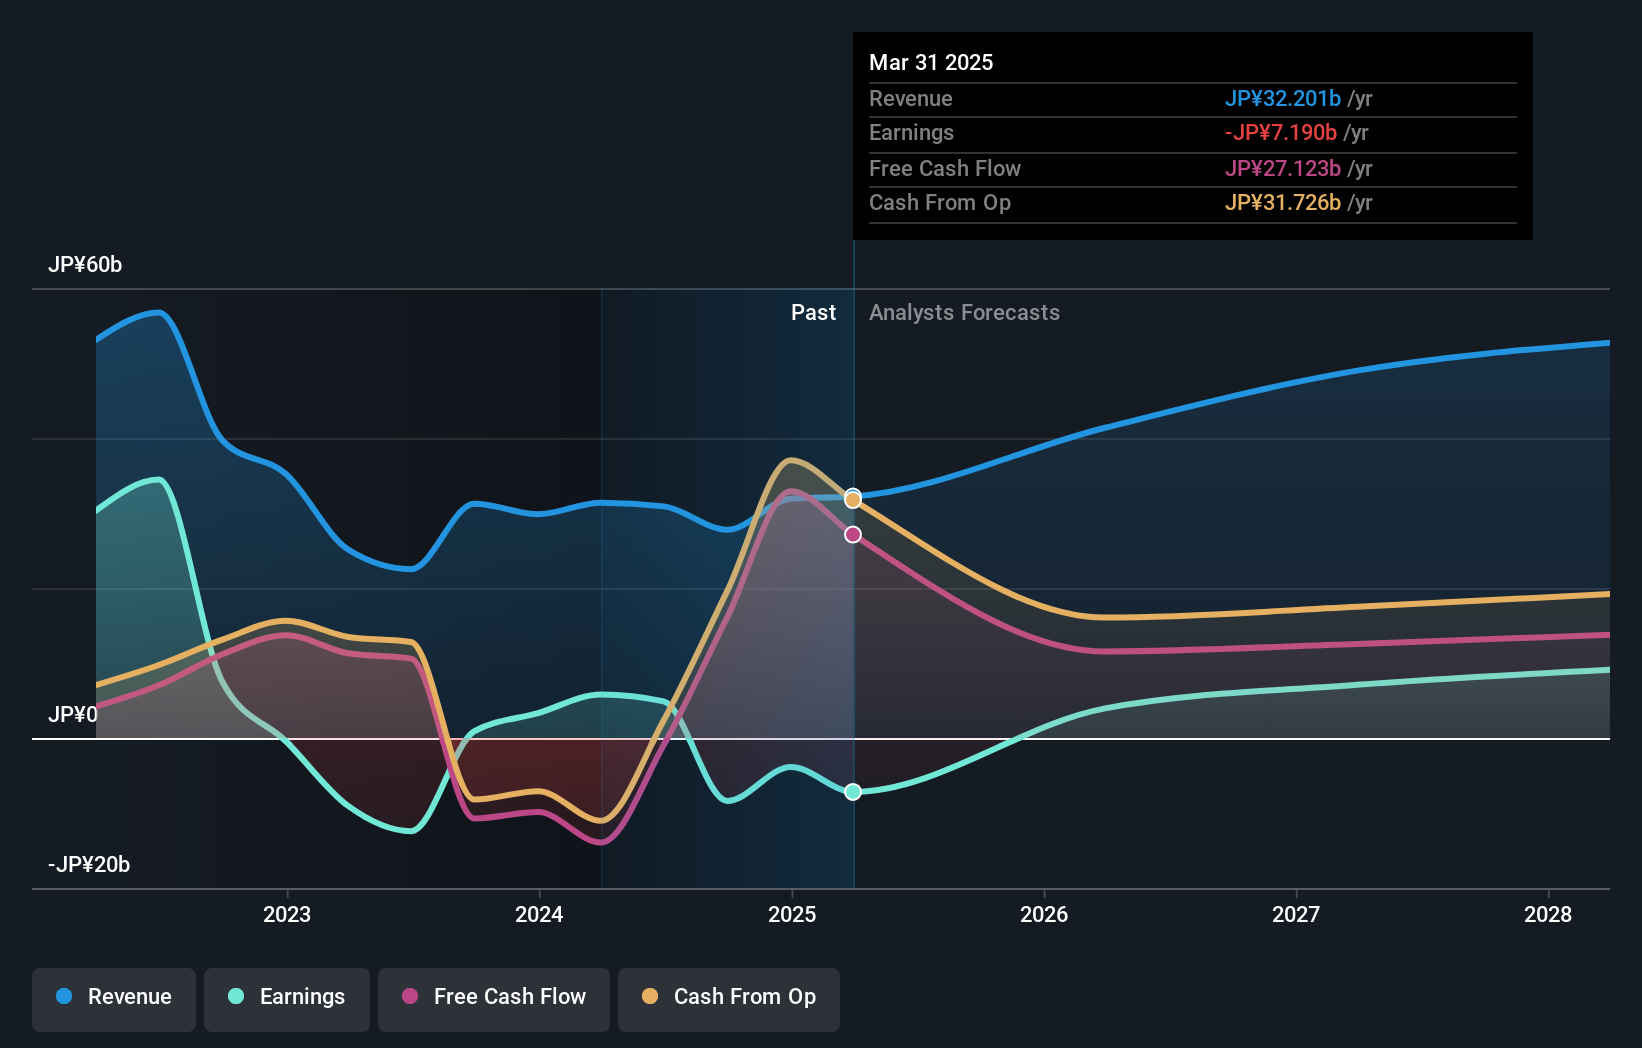
Operations: Digital Garage, Inc. generates revenue through its primary segments: ¥56.23 billion from the FinTech segment, ¥44.67 billion from the Marketing Technology segment, and ¥13.45 billion from the Incubation Technology segment.
Insider Ownership: 18%
Digital Garage's earnings are forecast to grow significantly at 26.59% annually, surpassing the Japanese market's growth rate. Despite becoming profitable this year, its revenue growth is slower than desired and impacted by large one-off items. Trading below estimated fair value suggests potential undervaluation, but a low return on equity and unsustainable dividend coverage pose risks. Recent leadership changes may influence strategic direction, while first-quarter results show slight improvements in sales and reduced net loss.
- Delve into the full analysis future growth report here for a deeper understanding of Digital Garage.
- Our valuation report unveils the possibility Digital Garage's shares may be trading at a premium.
Turning Ideas Into Actions
- Delve into our full catalog of 502 Fast Growing Asian Companies With High Insider Ownership here.
- Interested In Other Possibilities? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com