


3 Taiwan AI Chip Stocks Riding TSMC’s Record Quarter
TSMC just reported its sixth straight record quarter, with net income up about 69% and revenue up 51%, which puts AI chip infrastructure firmly back in the spotlight. That kind of momentum can reshape where capital flows next, and missing the right side of that shift can feel painful. This article walks through three stocks tied to this AI semiconductor build out and how the same news can reshape their risk and reward profile.
The three stocks covered below are just a sample pulled from a wider universe, and the full screen surfaced 28 more AI semiconductor infrastructure leaders with equally compelling stories that are not unpacked in this article. If you want to identify potential front runners and analyze where the stronger quality and size filters point, go straight to the AI Semiconductor Infrastructure Leaders screener
MPI (TPEX:6223)
Overview: MPI Corporation supplies semiconductor manufacturing and testing equipment used by foundries and chipmakers that support advanced AI hardware builds.
Operations: MPI generates about NT$16.4b in revenue from semiconductor equipment and services, tying its top line directly to chip industry capex.
Market Cap: NT$519.3b
MPI provides exposure to the AI semiconductor infrastructure build out through probe cards, test systems and thermal tools used across major chipmaking hubs. Reported revenue and earnings figures indicate that this equipment suite is seeing demand. The potential from AI-related capex depends on how one currently unseen pressure develops.
That pressure point is exactly where a lot of investors now focus, so it is worth scanning the 3 key rewards and 2 important warning signs (2 are major!) before AI capex cycles shift again.

Sigurd Microelectronics (TWSE:6257)
Overview: Sigurd Microelectronics runs outsourced IC packaging, testing, and burn in services that help qualify advanced AI chips for high volume production.
Operations: Sigurd Microelectronics generates about NT$21.2b from packaging and testing and about NT$56 million from trading related activities.
Market Cap: NT$123.4b
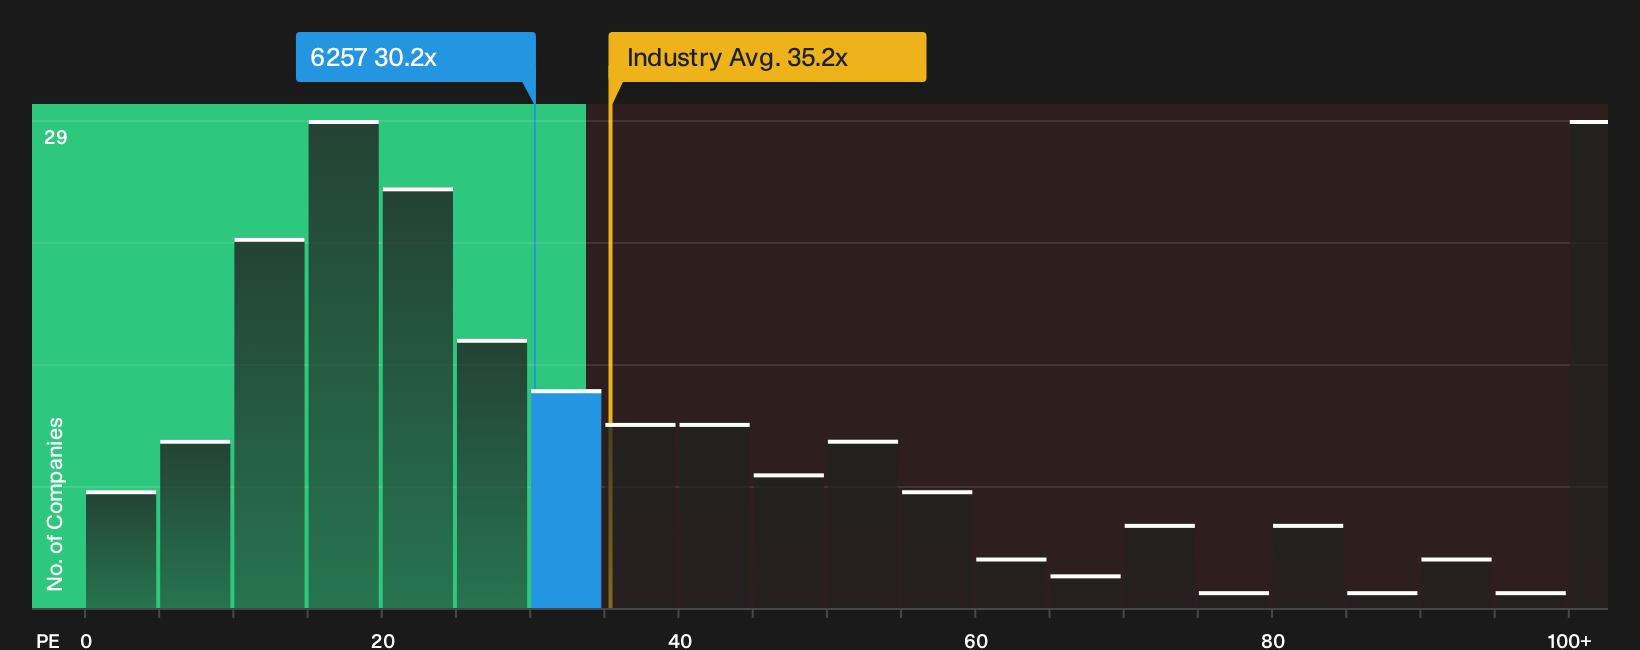
Sigurd Microelectronics provides exposure to the AI chip qualification chain, with packaging, test, and burn in services that become important when foundries such as TSMC undertake multi year AI capital expenditures. The company’s earnings profile, its P/E relative to some peers, and its role in AI hardware activity may be of interest to some investors, depending on how an identified pressure related to funding and cash flow quality develops.
That funding and cash flow tension is exactly what the 4 key rewards and 3 important warning signs (1 is major!) could be flagging before Sigurd Microelectronics’ role in AI increases further
AP Memory Technology (TWSE:6531)
Overview: AP Memory Technology designs and sells customized memory ICs used in AI accelerators and data center hardware, directly linking it to AI semiconductor infrastructure demand.
Operations: AP Memory Technology generates about NT$7.8b in revenue from semiconductor related products, tying its top line to memory IC demand.
Market Cap: NT$135.6b
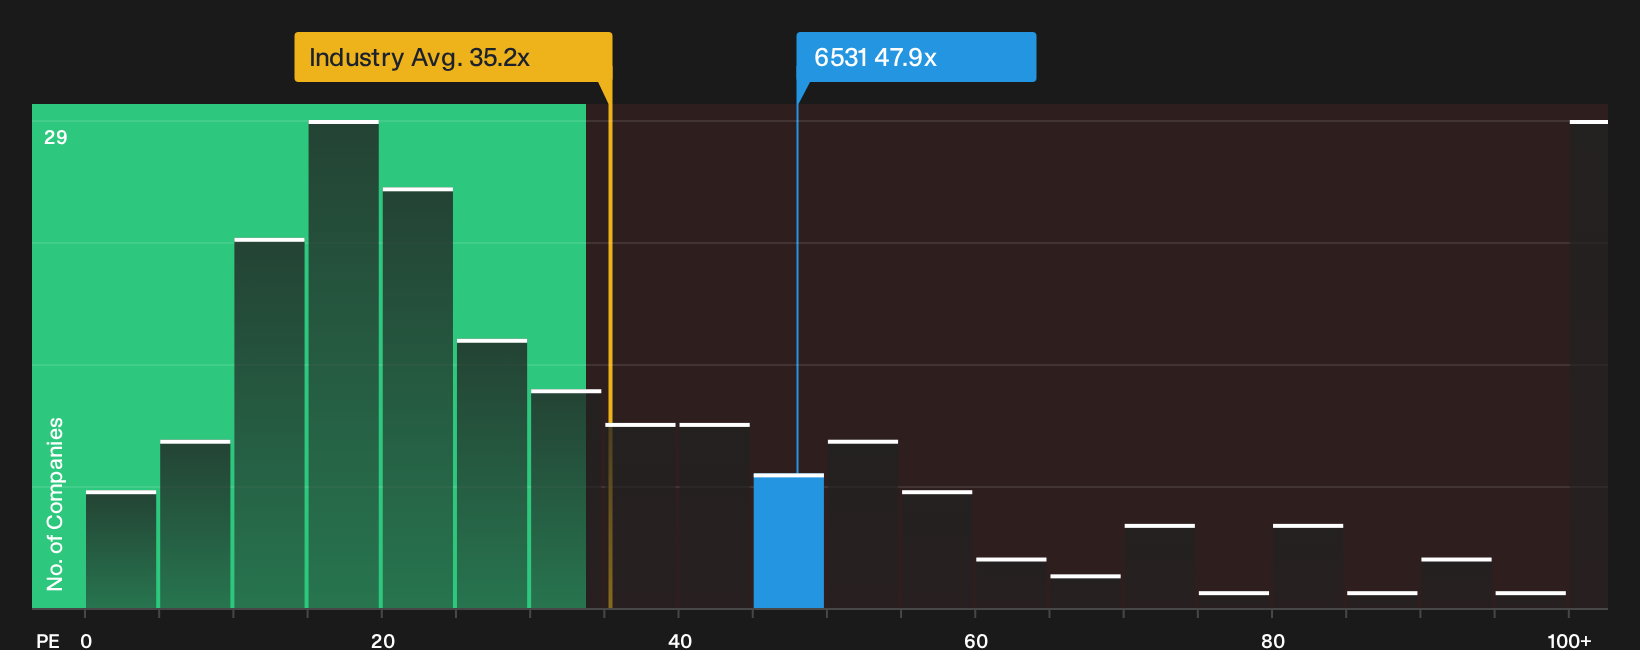
AP Memory Technology plugs into the AI Semiconductor Infrastructure Leaders theme through specialized memory ICs that support accelerators and data centers. Recent results show revenue of TWD 4,462.83 million and a swing from loss to profit in H1 2026, with a P/E of 47.9x that investors may assess in the context of their own expectations for resilience and pricing power.
That kind of valuation tension makes the 3 key rewards and 1 important major warning sign a sharp way to see what the headline P/E might be masking.
Seeking Fresh Alternatives Before They Fly
Some potential breakouts stay under the radar for now, then can shift quickly once momentum builds. Consider these fresh stock shortlists before any potential edge fades.
- Target reliable income streams by scanning 219 dividend fortresses that may help keep cash flowing even when sentiment swings.
- Look for quality at a discount with the curated 197 high quality undervalued stocks that focus on solid businesses investors may not have fully priced in yet.
- Track potential infrastructure demand through the hand picked 42 power grid technology and infrastructure stocks while the theme is still developing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com