


ASML Holding (ASML) Looks Pricey Following Chip Spending Caution
ASML Holding (NasdaqGS:ASML) is back in focus after sector peer Applied Materials declined to share an industry spending outlook, which pulled chip equipment stocks lower ahead of ASML's upcoming earnings report.
The recent pullback, with the share price down 3.94% over the last day and 8.59% over the past week to US$1,650, comes after a solid run that includes a 41.78% year to date share price return and a 64.31% 1 year total shareholder return. This suggests short term sentiment has cooled even as longer term performance remains strong.
Scan how this ASML Holding move compares with other chipmaking suppliers by reviewing our hand picked list of 93 AI infrastructure stocks before the next leg of AI hardware spending takes shape.
ASML Holding now trades well below average analyst targets, even as the latest wobble reflects fresh doubt around chip spending. Is this a fair discount to the firm’s prospects, or an overreaction to short term caution?
Preferred Multiple of P/E 55.2x: Is it justified?
Valuation has flipped quickly for ASML Holding. After a long run in the share price, the stock now trades on a P/E of 55.2x, which is well above both its own fair ratio estimate and key sector comparisons.
The P/E multiple compares what investors are paying for each dollar of ASML Holding earnings. For chip equipment suppliers, this is often used as a shorthand for how much faith the market has in future profit expansion and returns on capital.
At 55.2x earnings, the market is assigning a sizeable premium to ASML Holding compared with the estimated fair P/E of 40.6x. The current ratio also exceeds the US Semiconductor industry average of 46.8x and the peer group on 46.2x. That gap suggests the share price already bakes in a stronger earnings profile than both the sector and the level the fair ratio model indicates the market could move towards.
Explore the SWS fair ratio for ASML Holding.
Result: Price-to-earnings of 55.2x (OVERVALUED)
Still, the ASML Holding story can be knocked off course if chipmakers rein in equipment budgets, or if export controls tighten further in key regions.
Find out about the key risks to this ASML Holding narrative.
Another View: ASML Holding Through the Lens of Cash Flows
There is a very different message coming from the SWS DCF model. On that framework, ASML Holding at $1,650 sits above an estimated future cash flow value of $936.51, which points to an overvalued result rather than a premium that might be justified by earnings alone.
This kind of gap can matter. A rich P/E and a DCF that also signals limited value support both lean in the same direction. The key question is whether future cash generation eventually catches up to today’s price or whether expectations reset closer to the DCF line.
Look into how the SWS DCF model arrives at its fair value.
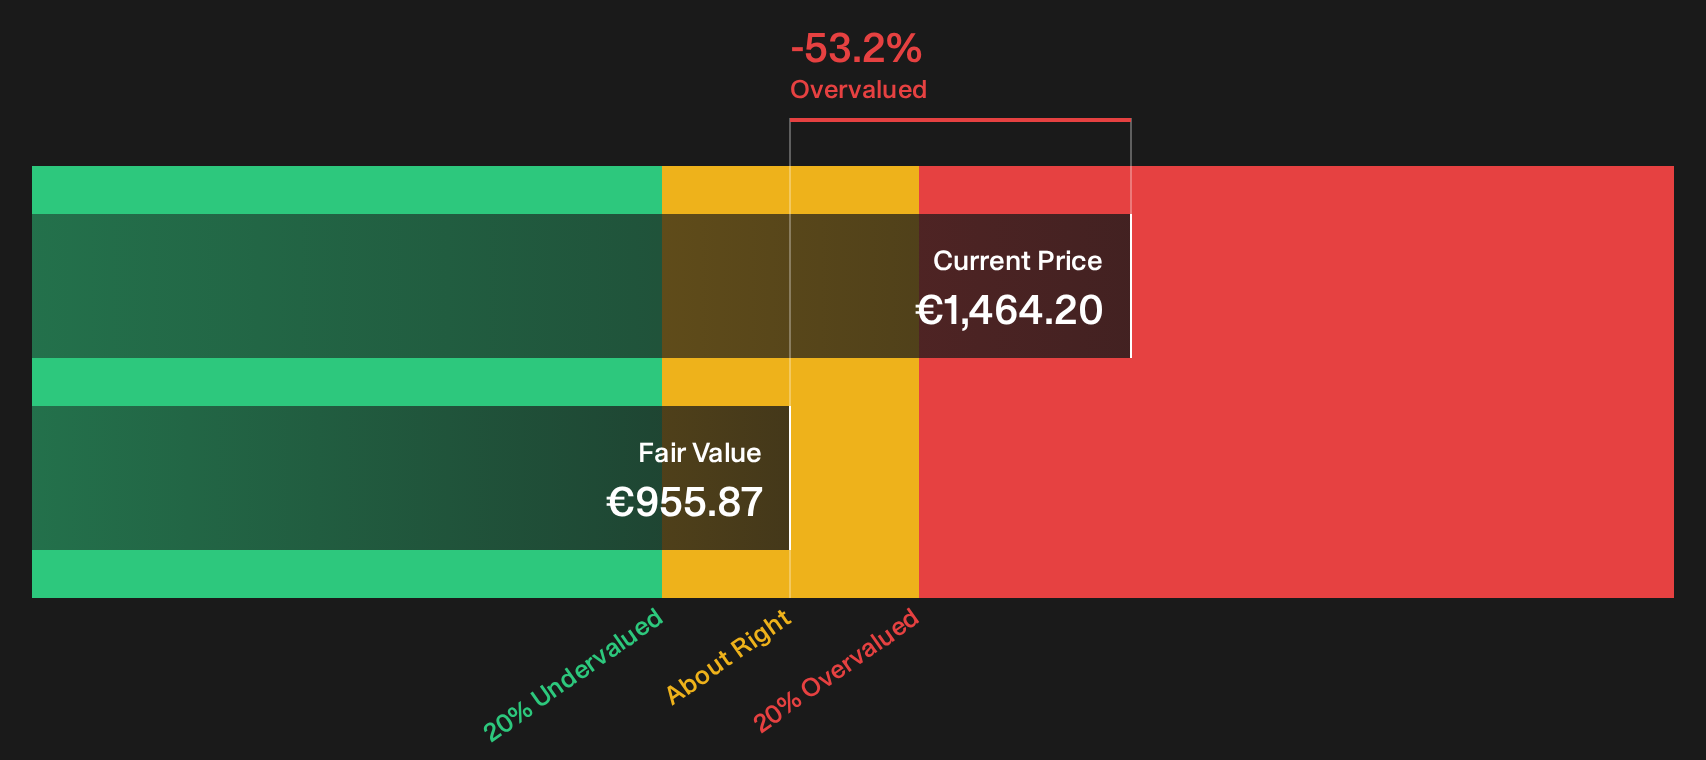
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ASML Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment in this ASML Holding review has been cautious, yet the data still points to specific upsides that investors are watching closely. If you want to move beyond headlines and price screens, take a few minutes to test the assumptions against your own expectations and time horizon, then weigh those against the 2 key rewards.
Looking for more ASML Holding sized ideas?
If ASML Holding has sharpened your focus, use that momentum and scan a few proven stock lists that can broaden your opportunity set fast.
- Target potential mispricings by reviewing our curated set of 32 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- Strengthen your income stream by assessing companies in the 7 dividend fortresses that combine higher yields with disciplined payout profiles.
- Dial down risk while staying invested by working through the 32 resilient stocks with low risk scores filtered for sturdier balance sheets and steadier business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com