


Zscaler (ZS) Reaffirms Guidance As A Rich Valuation Narrative Comes Back Into View
Why Zscaler Stock Is Back in Focus
Zscaler (ZS) has returned to investors’ radar after management reaffirmed its fiscal 2027 revenue guidance and outlook for the upcoming quarter, while analyst earnings projections have recently become more optimistic.
The reaffirmed outlook has landed after a sharp swing in sentiment, with Zscaler’s share price delivering a 15.2% gain over the past month and a 50.8% share price return over 90 days, even as the 1-year total shareholder return is down 27.0%.
Leverage the renewed momentum in Zscaler and see how it compares to hand picked cybersecurity peers with the 32 resilient stocks with low risk scores.After a 50% rebound in three months and guidance now reiterated, Zscaler no longer looks forgotten or cheap based on sentiment alone. Investors may now ask whether the current valuation still leaves enough upside to justify the cybersecurity risk profile.
Most Popular Narrative: 5% Undervalued
The most followed narrative on Zscaler sees fair value at $233.38, slightly above the last close of $220.79. This puts the recent rebound into clearer context for anyone weighing upside against risk.
Accelerating customer adoption of Zero Trust Everywhere and Data Security Everywhere solutions, particularly among larger enterprises, is now supported by Zero Trust Branch and Zero Trust Cloud reaching about US$250 million of ARR and maintaining ARR growth above 60% for eight consecutive quarters. This can continue to lift ARR per customer and support revenue growth.
See why 188 investors see Zscaler as 5% undervalued
Result: Fair Value of $233.38 (UNDERVALUED)
Still, the Zscaler story depends on reaccelerating ARR after guided 2027 growth slows, and on AI security pilots turning into larger rollouts rather than stalling.
Find out about the key risks to this Zscaler narrative.
Another View: What Zscaler’s Sales Multiple Is Telling You
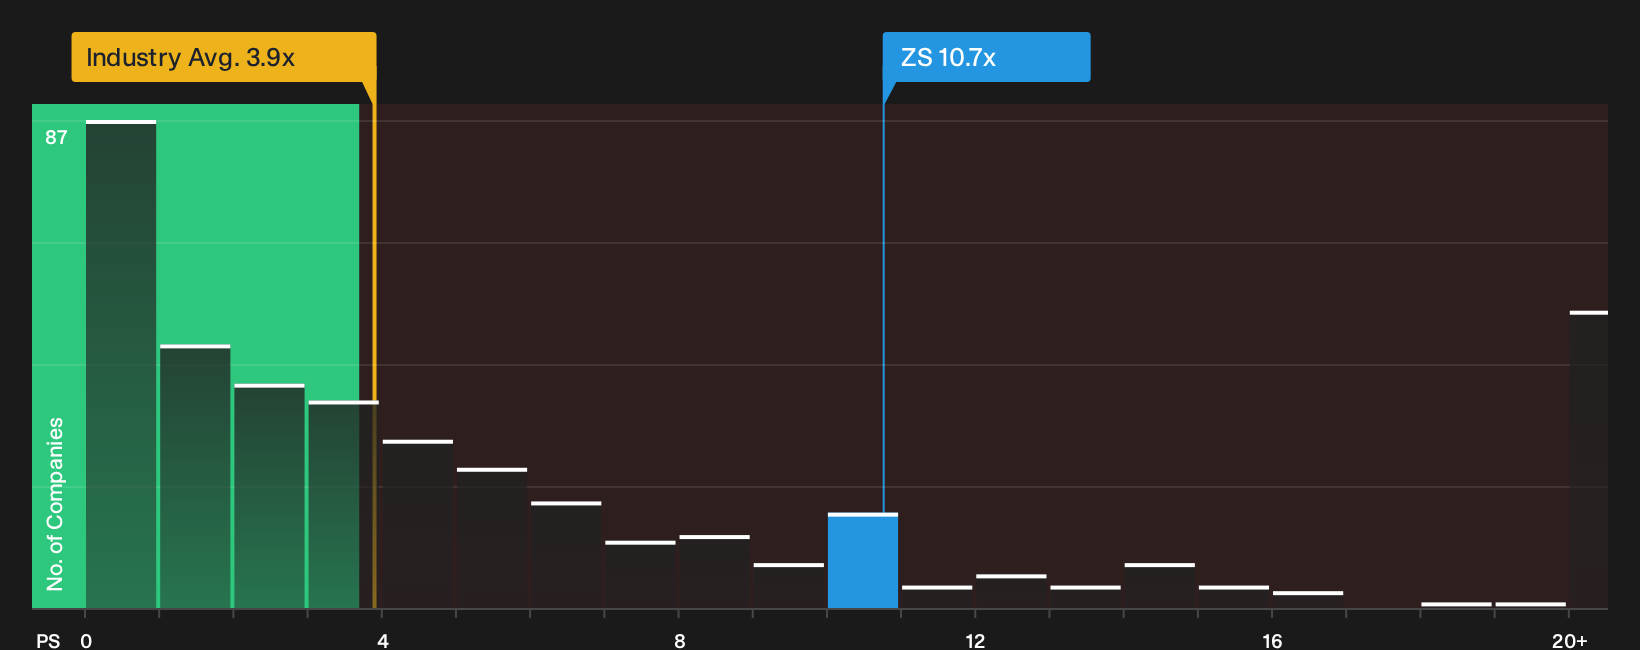
There is a different read on Zscaler when looking at its P/S ratio of 10.7x. That level is above the US Software industry at 3.9x and above the 9.5x fair ratio that the regression points to, so anyone buying today is paying a premium that could shrink if sentiment cools.
Before leaning on that premium as a sign of strength or a risk to avoid, it is worth seeing what the numbers say at a more granular level in our valuation breakdown, including the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the recent Zscaler narrative, with both concerns and bright spots in play, make this a moment to move fast, review the underlying data, and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Zscaler?
If Zscaler has sharpened your focus on where capital works hardest, do not stop here. Broader ideas can help you build a more resilient portfolio.
- Target potential mispricing by scanning a 32 high quality undervalued stocks that filters for companies with strong fundamentals trading below their estimated worth.
- Strengthen your income stream by reviewing a 7 dividend fortresses built around higher-yield payouts with an eye on consistency and resilience.
- Protect your downside by checking a list of solid balance sheet and fundamentals (25 results) that homes in on businesses with healthier leverage and liquidity profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com