


DexCom (DXCM) Just Drew Fresh Attention, So What Is The Market Weighing?
DexCom (DXCM) just received a rare spotlight in The New England Journal of Medicine, as its CONNECT randomized trial on the G7 continuous glucose monitor for Type 2 diabetes patients not using insulin reached publication.
For context, DexCom shares trade at US$83.47. While the 1-day share price return declined 1.87% and the 7-day share price return is down 0.98%, the 90-day share price return of 7.04% and year-to-date share price return of 25.44% point to building momentum around catalysts like the CONNECT data. At the same time, the 5-year total shareholder return of 40.01% and slightly negative 3-year total shareholder return of 0.77% remind investors that sentiment has shifted over time with changing expectations for growth and risk.
Capitalize on the interest around DexCom and this NEJM-backed CGM story by scanning a curated set of health-focused opportunities in our 34 healthcare AI stocks.DexCom now has gold standard clinical backing and a US$32.1b market value built on that glucose monitoring story. The real tension for investors sits elsewhere: Does the current US$83.47 share price still make sense?
Most Popular Narrative: 16% Undervalued
According to the most followed narrative on DexCom, the fair value sits at $99.69 compared with the recent $83.47 close. This frames the NEJM validation against a valuation gap that some investors are watching closely.
DXCM's average and forward revenue growth is approximately 15 p.a.
Historical and forward net profit margins will likely mirror sector and industry margins landing slightly above at 14.5%
See why 2 investors see DexCom as 16% undervalued.
Result: Fair Value of $99.69 (UNDERVALUED)
Still, the story can break if DexCom stumbles on execution in new products like Stelo, or if pricing pressure squeezes those guided margin targets.
Find out about the key risks to this DexCom narrative.
Another View: DexCom Through The P/E Lens
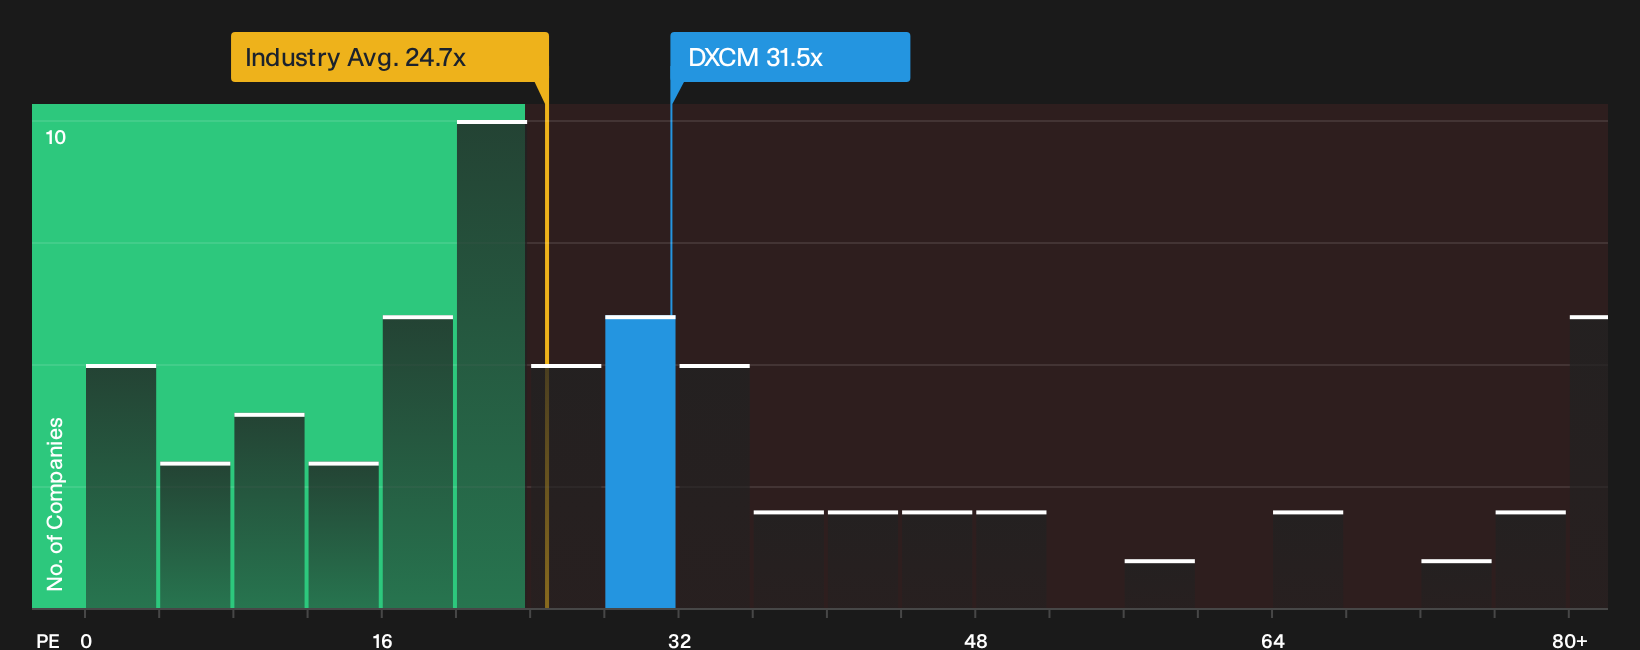
The first narrative pegs DexCom at $99.69 using growth and margin assumptions, yet the current P/E near 31.5x tells a different story. That valuation is higher than the Medical Equipment peer average around 25x and above a fair ratio of 31.1x, which nudges risk higher if expectations cool. Is the premium a source of comfort or a pressure point for you as a shareholder?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling pulled between DexCom's clinical headlines and its current valuation setup is normal, especially when different metrics point in different directions. Act while interest is high by testing the assumptions against your own risk tolerance, then explore the potential upside case by reviewing the 3 key rewards.
Looking for more investment ideas beyond DexCom?
Do not stop your research with DexCom. The same curiosity that brought you here can help you build a stronger watchlist of high conviction opportunities.
- Target powerful upside potential by scanning a curated set of 20 high quality undiscovered gems before they attract wider attention.
- Prioritise resilience in choppy markets and filter for 32 resilient stocks with low risk scores that aim to keep portfolio swings in check.
- Anchor your portfolio with quality by focusing on companies from our list of solid balance sheet and fundamentals (25 results) that combine financial strength with durable fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com