


How Investors Are Reacting To Tractor Supply (TSCO) Hotter Inflation Data
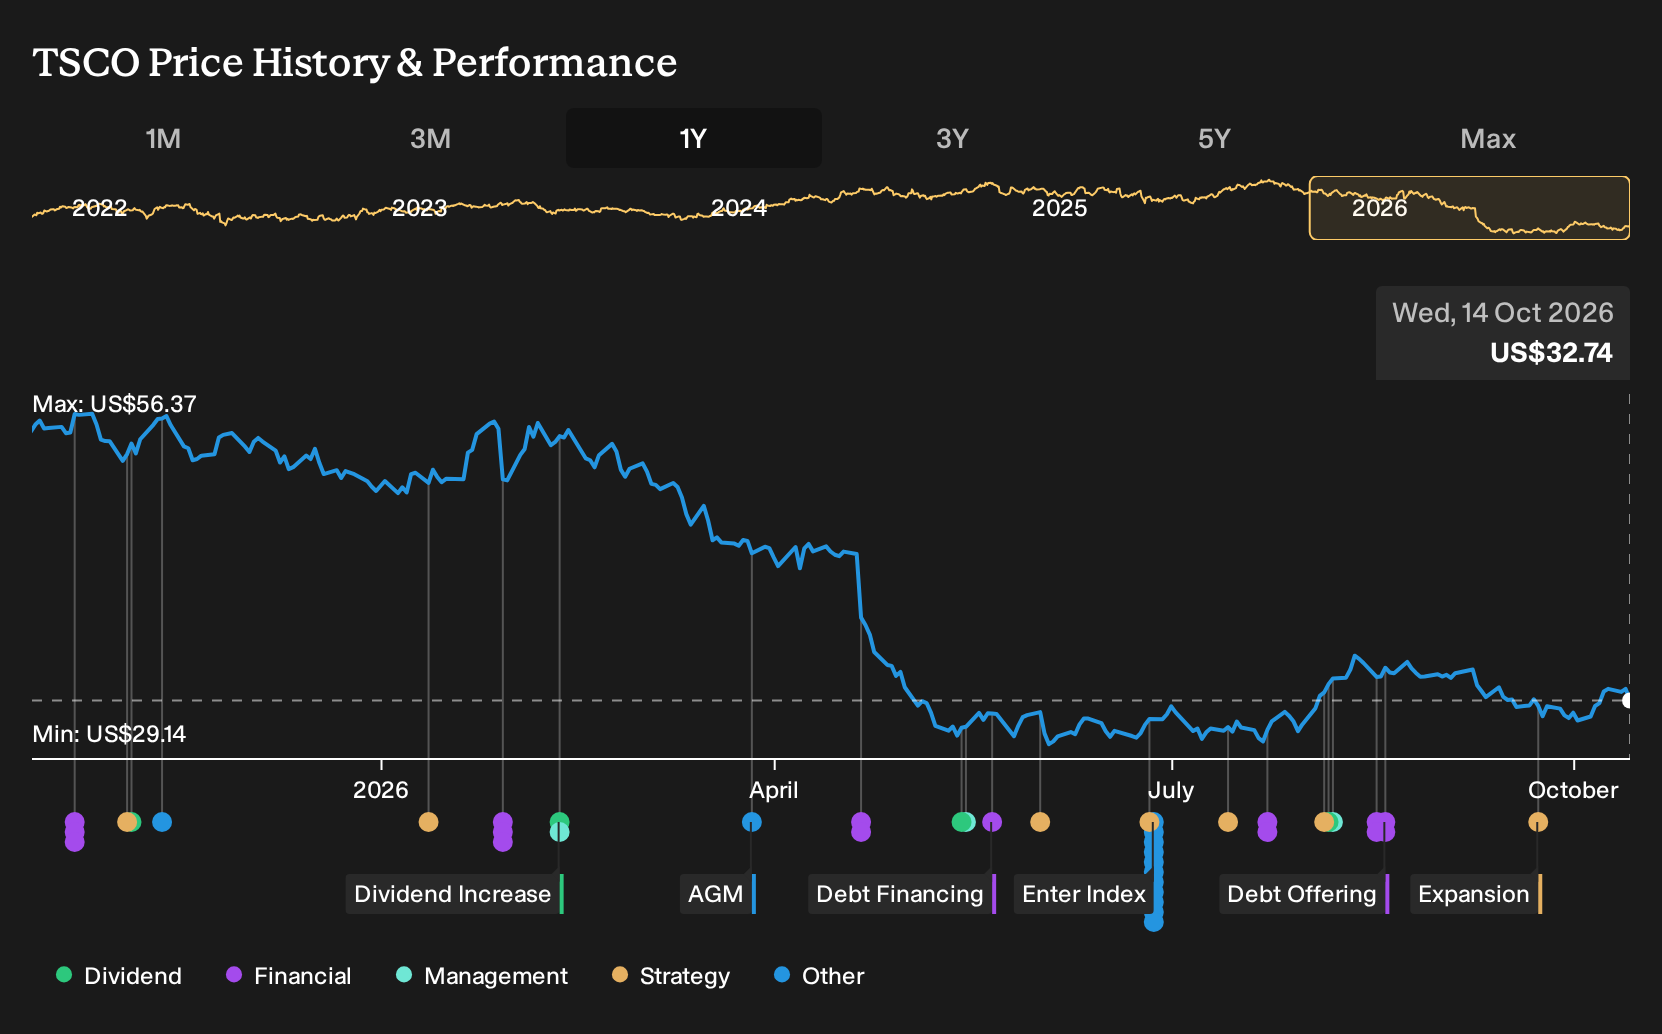
- Tractor Supply recently faced pressure after hotter than expected September inflation data pushed Treasury yields higher and weighed on consumer focused retailers.
- The inflation surprise matters for Tractor Supply because higher benchmark yields can reduce valuation support at the same time the retailer is experiencing softer comparable sales and investment driven free cash flow pressure.
- This article examines how Tractor Supply's investment narrative intersects with the higher Treasury yields that followed the hotter September inflation report.
Compare Tractor Supply's setup under higher Treasury yields with a curated list of retailers that screen as potential value opportunities in the current rate backdrop through 32 high quality undervalued stocks
Tractor Supply Investment Narrative Recap
To own Tractor Supply, you need to believe its rural lifestyle model can work through softer comparable sales and weaker big ticket demand while pet, consumables and services keep shoppers coming back. The hotter September inflation print and higher Treasury yields mainly hit the share price rather than the core operations.
The near term swing factor is whether traffic and ticket trends stabilize as management tightens pricing on key consumables and leans on its pet ecosystem and Final Mile delivery to support volumes. The biggest risk is that pressure on discretionary farm, pet and home improvement spending drags on for longer, keeping comps and margins under strain.
The recent pullback landed just as investors were already focused on Tractor Supply rebalancing its capital spend. Management plans to slow 2027 store openings and close roughly 75 underperforming Petsense locations while putting more money into remodels, relocations and projects with higher expected returns.
This shift matters for a higher yield backdrop because it concentrates cash into efficiency and earnings quality rather than footprint expansion. If store productivity, the new Nampa distribution center and growing pet subscriptions work together as intended, they could help offset some macro and rate related pressure. Execution around these projects now sits under a brighter spotlight.
How Tractor Supply's Forecasts Meet Higher Yields
Tractor Supply's narrative projects revenues of US$18.0b and earnings of US$1.2b by 2029. This path assumes revenue grows at 4.6% per year and earnings rise by about US$200m from US$1.0b today.
Uncover how Tractor Supply's fair value indicates an 8% potential upside to its current price before the gap to fundamentals starts to narrow.
Exploring Other Perspectives
Higher interest costs are the flashpoint where views really split. The most optimistic Tractor Supply analysts were modeling about US$18.5b in revenue and US$1.3b in earnings by 2029 before this inflation surprise, which is a step up from the US$18.0b and US$1.2b baseline. That more upbeat scenario could shift if higher yields stick.
Explore 3 other Tractor Supply fair value estimates, including one that suggests as much as 24% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tractor Supply research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tractor Supply. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Tractor Supply's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tractor Supply?
Once you have a view on Tractor Supply, it can help to compare that thesis with other businesses that match your risk tolerance, income needs and time horizon. The Simply Wall St Screener lets you quickly move from a single stock story to a wider watchlist tailored to the type of opportunities you want to research next.
- If capital preservation sits high on your list, focus on resilient businesses by scanning a 32 resilient stocks with low risk scores that may suit a more cautious approach.
- For investors who care most about financial strength and staying power, review a list of solid balance sheet and fundamentals (25 results) that can help anchor the more speculative parts of a portfolio.
- If you are hunting for overlooked opportunities with robust fundamentals, take a look at a 20 high quality undiscovered gems that could add fresh ideas to your research list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com