


What UniCredit Buyers Were Betting On
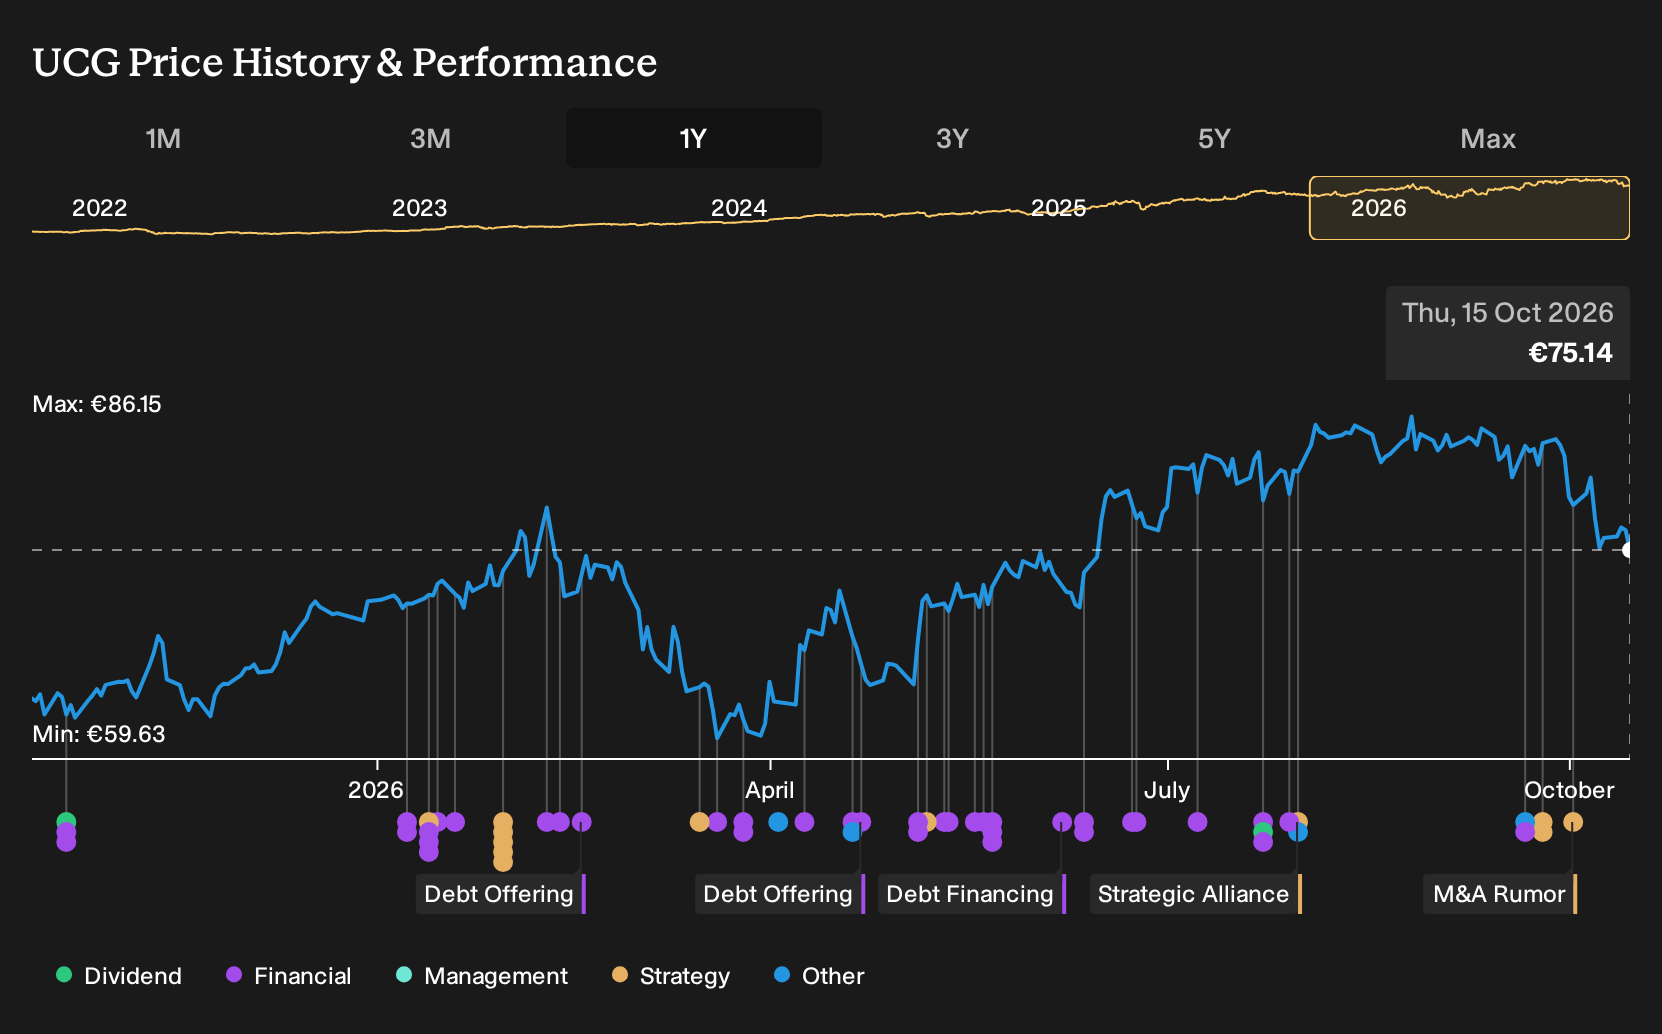
If UniCredit was on your watchlist rather than in your portfolio, the result may feel like a missed call. For UniCredit shareholders, the return over the past year was 24.5%, including dividends. That number raises a blunt question. Back on 15 October 2025, with bullish analysts leaning on digital banking, sustainable finance and cross border expansion, what should have told you that UniCredit’s push into large scale deals like Commerzbank might justify owning it rather than just watching?
If the move has made UniCredit harder to judge, start where the gap is still open and scan 198 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On UniCredit
The shares cost €62.69 at the start of the period, and the debate around UniCredit split cleanly into two stories about where the bank could head next.
On the bullish side, one narrative saw digital banking, wealth management and sustainable finance reshaping UniCredit, with a Fair Value of €66.32. This was essentially the price implied if those plans worked. That view leaned on expansion in fee based life insurance and advisory to build more recurring, higher margin income.
The bearish camp anchored on a Fair Value of €57 that reflected a tougher outcome. In that story, intensifying fintech competition and heavier regulation steadily ate into UniCredit’s fees and net interest income, leaving margins under pressure.
What The Results And Deals Said About UniCredit
UniCredit spent the period pushing hard on Commerzbank, moving from a rejected €35b bid to securing close to half the voting rights and later approaching majority control as German resistance softened. That tilt toward large cross border deals supported the bullish story on scale and fee potential. At the same time, Q2 2026 showed revenue and net income down year on year, and net margin slipping from 47.9% to 45.7%, so the evidence cut both ways.
The key lesson is clear. When a bank leans on big M&A to justify a higher Fair Value, you need to track two things side by side: deal progress against stated conditions, and the reported margin trend, quarter by quarter, to see whether integration ambition is lining up with actual profitability.
What UniCredit’s Price Now Asks You To Believe
UniCredit trades at €75.14, with the selected Narrative arguing that its Fair Value sits above that level. That view leans on AI driven efficiency, fee heavy revenue and capital discipline combining into a durable earnings engine.
The core question for anyone paying today’s price is whether UniCredit can keep executing an AI centred, fee rich banking model while completing Commerzbank on terms that protect returns.
"Key Takeaways: Analysts expect UniCredit to keep using its AI and technology led operating model, capital efficient earnings power, and fee rich business mix to support a high return on equity and sizeable excess capital generation over time. The main thing that has to go right is UniCredit successfully executing a Commerzbank acquisition on acceptable political terms, while delivering the large cost efficiencies and capital discipline implied by its current operating model."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 32% below our estimate - turn heavy investment in digital, appliances and e&s into higher margin multichannel sales.
- Company 2 - 35% below our estimate - capture institutional capital reallocating toward energy transition infrastructure through higher fee private funds.
- Company 3 - 24% below our estimate - attract senior lawyers leaving partnerships for a tech enabled, higher personal fee share model.
Three companies from the same screener. Open every one of the 201 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com