


J&T Global Express (SEHK:1519) Could Be 33% Undervalued Following Q3 Parcel Volume Growth
J&T Global Express (SEHK:1519) put volume firmly in focus after reporting Q3 2026 operating results, with global parcels reaching 9.58 b and average daily traffic topping 100 million for a second straight quarter.
The Q3 volume update lands after a choppy stretch for J&T Global Express, with the share price at HK$8.99 and a 7 day share price return of 3.45% partially offsetting a year to date share price decline of 13.64% and a 1 year total shareholder return decline of 13.06%. This suggests that recent momentum is improving even as longer term holders remain under pressure.
Spot opportunities around J&T Global Express by scanning a curated list of solid balance sheet and fundamentals (201 results) that could be better positioned if parcel and e-commerce volumes stay in focus.Bulls point to J&T Global Express’s parcel momentum and wide e commerce footprint. Bears focus on share price losses and tight industry economics. Which side will the valuation favor next?
Most Popular Narrative: 33% Undervalued
Against a last close of HK$8.99, the most followed narrative pegs J&T Global Express at a fair value of about HK$13.48, using an 8.57% discount rate and detailed long term forecasts to bridge parcel growth with profitability.
The rapid expansion of e-commerce, especially in Southeast Asia and emerging markets like Latin America, continues to drive strong parcel volume growth for J&T (e.g., 58% volume growth in Southeast Asia and 22% in new markets in H1 2025), supporting both top-line revenue growth and reinforcing a long-term structural demand tailwind.
Find out how 3 investors see J&T Global Express as 33% undervalued.
Based on that framework, the narrative implies J&T Global Express trades at a 33.3% discount to its HK$13.48 fair value estimate. The gap is described as being driven by parcel scale assumptions, margin expansion to a 5.25% profit margin, and a future P/E of about 16x that is above the Hong Kong logistics sector multiple but below the model’s previous setting. The same storyline applies a discount rate of 8.57% to those projected cash flows, which keeps the focus on whether earnings can track the forecast path rather than on short term share price moves.
Result: Fair Value of HK$13.48 (UNDERVALUED)
Still, intense parcel price competition in China and the capital heavy push into new regions could pressure J&T Global Express if volume or margin assumptions misfire.
Find out about the key risks to this J&T Global Express narrative.
Another View: J&T Global Express Looks Expensive On Earnings
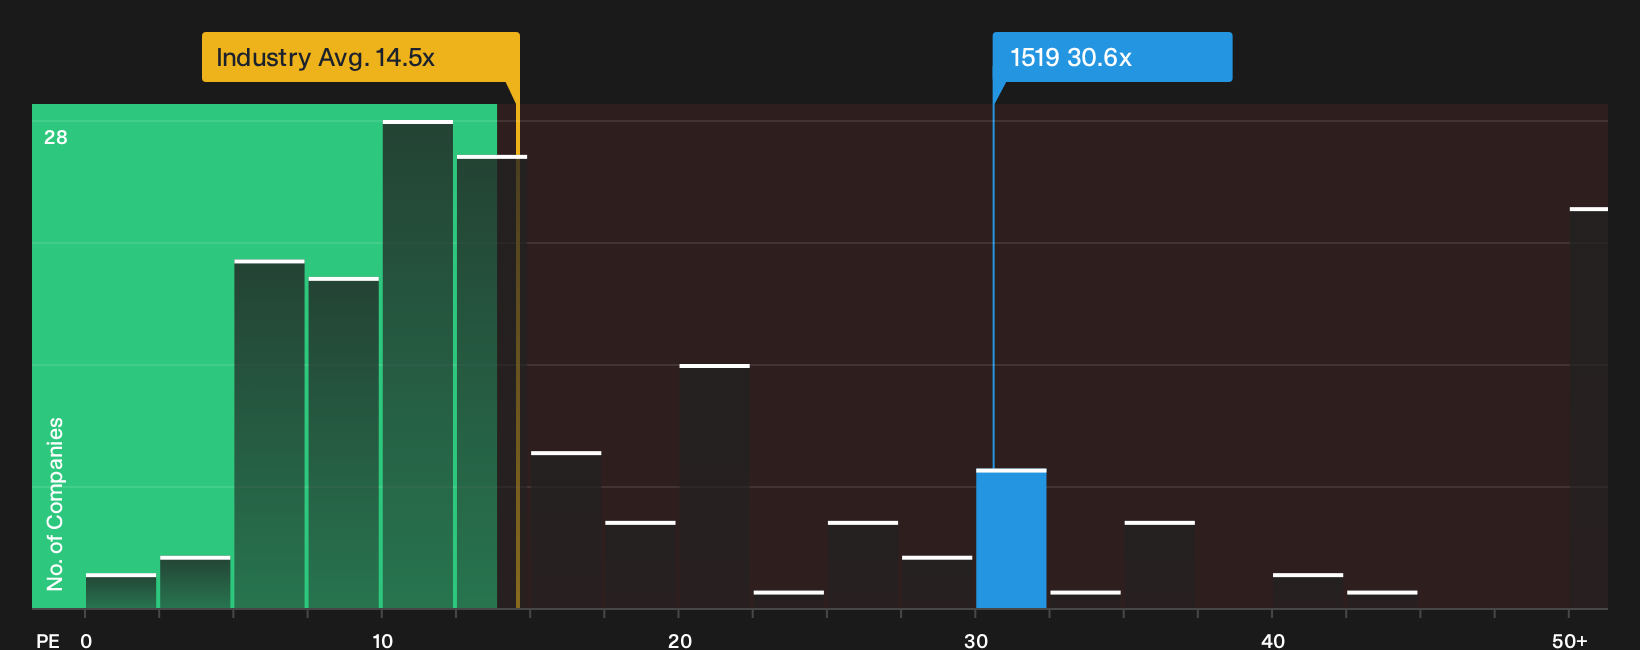
On the flip side of that 33% undervalued fair value story, the current P/E of about 30.6x for J&T Global Express sits well above the Asian logistics group at 14.5x and the 17x fair ratio. That kind of premium can limit room for error if growth or margins disappoint. Which yardstick do you trust more when the numbers disagree?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across J&T Global Express’s valuation and parcel metrics can feel confusing, so move quickly and test the numbers yourself before opinions harden. To balance both sides of the ledger, weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond J&T Global Express?
If J&T Global Express has sharpened your focus on parcel and e commerce trends, do not stop here. Use targeted screeners to surface fresh ideas before others do.
- Target resilient cash generators by scanning a 198 high quality undervalued stocks that filters for companies combining attractive prices with solid fundamentals.
- Strengthen portfolio stability by reviewing a 224 resilient stocks with low risk scores designed to spotlight businesses with fewer financial red flags and steadier profiles.
- Spot earlier stage opportunities by checking a 120 elite penny stocks with strong financials that highlights smaller companies investors may be overlooking today.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com