


Do New Drilling Deals Change The Bull Case For Valaris Stock (VAL)?
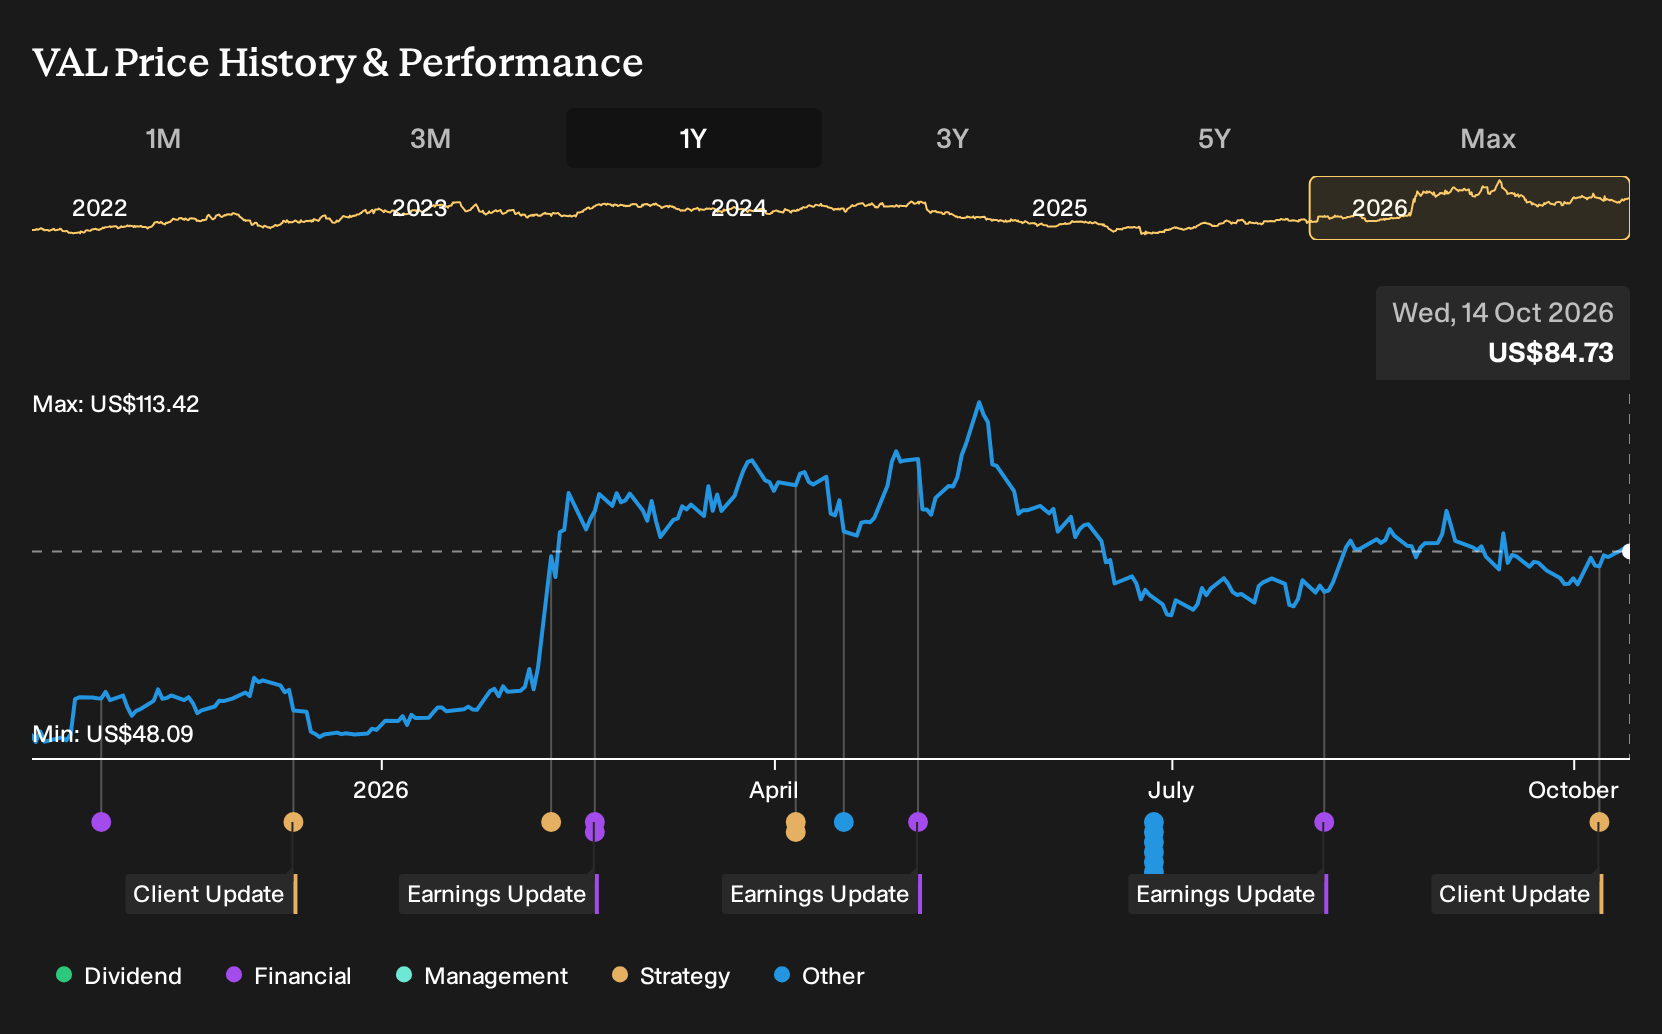
- Valaris reported a series of new offshore drilling contracts and extensions across Suriname, Australia, the North Sea and the UK, adding about $220 million of contract backlog excluding mobilization and other lump sum items.
- The mix of floater, jackup and plug and abandonment work spreads Valaris’s future activity across multiple regions and contract structures. This may help smooth utilization risk as rigs roll off existing commitments.
- We will now look at how Valaris’s investment narrative is affected by this added backlog and expanded North Sea exposure.
Valaris Investment Narrative Recap
To own Valaris, you need to think the rig fleet can stay busy enough, at firm enough day rates, to support cash generation despite a volatile earnings outlook. The new US$220m of contracts modestly extends visibility and spreads work across floaters, jackups and plug and abandonment activity, which may help near term utilization.
The biggest swing factor in the short term remains execution on existing backlog and how that feeds into reported cash flow as the Transocean merger progresses. The key risk stays the same: a weaker offshore activity set or operational downtime could leave rigs underused, especially given high non cash earnings and forecast earnings declines.
The plug and abandonment award in the Southern North Sea looks most relevant for this latest update. It is a flexible fleet contract that can use any suitable Valaris North Sea rig, runs for an estimated 341 days and carries about US$41.5m of backlog, with an annual cost escalation feature and an extra one well option.
For you, the message is clear. This kind of work aligns with the core catalyst that matters now, which is converting opportunity into contracted days while managing cost and reliability. It also illustrates risk. If North Sea conditions, regulations or customer budgets tighten, that multi rig flexibility and the long commencement window up to December 2030 could cut both ways.
Valaris' current analyst story assumes revenues of about US$2.7b and earnings of US$103.1m by 2029, built on 8.2% yearly top line growth and an earnings decline of roughly US$836.5m from US$939.6m today to that 2029 consensus level.
Uncover why Valaris' fair value indicates a 20% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate angle you might consider focuses on merger risk rather than backlog. The most cautious Valaris analysts worry that a longer antitrust process for the Transocean deal could limit the benefit of the roughly US$2.6b revenue and US$144.6m earnings they were pencilling in for 2029. Those forecasts, set before this US$220m contract update, show how wide opinion already is and why it can help to compare several narratives before deciding what this new backlog really means for you.
Explore 4 other Valaris fair value estimates, including one that suggests as much as 47% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Valaris research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Valaris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Valaris' overall financial health at a glance.
Looking for more investment ideas beyond Valaris?
Once you have a view on Valaris, it often helps to compare it with a wider set of listed peers that share similar financial traits but sit at different points in their own stories. The Simply Wall St Screener lets you filter for balance sheet strength, valuation appeal and income potential so you can quickly build a shortlist that matches what you care about most.
- If capital preservation is high on your list, focus on businesses with sturdier finances and steadier metrics by scanning a 32 resilient stocks with low risk scores that meet tighter risk thresholds.
- For investors hunting for mispriced quality, narrow in on financially sound enterprises trading below estimated intrinsic value by reviewing a 32 high quality undervalued stocks that may warrant a spot on your watchlist.
- If you rely on portfolio income, look at companies with higher yields and more robust payout records using a 7 dividend fortresses that screens for stronger dividend characteristics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com