


Shaftesbury Capital (LSE:SHC) Draws Fresh Interest On A Low P E Yet Pricey DCF View
Recent coverage of Shaftesbury Capital (LSE:SHC) focuses on a rare split verdict. A low P/E multiple hints at potential value, while discounted cash flow work points to possible overvaluation.
Over the past week Shaftesbury Capital has picked up some momentum, with a 7 day share price return of 4.77% and a 30 day gain of 1.66%, even though the year to date share price return is down 1.82% and the 5 year total shareholder return is slightly negative at 4.03%.
Spot opportunities beyond Shaftesbury Capital by scanning our hand picked 9 high quality undervalued stocks, which share a similar mix of compressed P/E ratios and mixed valuation signals.The latest uptick in Shaftesbury Capital could signal investors are warming back up to its West End portfolio, or it could simply reflect a short-term swing in sentiment. The valuation work now has to separate the two.
Price-to-Earnings of 6.7x: Is it justified?
Shaftesbury Capital trades on a P/E of 6.7x, which looks inexpensive compared to peers and the wider REITs industry given the current £1.41 share price.
The P/E ratio links what investors are paying today to the profits the property owner is currently generating. For a mixed-use West End portfolio like Shaftesbury Capital, this metric helps you see how the market values its existing earnings power from Covent Garden, Soho, Carnaby and Chinatown.
Management has turned the business profitable over the past five years, with earnings growing 34.9% per year over that period. However, the most recent year shows slower 20.4% growth and includes a large one off gain of £336.2m that flatters reported profit. In that context, a 6.7x multiple suggests the market is pricing in modest future profitability and is applying a clear discount despite analysts being in solid agreement that the share price could rise by 21.8% from here.
The discount becomes stronger when set against reference points. The P/E sits below the peer average of 10.2x and also under the European REITs industry average of 13.6x. This points to the market valuing each pound of Shaftesbury Capital earnings far lower than comparable listed landlords. It also screens cheaper than the estimated fair P/E of 11.5x, a level the valuation work indicates could be more in line with the group’s fundamentals if the market reassessed the story.
Explore the SWS fair ratio for Shaftesbury Capital.
Result: Price-to-Earnings of 6.7x (UNDERVALUED)
Still, Shaftesbury Capital relies heavily on a single London-focused portfolio, so any sustained weakness in West End footfall or rents could quickly challenge the low P/E story.
Find out about the key risks to this Shaftesbury Capital narrative.
Another view on Shaftesbury Capital’s valuation
The P/E story leans toward value. The SWS DCF model tells a different tale, with an estimated future cash flow value of £0.38 per share versus the current £1.41 price. This implies Shaftesbury Capital screens as overvalued on this method. Which signal do you give more weight to?
To see what might be driving this gap between earnings based metrics and cash flow based fair value, take a closer look at the detail in our valuation work Look into how the SWS DCF model arrives at its fair value.
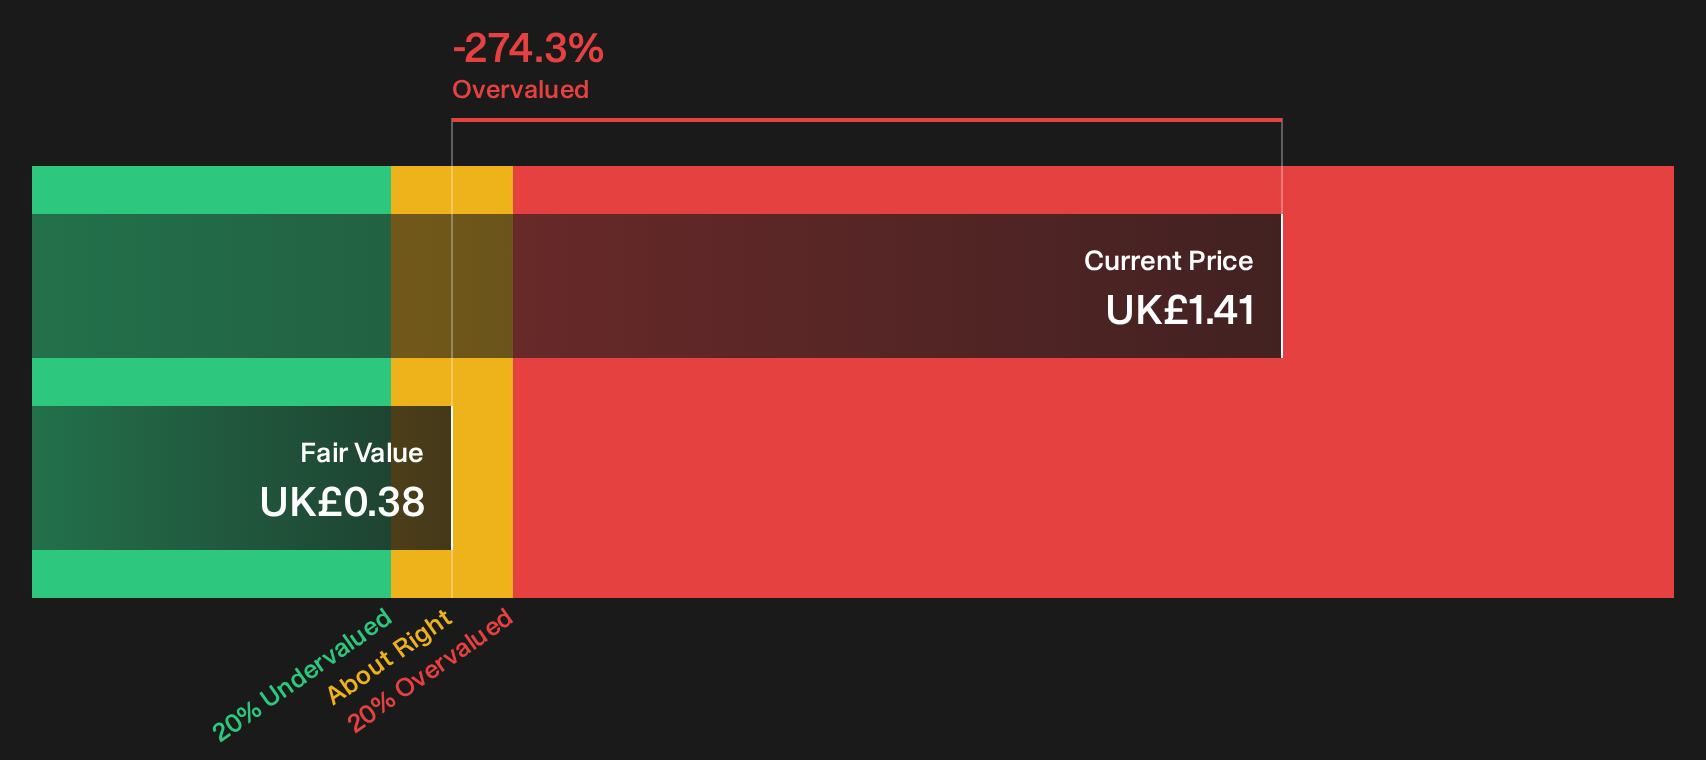
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shaftesbury Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 9 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Shaftesbury Capital often create the most interesting setups, so move fast and test the numbers for yourself before sentiment settles. To see how risks and rewards stack up side by side, review the 4 key rewards and 3 important warning signs.
Looking for more ideas beyond Shaftesbury Capital?
Do not stop at Shaftesbury Capital. Use the screener to surface fresh ideas that match your style before the best opportunities get picked over.
- Target dependable income by scanning companies that qualify as 4 dividend fortresses and see which yields match your risk tolerance.
- Hunt for quality on sale by filtering for a 9 high quality undervalued stocks that combine solid fundamentals with compressed valuations.
- Prioritise resilience first by reviewing a 4 resilient stocks with low risk scores that keep financial risk scores in check while still offering upside potential.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com