


Is CLP Holdings (SEHK:2) A Bargain As Hong Kong Sales Rise And The Dividend Holds?
CLP Holdings (SEHK:2) is back in focus after reporting a 2.5% year-on-year rise in Hong Kong electricity sales for the first nine months and affirming a third interim dividend of HK$0.63 per share.
Recent trading suggests investors are cautiously rebuilding confidence in CLP Holdings, with a year-to-date share price return of 10.7% and a 1-year total shareholder return of 22.4% that together reflect meaningful income and price gains.
Scan a curated 224 resilient stocks with low risk scores if you want more utilities and infrastructure stocks with resilience profiles similar to CLP Holdings after this latest dividend affirmation and steady Hong Kong demand.
After a solid price run and a fresh dividend decision, CLP Holdings now poses a simple timing question. Does it make more sense to step in at HK$77.40 or wait for a cheaper entry before the next move?
Most Popular Narrative: 2.6% Undervalued
CLP Holdings is trading at HK$77.40 against a widely followed fair value estimate of HK$79.49, which points to a small valuation gap that hinges on how investors view its long-term capital program and earnings quality.
Growing capital investment in grid modernization and zero-carbon infrastructure in Hong Kong, driven by upcoming cross-border transmission needs, electrification of transport, and the government's 2035 and 2050 climate targets, is expected to support steady regulated asset growth and more predictable earnings, which in turn may help sustain long-term increases in revenue and cash flow.
See why 6 investors see CLP Holdings as 3% undervalued.
Result: Fair Value of HK$79.49 (UNDERVALUED)
Still, the narrative around CLP Holdings can shift quickly if margin pressure at EnergyAustralia deepens, or if rising decarbonisation capex tightens cash flow and limits dividend flexibility.
Find out about the key risks to this CLP Holdings narrative.
Another View: CLP Holdings Looks Expensive On Earnings
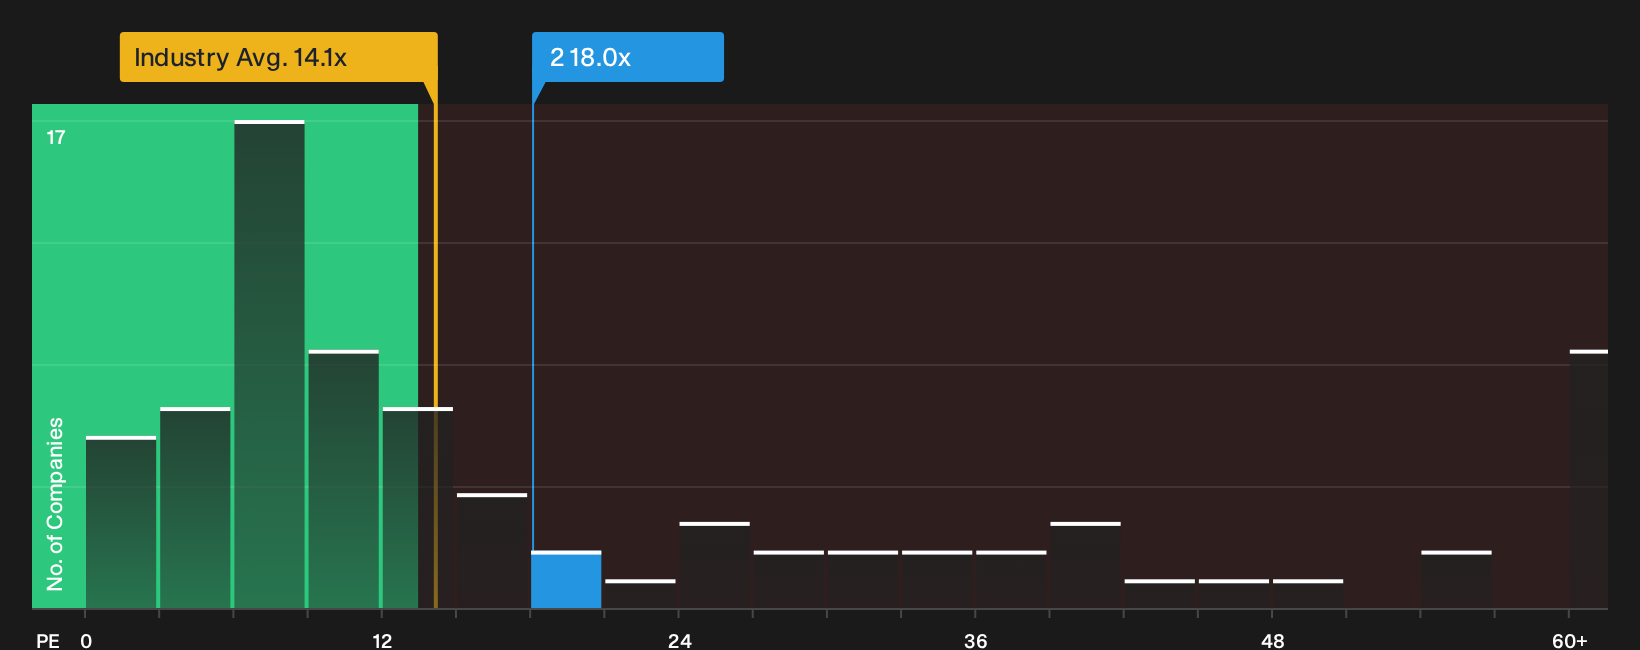
On a simple earnings lens, CLP Holdings screens as rich. The stock trades on a P/E of 18x, while the Asian Electric Utilities group sits around 14.1x and direct peers average 11.4x. The fair ratio points to 9.5x, suggesting limited room for valuation error at HK$77.40.
If the market drifts closer to that fair ratio over time, the gap would need to be closed by stronger profit growth or a lower share price. This puts the burden of proof squarely on future delivery.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around CLP Holdings feels familiar, that is the point. Take a close look at the numbers, weigh the potential pressure points, then decide how those 2 important warning signs shape your own view.
Looking for more ideas beyond CLP Holdings?
If CLP Holdings sharpened your focus, do not stop there. Broader opportunity often sits in the ideas you nearly skipped past.
- Target steadier compounding potential by reviewing a 219 dividend fortresses that could help anchor your portfolio with income-focused candidates.
- Hunt for mispriced potential through a 613 high quality undiscovered gems that highlights lesser-known businesses with strong underlying fundamentals.
- Tighten risk management by filtering for a list of solid balance sheet and fundamentals (201 results) that keeps you focused on financially robust companies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com