


Welltower (WELL) Sees Strong Senior Housing Growth, Is It Still 11% Undervalued?
Welltower (WELL) reset expectations after projecting around 19% same store senior housing NOI growth for 2026, citing higher occupancy and limited new development as key drivers within its senior housing portfolio.
Recent trading has been mixed for Welltower, with the share price up 5.0% over the past week and 24.2% year to date, while the 90 day share price return is down 3.9%. Even so, a 1 year total shareholder return of 36.7% and a very large 5 year total shareholder return above 200% point to momentum that long term holders have already seen play out.
Scan beyond Welltower and identify other real estate and income opportunities with similar momentum and fundamentals using our curated list of solid balance sheet and fundamentals (25 results)
Recent gains and a strong multi year run suggest investors see something durable in Welltower’s senior housing story. How much of that move reflects business progress rather than warmer sentiment now shows up in the valuation.
Most Popular Narrative: 11% Undervalued
Against a last close of $232.17, the most followed valuation narrative pegs Welltower’s fair value at $262.05, which frames recent price strength as still leaving a gap between market price and that thesis.
Significant off market acquisition activity, with about US$15.5b of largely newer senior housing assets bought or under contract at discounts to replacement cost and with room for occupancy improvement, gives Welltower a pipeline of properties that can contribute to future revenue and NOI expansion as they stabilize.
See why 29 investors see Welltower as 11% undervalued.
Result: Fair Value of $262.05 (UNDERVALUED)
Still, the bullish Welltower narrative depends on senior housing occupancy staying resilient, and on recycled outpatient assets not dragging on FFO and earnings more than expected.
Find out about the key risks to this Welltower narrative.
Another View: What Multiples Say About Welltower
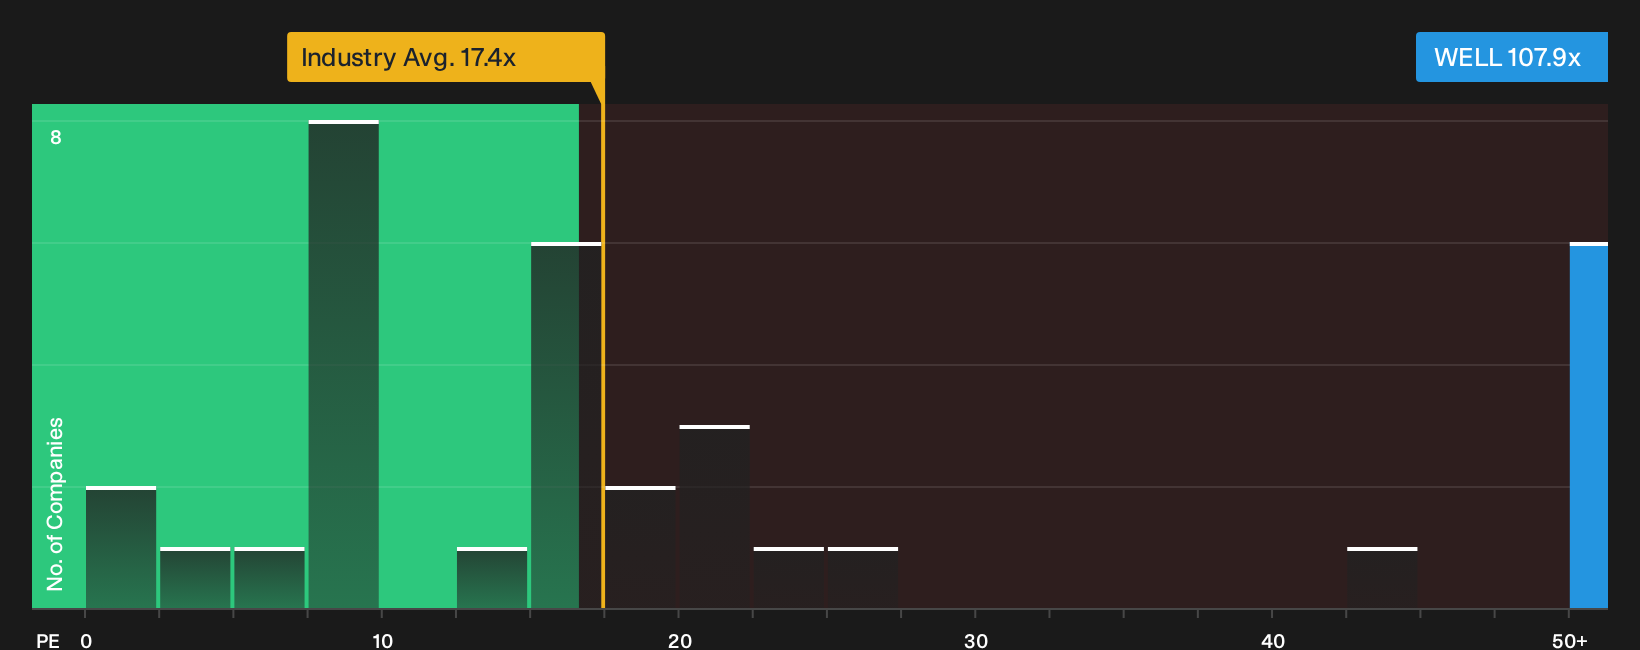
The first narrative presents Welltower as 11% undervalued relative to a forward-looking fair value estimate of $262.05. Setting that view aside, the current P/E of about 107.9x appears elevated compared with both peers at 83.6x and the broader health care REIT group at 17.2x.
Even relative to an internal fair ratio of 39.9x, the current multiple is substantially higher. This raises a simple question for investors: Is this price driven more by confidence in the senior housing narrative than by what the current earnings profile supports
To understand what that gap could imply for potential upside or downside risk, it is useful to see how today’s valuation compares with detailed earnings and peer data in a single view, beginning with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism runs through this Welltower story, but some investors clearly see reasons to be cautious as well. Move quickly, review the numbers for yourself, and weigh both the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Welltower?
Do not stop your research with a single REIT. Use the broader market to cross check what you see in Welltower and refine your opportunity set.
- Target potential bargains by reviewing companies that screen as high quality and priced below estimated value through the 32 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses with higher yields and robust fundamentals using the 7 dividend fortresses.
- Dial back risk by concentrating on resilient companies with stronger balance sheets and healthier metrics through the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com