


Ultra Clean Holdings (UCTT) Stock Trades Below Fair Value After A 119% Run
Ultra Clean Holdings has seen a sharp climb over the past few years, and after that kind of ride the real puzzle is whether the current share price still lines up with what its sales can reasonably support. For anyone looking at the stock today, the core issue is how much of that history is already baked into the price tag attached to its existing revenue base.
- Over the past 3 years the stock is up 119.2%, which puts a lot of weight on the question of how strongly its sales can continue to underpin that move.
- The business depends heavily on turning equipment demand into consistent sales and cash generation, so any change in order patterns or pricing power can quickly shift what investors are willing to pay for each dollar of revenue.
- The analysts covering Ultra Clean Holdings have run their own numbers. See what analysts think Ultra Clean Holdings's shares could be worth.
The issue now is whether Ultra Clean Holdings' current share price is adequately supported by its sales when set against the Fair Ratio benchmark.
If you are weighing whether Ultra Clean Holdings' current price is fair for its sales, it can help to compare that same question across 32 high quality undervalued stocks.
Does Ultra Clean Holdings Look Undervalued on Sales?
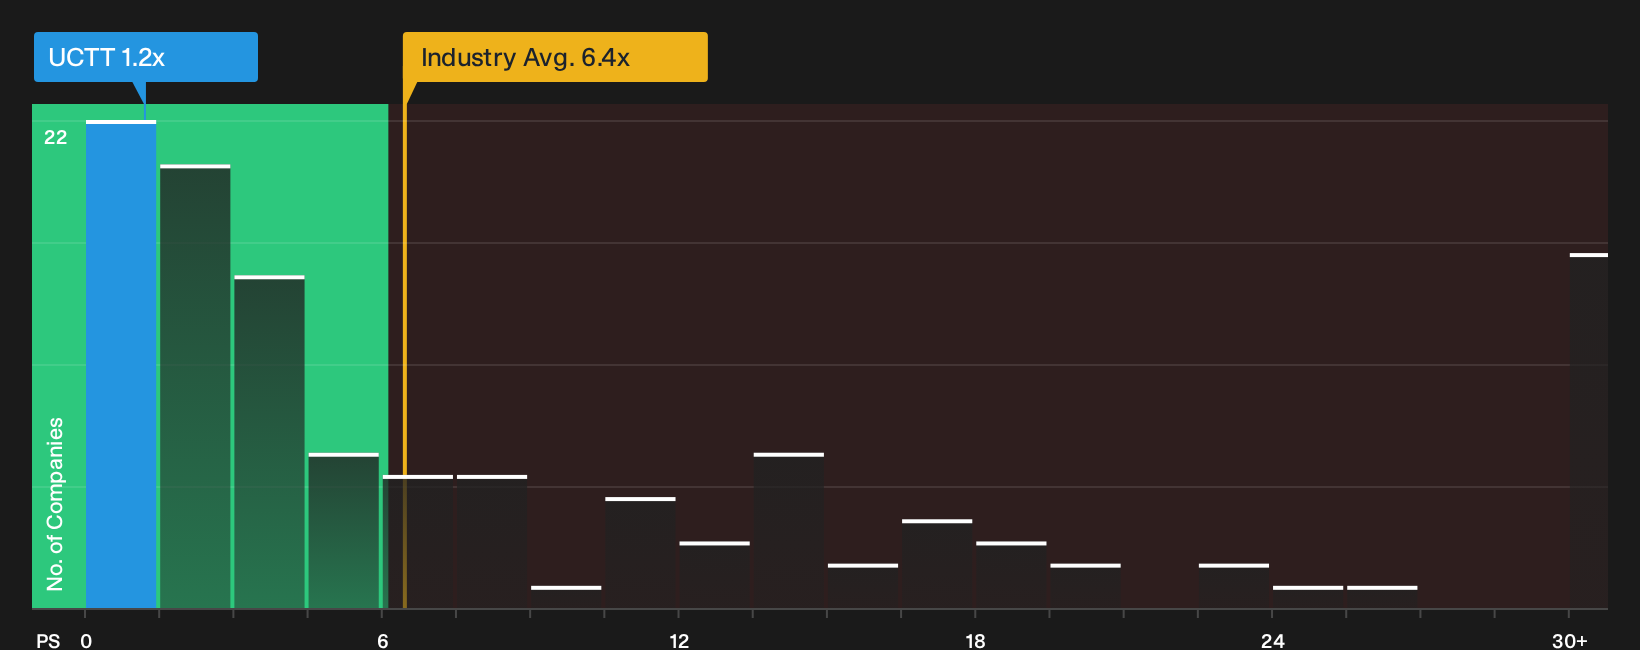
P/S works well for Ultra Clean Holdings because the business is closely tied to sales volume in the semiconductor supply chain. On this measure, the stock trades on a P/S of 1.2x, which is far below the semiconductor industry average of 6.4x and also below the peer group level of about 11.2x. That puts a relatively low market value on each dollar of revenue compared with many other chip related businesses.
The Fair Ratio framework, which adjusts the P/S benchmark for Ultra Clean Holdings based on its own growth profile, profitability, size and risk, also points to a higher multiple than where the shares trade today. The current P/S sitting below that tailored yardstick suggests the market is pricing the company at a discount to what this model would expect. The key question for you is whether the quality and durability of those sales justify a higher tag. Explore the numbers behind Ultra Clean Holdings's P/S valuation.
The Ultra Clean Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ultra Clean Holdings pick up where this valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the shares to look meaningfully richer or cheaper than they do today on the Community page. Each narrative presents Ultra Clean Holdings' implied fair worth as a thesis about the business that can be revisited over time rather than a one off snapshot.
One of the top community narratives on Ultra Clean Holdings: 59% undervalued
"A surge in AI-driven capital investment and strong expectations for new fab buildouts in 2026 support solid long-term demand for Ultra Clean's advanced process subsystems..."
Discover why this Narrative puts Ultra Clean Holdings at 59% undervalued.
One last Ultra Clean Holdings check before you stop at the share price
Before you focus only on what Ultra Clean Holdings trades for, it is worth asking who is steering the business and how their pay lines up with your expectations. See who runs Ultra Clean Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com