


Did Raised Revenue Guidance Just Shift Acadia Pharmaceuticals (ACAD) Investment Narrative?
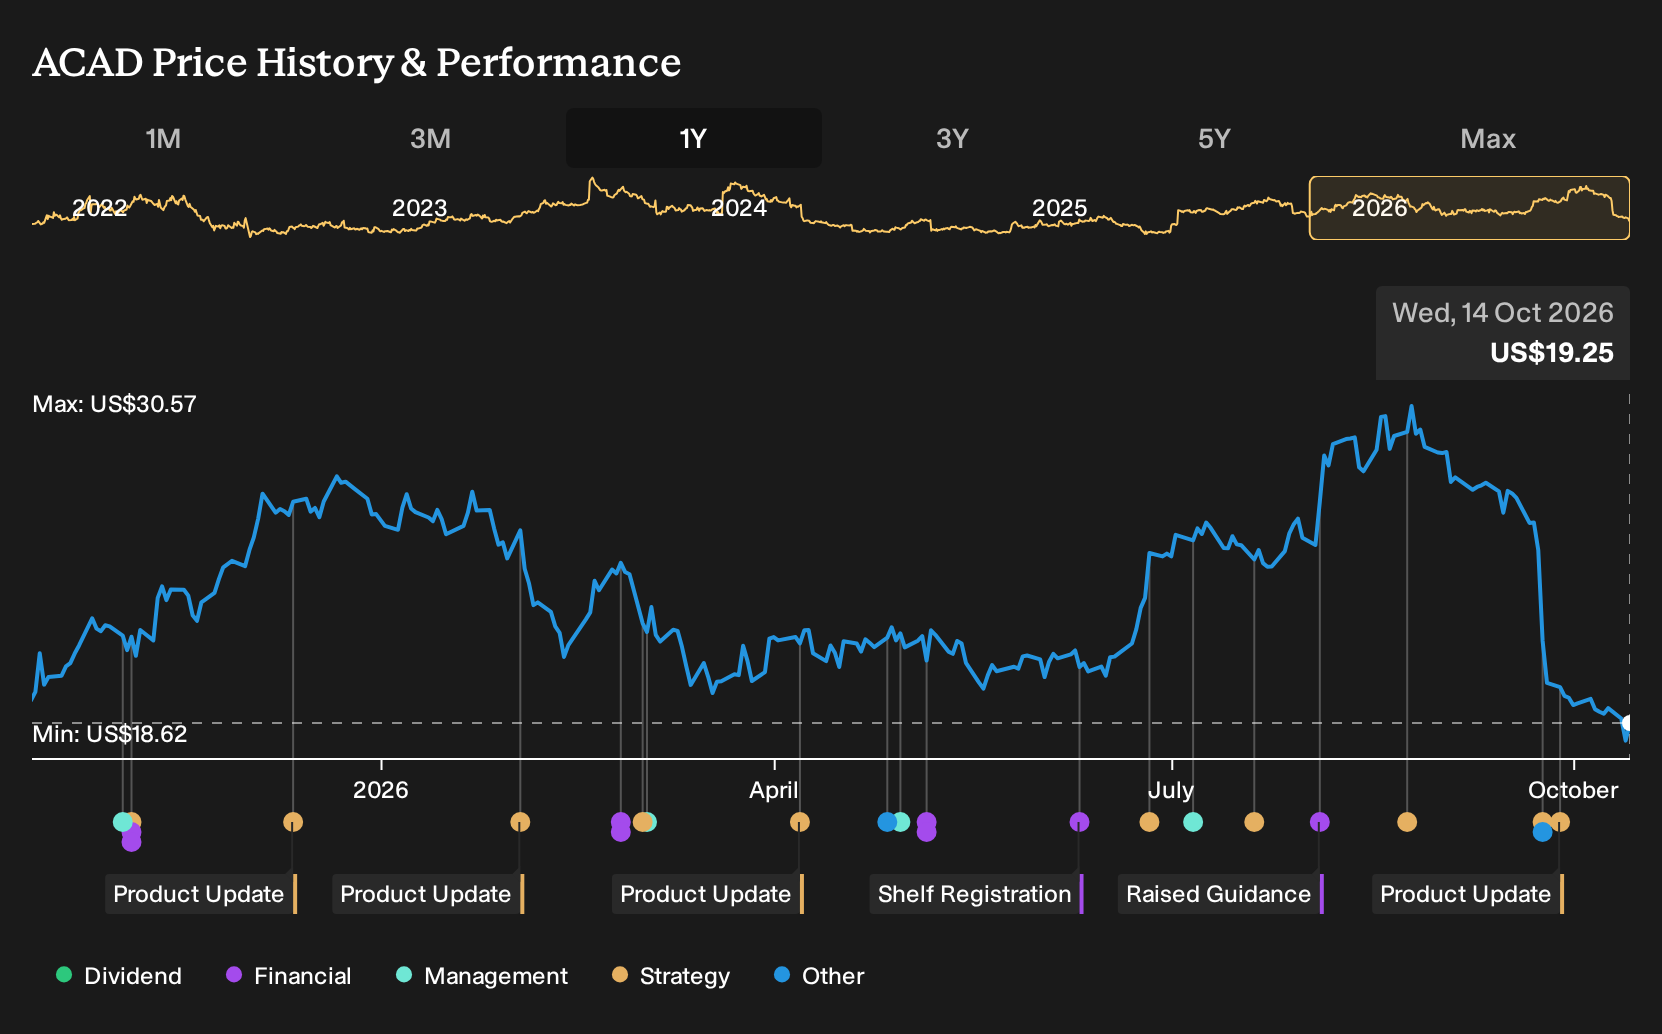
- Acadia Pharmaceuticals lifted its 2026 revenue guidance after strong Q2 performance and prescription trends for Nuplazid and Daybue, while Daybue also secured European Commission approval for treating neurobehavioral symptoms of Rett syndrome in patients aged five and older.
- Daybue’s new European authorization gives Acadia Pharmaceuticals a fresh route to expand its Rett syndrome franchise beyond the U.S. This development could change how investors think about the durability and reach of its rare disease portfolio.
- We will now explore how Acadia Pharmaceuticals' raised revenue guidance could reshape its investment narrative as Daybue expands into Europe.
Acadia Pharmaceuticals Investment Narrative Recap
To own Acadia Pharmaceuticals, you need to believe its two commercial drugs can keep doing the heavy lifting while the CNS and rare disease pipeline slowly earns its place. The raised 2026 revenue guidance points to management seeing more dependable demand for Nuplazid and Daybue in the near term, which supports this thesis on the operating side.
The near term upside still hinges on sustained prescription volume and a smooth international rollout of Daybue, with remlifanserin progress sitting in the background as a longer dated swing factor. The biggest operational risk remains that real world persistency, pricing pressure, or competition could mean Daybue and Nuplazid sales fall short of what the guidance implies.
The most relevant update here is Daybue’s European Commission approval for Rett syndrome and the plan to start launches in markets such as Germany in early Q4 2026. This creates the first ex U.S. revenue stream for trofinetide and tests how scalable Acadia Pharmaceuticals' rare disease model is outside its home market.
Execution now becomes very practical. Pricing and reimbursement negotiations, physician education, and supply chain reliability will determine how quickly European use ramps and how much it offsets any pressure on the U.S. business. Analyst rating changes, including the recent downgrade and spread in price targets, underline that investors are watching those operational milestones closely.
Acadia Pharmaceuticals' current analyst narrative projects US$1.7b in revenue and US$328.0 million in earnings by 2029, based on a 13.4% annual revenue growth rate. That outlook implies earnings falling from US$380.5 million today to the US$328.0 million forecast, a decrease of US$52.5 million by 2029.
Discover why Acadia Pharmaceuticals' fair value suggests a 67% potential upside to its current price, which may not be available for long.
Exploring Other Perspectives
One alternate view on Acadia Pharmaceuticals focuses heavily on dilution risk. The most bearish analysts were assuming 12.5% annual revenue growth to about US$1.6b and earnings falling toward US$169.4 million by 2029, well below consensus. That paints a much tougher earnings story. Use it as a reminder to weigh several narratives before reacting to the latest guidance and Daybue news.
Explore 5 other Acadia Pharmaceuticals fair value estimates, including one that suggests it could be worth just $19.22.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Acadia Pharmaceuticals research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Acadia Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Acadia Pharmaceuticals' overall financial health at a glance.
Looking for more investment ideas beyond Acadia Pharmaceuticals?
Once you have a view on Acadia Pharmaceuticals, widen the net and use the Simply Wall St Screener to compare it with other businesses that match your risk profile, income needs, and interest in long term compounding.
- For investors who care most about valuation support and quality fundamentals, consider scanning a focused set of opportunities through our 32 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than headline excitement, filter the market using our 32 resilient stocks with low risk scores.
- When you want balance sheets that can better absorb shocks and fund growth internally, start with the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com