


Monogatari (TSE:3097) Posted Strong Sales, Is The Stock Getting Expensive?
Monogatari (TSE:3097) has released unaudited sales figures for September and the first quarter, with all restaurants reporting net sales above 110% compared with the same periods last year, keeping investor focus squarely on recent performance.
Investors have been leaning into that sales momentum, with Monogatari’s share price at ¥5,620 after a 30.09% year to date share price return and a 42.36% one year total shareholder return, signalling firm positive sentiment rather than fading enthusiasm.
Scan how Monogatari’s recent sales strength compares with other consumer-focused stocks showing resilient demand by reviewing the curated 72 high quality undiscovered gems.
Bulls point to Monogatari’s sales momentum and strong recent returns. Bears flag a stretched valuation versus fair P/E and peers. Do the current figures still justify the premium investors are paying?
Price-to-Earnings of 24.7x: Is it justified?
Monogatari trades on a P/E of 24.7x, which sits above its own estimated fair P/E of 23.2x and above the broader JP Hospitality average of 21.9x. The current share price of ¥5,620 therefore reflects a premium rating tied to recent strength.
The P/E ratio compares the equity value investors are willing to pay today for each unit of current earnings. For a restaurant operator whose earnings are already established rather than highly speculative, this metric gives a direct read on how much optimism is embedded in the price versus current profit generation.
Forecasts in the statements suggest earnings are expected to grow 9.9% per year while revenue is projected to rise 9.4% per year, with both metrics slightly ahead of the broader JP market and supported by a recent 42% earnings increase over the past year. In that context, a P/E above the sector average signals that investors are paying up for Monogatari’s higher recent earnings growth and the view that these forecasts are credible, as underlined by the statement that analysts show a statistically confident range of agreement.
Compared with the JP Hospitality industry average P/E of 21.9x, Monogatari’s 24.7x multiple is clearly richer. The fact that it is also above the estimated fair P/E of 23.2x points to limited valuation slack if growth or margins soften from here. The peer group average P/E of 64.9x in the data looks far higher, which keeps Monogatari looking restrained next to a small subset of more aggressively priced stocks. However, the fair ratio level of 23.2x still suggests a multiple the market could move towards if enthusiasm cools.
Explore the SWS fair ratio for Monogatari.
Result: Price-to-Earnings of 24.7x (OVERVALUED)
Still, belief in Monogatari’s premium could be upended if sales momentum cools or if sector peers close the valuation gap and compress that P/E multiple.
Find out about the key risks to this Monogatari narrative.
Another View: What The SWS DCF Model Says
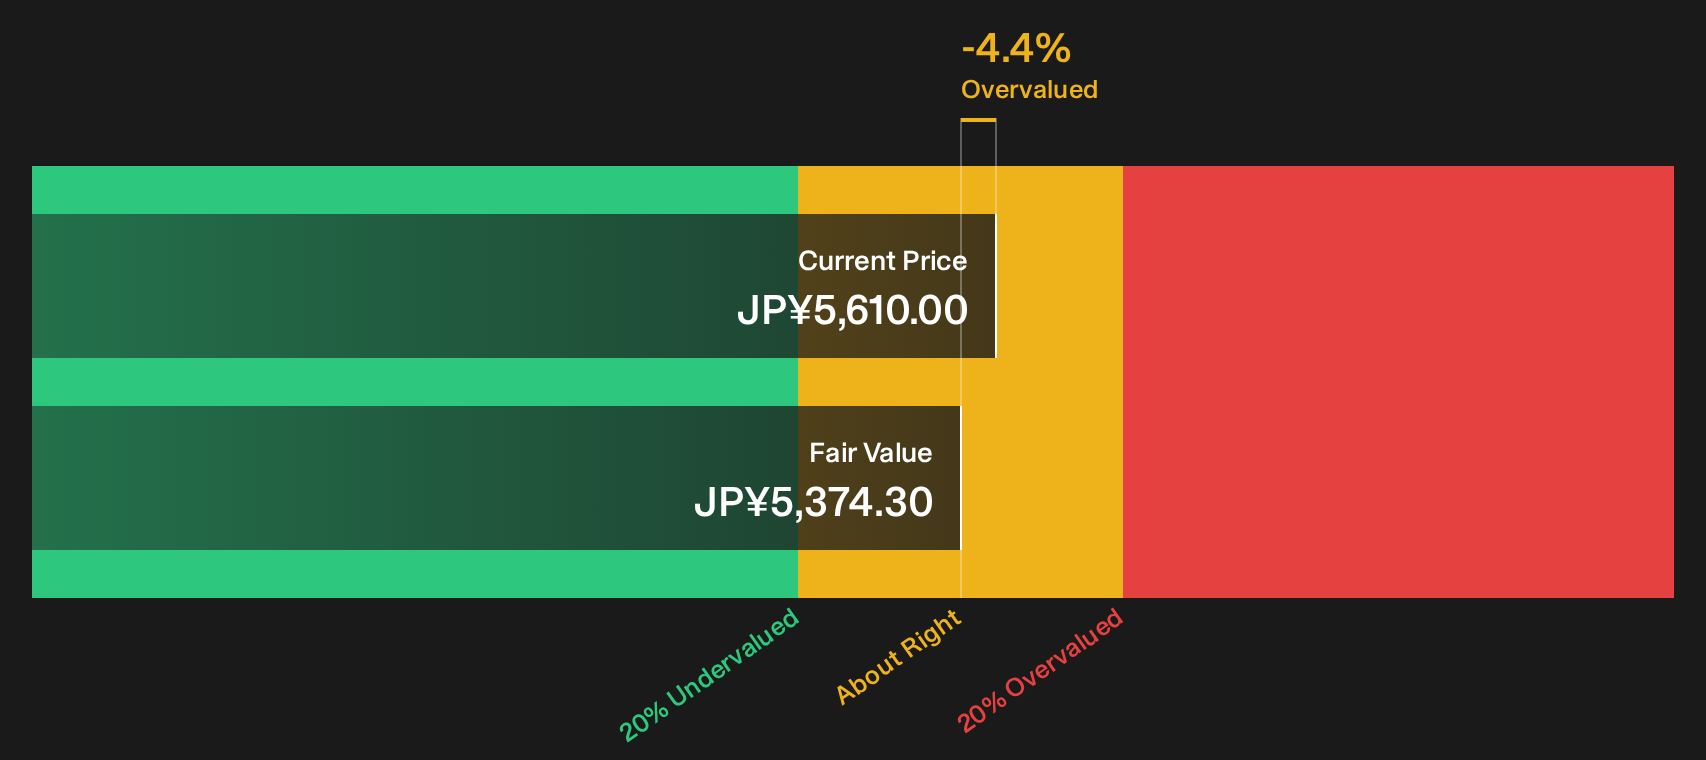
The P/E picture paints Monogatari as slightly expensive, and the SWS DCF model broadly agrees with that message. The shares trade at ¥5,620 while the estimated future cash flow value sits at ¥5,378.16, which points to the stock being mildly overvalued on that lens as well.
That small gap leaves investors asking a simple question. Is this a harmless premium for quality, or a thin margin of safety if sentiment toward Monogatari cools?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Monogatari for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Monogatari is clearly optimistic, so do not just take the headline multiples at face value when your own judgment matters most. Move quickly, review the underlying metrics for yourself, and weigh those positives against your risk tolerance by checking the 3 key rewards
Looking for more Monogatari sized ideas?
If you stop with Monogatari, you miss a wider field of potential opportunities that match different risk levels, income needs, and valuation preferences.
- Target stronger value by using the 15 high quality undervalued stocks that filters for quality companies trading on cheaper multiples than their fundamentals suggest.
- Lock in potential income streams through the 32 dividend fortresses that focuses on higher yielding businesses with more robust payout profiles.
- Dial back potential downside by reviewing the 21 resilient stocks with low risk scores that highlights companies with more resilient financial and risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com