


How Salesforce Hunter Tie Up At ZoomInfo Technologies (GTM) Has Changed Its Investment Story
- Salesforce recently confirmed ZoomInfo as a core data partner for Hunter, its new outbound sales agent for Sales Cloud, while ZoomInfo expanded its GTM.AI platform using Workbounce to blend external market data with internal go to market knowledge for sales teams.
- These moves push ZoomInfo deeper into everyday seller workflows by embedding its data directly inside tools like Salesforce rather than relying on separate logins or manual exports.
- We will look at how ZoomInfo's deeper integration into Salesforce workflows could reshape the existing investment narrative investors rely on.
Scan how ZoomInfo Technologies fits into the broader AI tooling wave by lining it up against a curated set of 92 AI infrastructure stocks.
ZoomInfo Technologies Investment Narrative Recap
To own ZoomInfo Technologies, you need to believe its role as a go to market data and workflow layer for enterprise sales teams can offset pressure from declining downmarket revenue and high debt. The recent Salesforce Hunter partnership and broader GTM.AI integrations support that view operationally, but do not remove concentration, commoditization, or regulatory risk.
In the near term, the key catalyst is whether deeper embedding into tools like Salesforce, ClickUp, and n8n converts into stickier, higher value enterprise relationships as the business focuses upmarket. The biggest current risk remains that large customers gain too much pricing power or switch to alternatives, while smaller customer churn and regulatory costs continue to weigh on growth.
The Salesforce Hunter announcement links directly to the main thesis on ZoomInfo Technologies. It pushes ZoomInfo data from a separate app into the daily rhythm of Sales Cloud users. That is exactly where the platform needs to live if it is going to be treated as critical infrastructure rather than a nice to have add on.
Hunter also leans on GTM.AI, the same context layer now wired into tools like ClickUp, Workbounce powered workflows, and n8n. If those agents drive more automated outreach and less manual list building, the operational test will be clear: do customers standardize on ZoomInfo’s graph for that automation, or do competitors and internal first party data crowd it out?
ZoomInfo Technologies' current analyst narrative points to revenues of US$1.2b and earnings of US$391.8m by 2029, based on a forecast revenue decline of 1.3% per year and a move from a current loss of US$541.0m to those future profits, which implies an earnings swing of about US$932.8m.
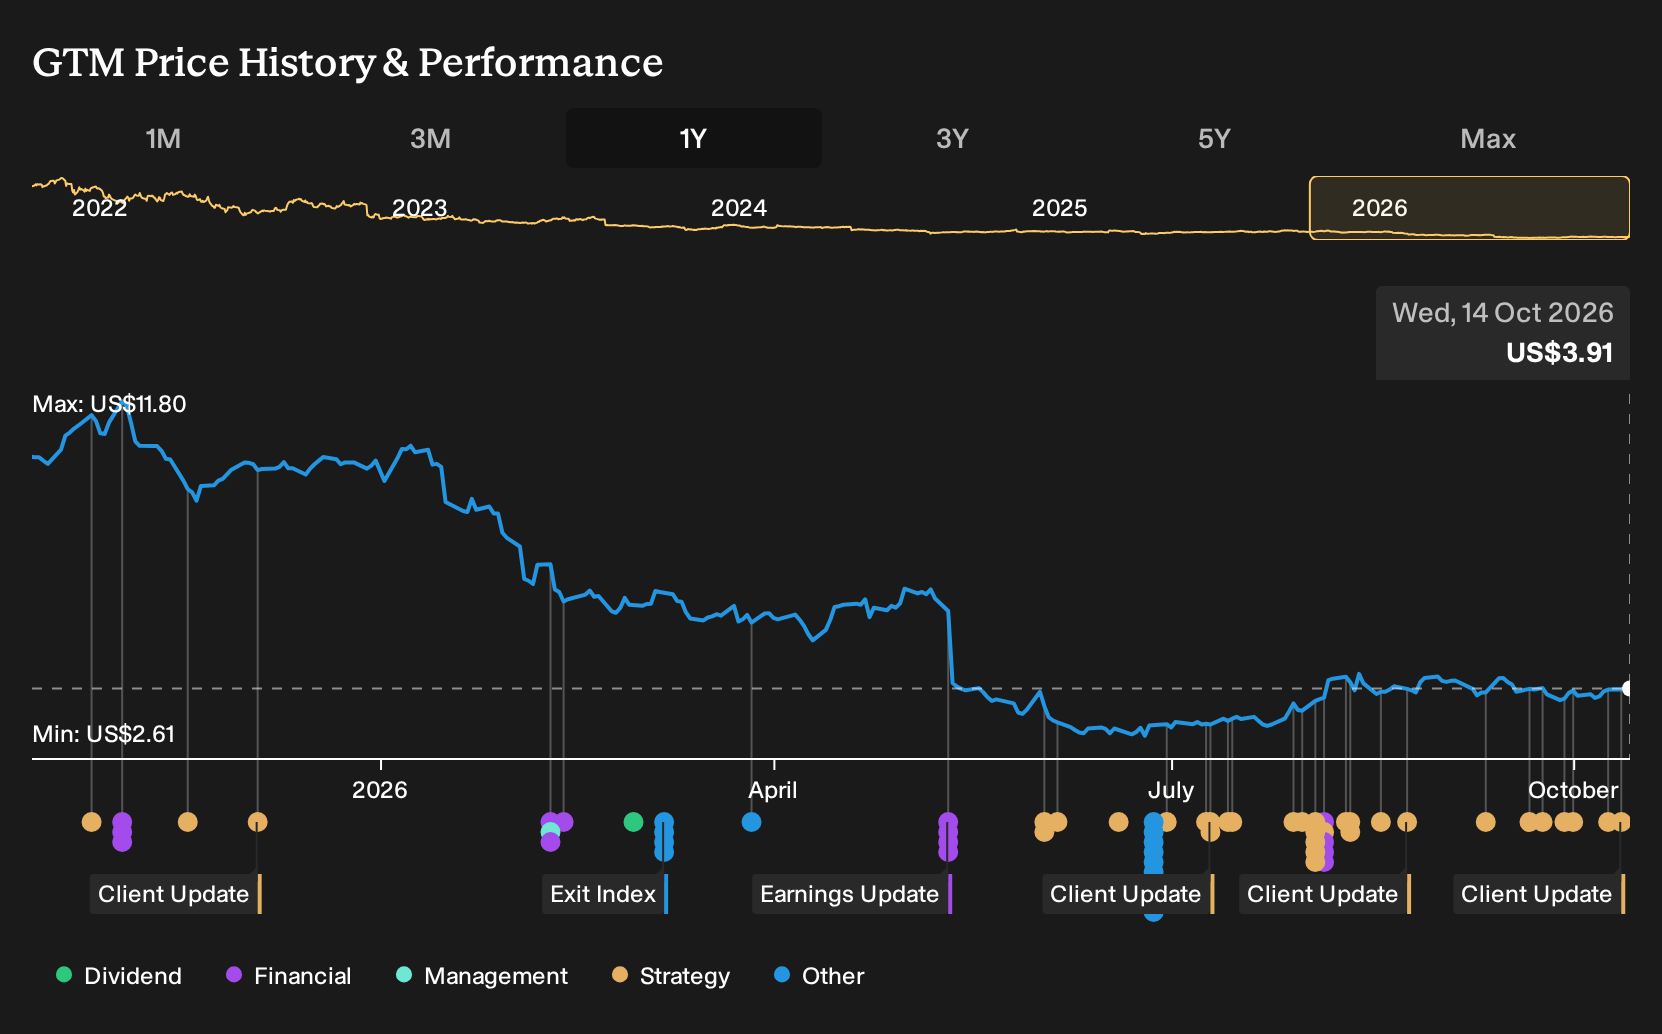
Uncover why ZoomInfo Technologies' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses less on customer concentration and more on the risk that ZoomInfo’s AI transition simply does not move the revenue needle. The most cautious analysts were penciling in about US$1.1b of sales and US$300.6m of earnings by 2029 before this Salesforce Hunter news, which shows just how wide opinion can run. You can treat this partnership as a fresh input and stress test both the consensus and the bearish case for yourself.
Explore 4 other ZoomInfo Technologies fair value estimates, including one that suggests it could be worth just $4.58.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ZoomInfo Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ZoomInfo Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ZoomInfo Technologies' overall financial health at a glance.
Looking For More Ideas Beyond ZoomInfo Technologies?
If the ZoomInfo Technologies story has sharpened your thinking, use that momentum to scan a wider set of opportunities. A focused screener can help you quickly line up companies against the traits you care about most, whether that is value, balance sheet strength, or lower risk profiles.
- If you want to focus on companies that look cheap relative to their fundamentals, start with a curated group of 32 high quality undervalued stocks that pair financial quality with more modest pricing.
- For investors who care most about resilience and downside protection, consider a 32 resilient stocks with low risk scores that filters for businesses with more measured risk scores.
- When balance sheet strength is non negotiable for you, scan a list of solid balance sheet and fundamentals (25 results) to find firms that combine cleaner finances with underlying business durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com