


How Investors May Respond To Avis Budget Group (CAR) $650 Million Settlement
- Avis Budget Group reported softer travel demand and a smaller Americas fleet, yet kept sales stable, increased adjusted EBITDA and held full year profit guidance, while also settling a US$650 million short swing profits claim with Pentwater Capital that management expects to receive by year end 2026.
- The rental operator is prioritising earnings quality over rental volume, running a 5.4% smaller Americas fleet at a record 73.2% utilisation. It plans to use cash flow, together with the Pentwater settlement, to reduce its sizeable debt load and net corporate leverage.
- We will look at how Avis Budget Group's tighter fleet and US$650 million settlement reshape the existing investment narrative and risk balance.
Scan how other car rental and mobility players are positioned by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
Avis Budget Group Investment Narrative Recap
To own Avis Budget Group, you need to believe a smaller, tighter fleet can keep generating solid EBITDA while the balance sheet improves. The near term story is about execution on utilisation, recall management and pricing discipline, not headline rental days. The recent sell off after the short squeeze does not directly change that operating task.
The most important near term catalyst is whether utilisation and earnings hold up while travel demand is softer and recall disruptions persist. The biggest risk remains high leverage and interest costs. If profitability weakens or recall costs escalate, progress on reducing that debt load could slow meaningfully.
The US$650 million Pentwater settlement is the clearest recent announcement tied to this news flow. Management plans to channel it, alongside free cash flow, into repaying corporate debt including a portion of 2027 notes. For a business with interest payments not well covered by earnings today, that intended use matters.
If execution on the tighter fleet strategy sustains EBITDA while that cash is applied to liabilities, leverage and interest expense could trend lower over time. That would directly influence the key catalysts many investors are watching in Avis Budget Group, from balance sheet resilience to the flexibility to keep investing in premium offerings and digital fleet tools.
Avis Budget Group's current analyst narrative points to revenues of US$12.2b and earnings of US$592.8m by 2029, built on assumed yearly top line growth of 1.3% and a swing in profitability from an earnings loss of US$636.0m today to a projected profit of US$592.8m, which is an earnings change of roughly US$1.23b.
Uncover why Avis Budget Group's fair value indicates a 20% potential upside to its current price that could narrow quickly.
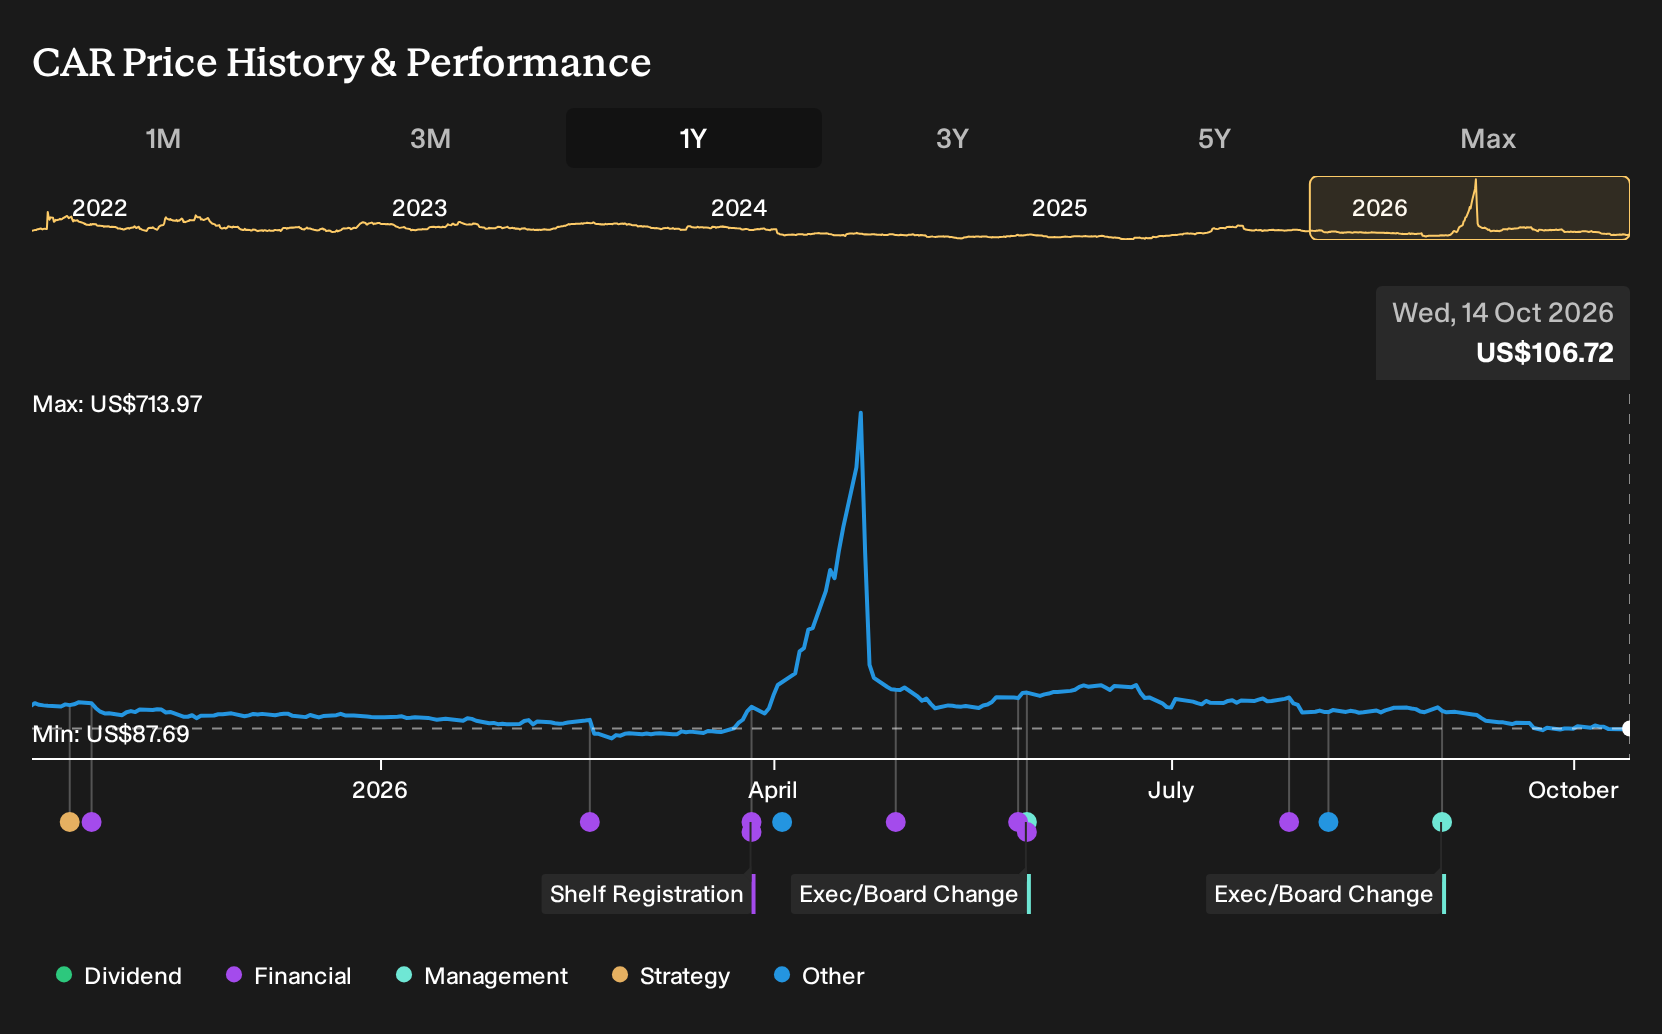
Exploring Other Perspectives
Some of the most optimistic analysts put far more weight on the Avis Budget Group deleveraging story. Before this news, the bullish camp was already pencilling in about US$12.5b of revenue and US$666.4m of earnings by 2029, compared with the US$12.2b and US$592.8m in the baseline view. You can use those very different trajectories to test how this Pentwater cash inflow and the fleet reset might shift each narrative over time.
Explore 2 other Avis Budget Group fair value estimates, including one that suggests upside of as much as 221% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Avis Budget Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avis Budget Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avis Budget Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Avis Budget Group?
If the Avis Budget Group story has sharpened your thinking about balance sheets, earnings quality and future potential, you can use that same lens across a wider universe of companies with the Simply Wall St Screener.
- For investors hunting for companies that trade below what their fundamentals might justify, a good next step is to review a curated set of 32 high quality undervalued stocks that combine quality with attractive pricing.
- If income is a priority and you care about cash returns to shareholders, focus on businesses in the 7 dividend fortresses that pair higher yields with an emphasis on resilience.
- When downside protection matters most, narrow your search to businesses in the 32 resilient stocks with low risk scores and compare their profiles with the risk picture you see at Avis Budget Group.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com