


Brinker International (EAT) Is Back In The Spotlight, What Is Drawing Attention?
S&P Global Ratings just shifted its outlook on Brinker International (EAT) to positive, affirming a BB+ credit rating that reflects solid traffic trends, lower debt levels, and consistent operating execution.
The positive shift in S&P’s outlook lands alongside a sharp improvement in momentum, with Brinker International’s share price up 10.2% over the past week and 34.8% year to date, even after a 4.6% pullback over 30 days. That move sits on top of a 56.1% 1-year total shareholder return and a very large 3-year total shareholder return above 5x. This suggests investors are reacting to both the upgraded credit view and recent product news like Chili’s new Chicken Parm Big Crispy launch, while also reassessing the long-term risk profile at a recent share price of US$204.24.
Scan for other restaurant and consumer stocks showing similar credit and momentum shifts by reviewing the hand picked 32 high quality undervalued stocks, which may share traits with Brinker International.
After that kind of surge and a credit outlook turning more upbeat, Brinker International now asks a simple question of buyers: Does the current valuation still leave enough upside to justify the risk being taken on today?
Most Popular Narrative: 22% Undervalued
Brinker International's most followed narrative points to a fair value of $262.59 compared with the last close at $204.24. This puts the recent rally into context and anchors the debate around how durable Chili's unit economics really are.
Brinker International is extending its menu work at Chili's, including upgrades in core items and beverages, on top of a higher earning restaurant model where AUVs have reached about $5 million and restaurant operating margin has widened by 660 basis points. This can support further revenue and earnings growth if traffic and mix benefits continue to scale.
See why 31 investors see Brinker International as 22% undervalued.
Result: Fair Value of $262.59 (UNDERVALUED)
Still, the whole Brinker International story can fray quickly if Chili’s value pitch loses traction with guests or if persistent wage and commodity inflation squeezes margins.
Find out about the key risks to this Brinker International narrative.
Another View on Brinker International’s Valuation
While the most popular narrative flags Brinker International as 22% undervalued against a fair value of $262.59, the SWS DCF model tells a cooler story. On that cash flow view, EAT at $204.24 sits above an estimated value of $169.80, which points to an overvalued signal instead. Which lens do you trust more when real cash flows hit the page?
For a closer look at how this cash flow view is built and where the sensitivities sit, take a moment to Look into how the SWS DCF model arrives at its fair value.
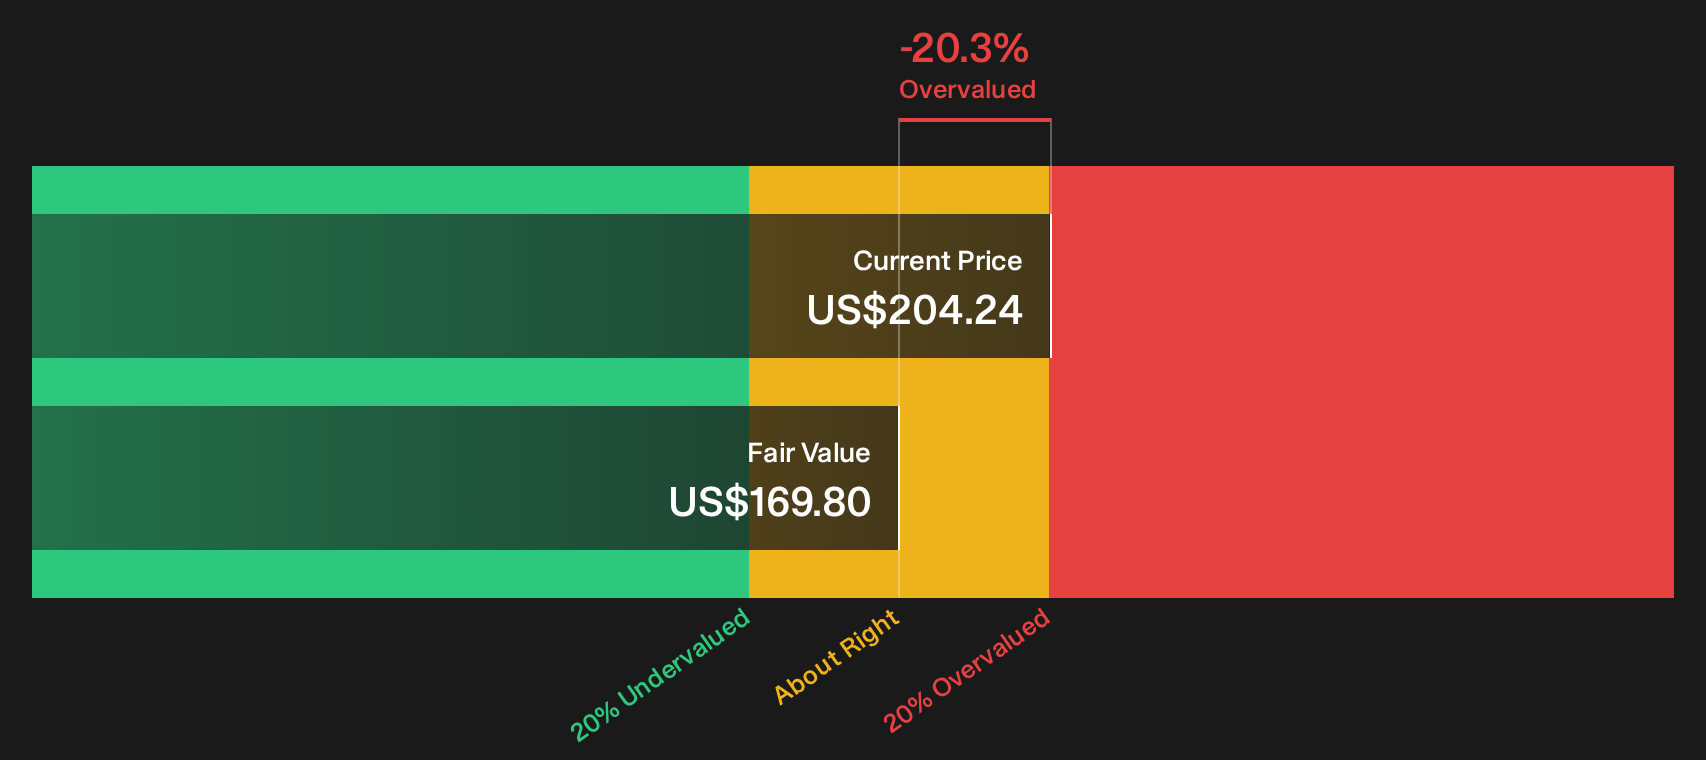
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brinker International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Brinker International feels familiar, you may want to act quickly. Test the data yourself and pressure test both sides of the debate using the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Brinker International?
If Brinker International has sharpened your appetite for opportunities, do not stop here. Broaden your watchlist and pressure test your thesis against other compelling setups.
- Target higher income potential by reviewing companies in the 7 dividend fortresses that combine robust yields with disciplined payout profiles.
- Spread risk more deliberately by scanning the 32 resilient stocks with low risk scores to focus on businesses with steadier fundamentals and fewer red flags.
- Get ahead of the crowd by searching the 20 high quality undiscovered gems where underfollowed stocks with solid financial footing may be waiting for fresh attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com