


3 Great Canadian Dividend Stocks To Own In October 2026
Wholesale inflation in the US just jumped by the most in four years as gas prices surged, reminding investors how quickly rising costs can rattle markets and income plans. Reliable Canadian dividend payers yielding more than 3% can act like a paycheck that does not depend on day to day market moods. This piece highlights three high yielding contenders with covered, growing, and historically steady payouts.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding businesses with covered, growing, and stable dividends. However, if you want the standouts, these 3 dividend aristocrats stocks are the most outstanding.
Canadian Tire Corporation (TSX:CTC.A)
Canadian Tire Corporation ties a familiar retail brand to a meaningful real estate and financial arm, and that mix is what earns it a place in a dividend screen that prizes covered, consistent payouts rather than headline growth alone.
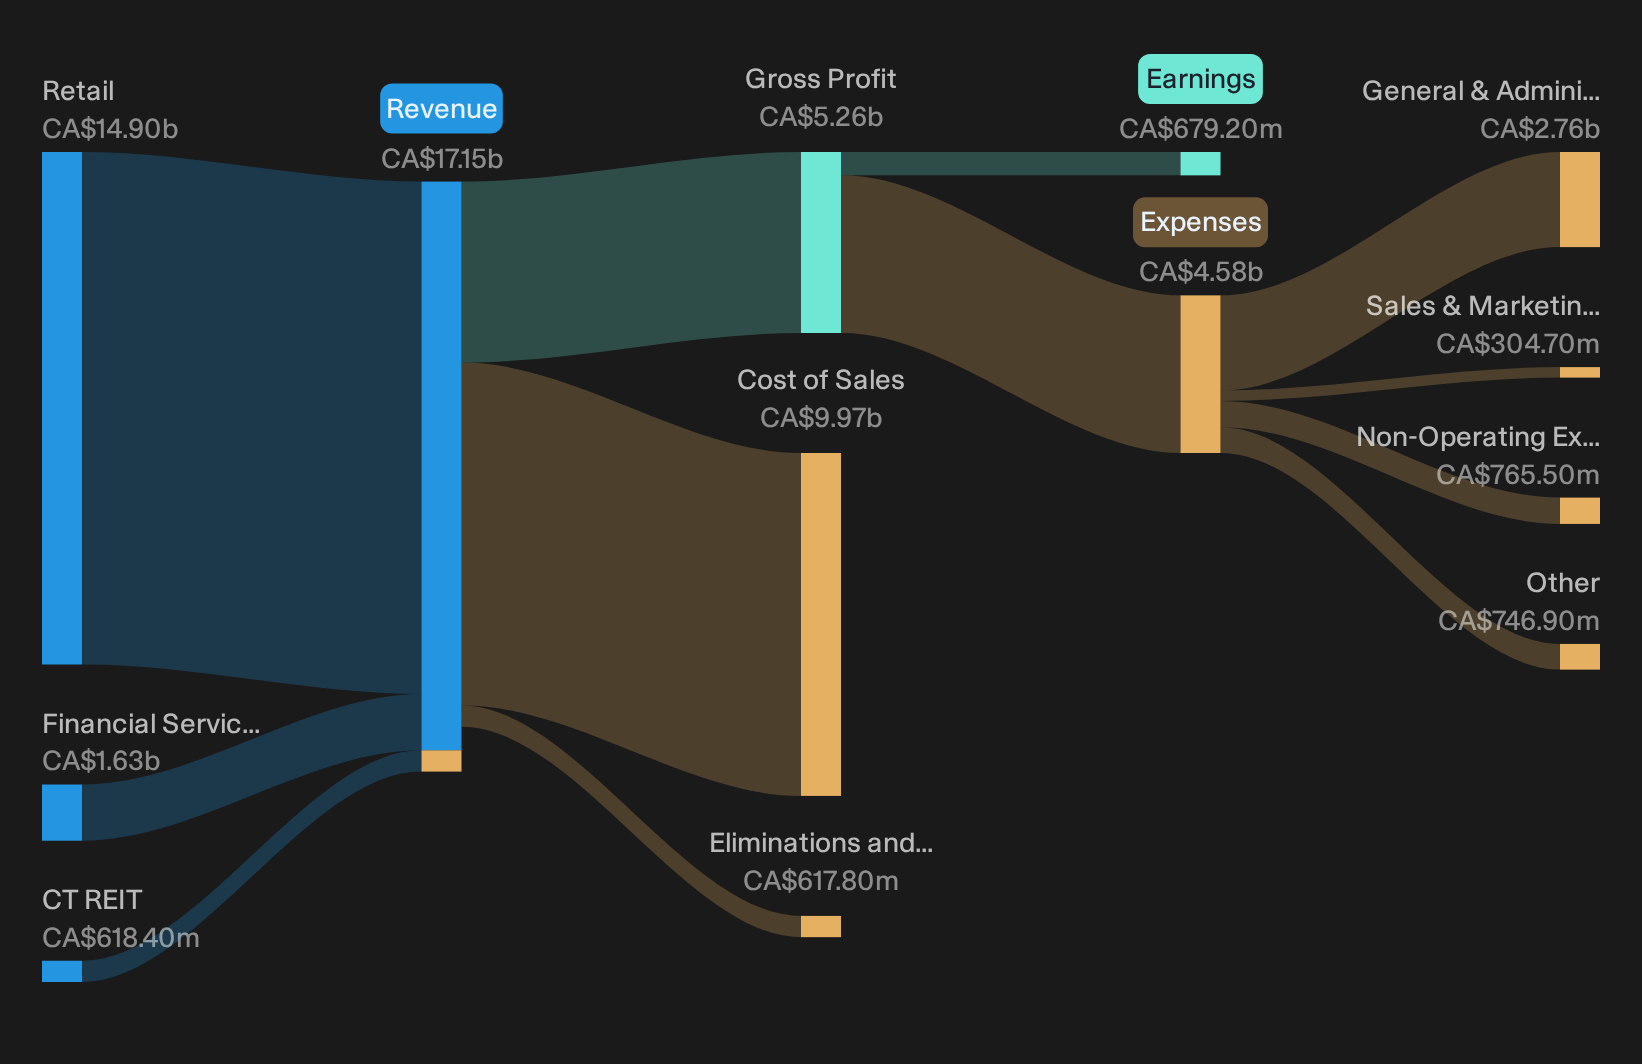
Canadian Tire Corporation runs a broad retail network across automotive, apparel, sports and home goods. CT REIT owns Canadian Tire anchored properties that feed steady rent into the group, and a financial arm offers credit cards and savings products. Most revenue comes from Retail at about CA$14.9b, with CT REIT contributing roughly CA$618 million and Financial Services about CA$1.6b, and the group carries a market value near CA$10.1b.
"The wider rollout of AI pricing and customer analytics tools, such as the platforms used to shape promotions and category occasions, is expected to influence assortment, promo intensity and regular pricing in ways that support gross margin and earnings quality."
For income focused investors, what happens if a single key assumption in that broader earnings and margin story quietly shifts over the next few years?
If that assumption shifts, you need the full context in the full narrative for Canadian Tire Corporation to see where Canadian Tire could be quietly decoupling from headline retail risk.
Freehold Royalties (TSX:FRU)
Freehold Royalties is a Calgary based royalty owner that collects production based income from oil and gas operators, generating about CA$322 million from exploration and production royalties and supporting a higher yielding dividend stream, with the stock valued around CA$2.8b.
Where Canadian Tire leans on retail spending and credit income, Freehold Royalties brings in cash by staying above the drill bit and letting operators do the heavy lifting. This can create the kind of top line cash flow profile that may appeal to dividend focused investors.
"Freehold leases its mineral rights (Mineral Title) or gross overriding royalty (GORR) to third-party operators and receives a "top-line" share of each barrel of oil or gas produced. This model provides a more defensive shield against fluctuations in commodity prices compared to E&P companies, while enabling immediate participation in price increases."
The real test is what happens to that payout if a single pressure on cash coverage or funding costs quietly shifts in the background.
That quiet shift is exactly why the full narrative for Freehold Royalties explores how Freehold Royalties manages payout risks while seeking upside potential in an accelerating royalty cycle.

North West (TSX:NWC)
The North West Company runs essential grocery, discount and convenience stores that help underpin a covered dividend, with most cash coming from everyday spending in remote and rural communities. It generates about CA$1.5b of revenue in Canada and CA$1.1b internationally and has a market value near CA$2.6b.
A certified 3.03% yield backed by recurring supermarket style spending in hard to reach regions makes North West Company a clear Dividend Powerhouses candidate. Earnings and margins look steady rather than fast growing. Dividend reliability increasingly hinges on what happens if a single funding cost assumption shifts.
When that funding assumption moves, the analysis report for North West shows where North West’s payout strength may outlast short term rate pressure.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds, the clean entry points are often taken quickly while prices keep rising. Scan under the radar for now and consider acting early.
- Explore potential high-yield income opportunities by scanning curated 3 dividend fortresses before more investors notice the payout strength and influence entry prices.
- Gain exposure to the infrastructure build-out by reviewing focused 92 AI infrastructure stocks while capital is still shifting into the companies enabling data center and AI development.
- Position for possible resource momentum by checking concentrated 35 elite gold producer stocks before renewed attention affects producer valuations and reduces your room for error.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com