


What Oil States International Doubters Overlooked
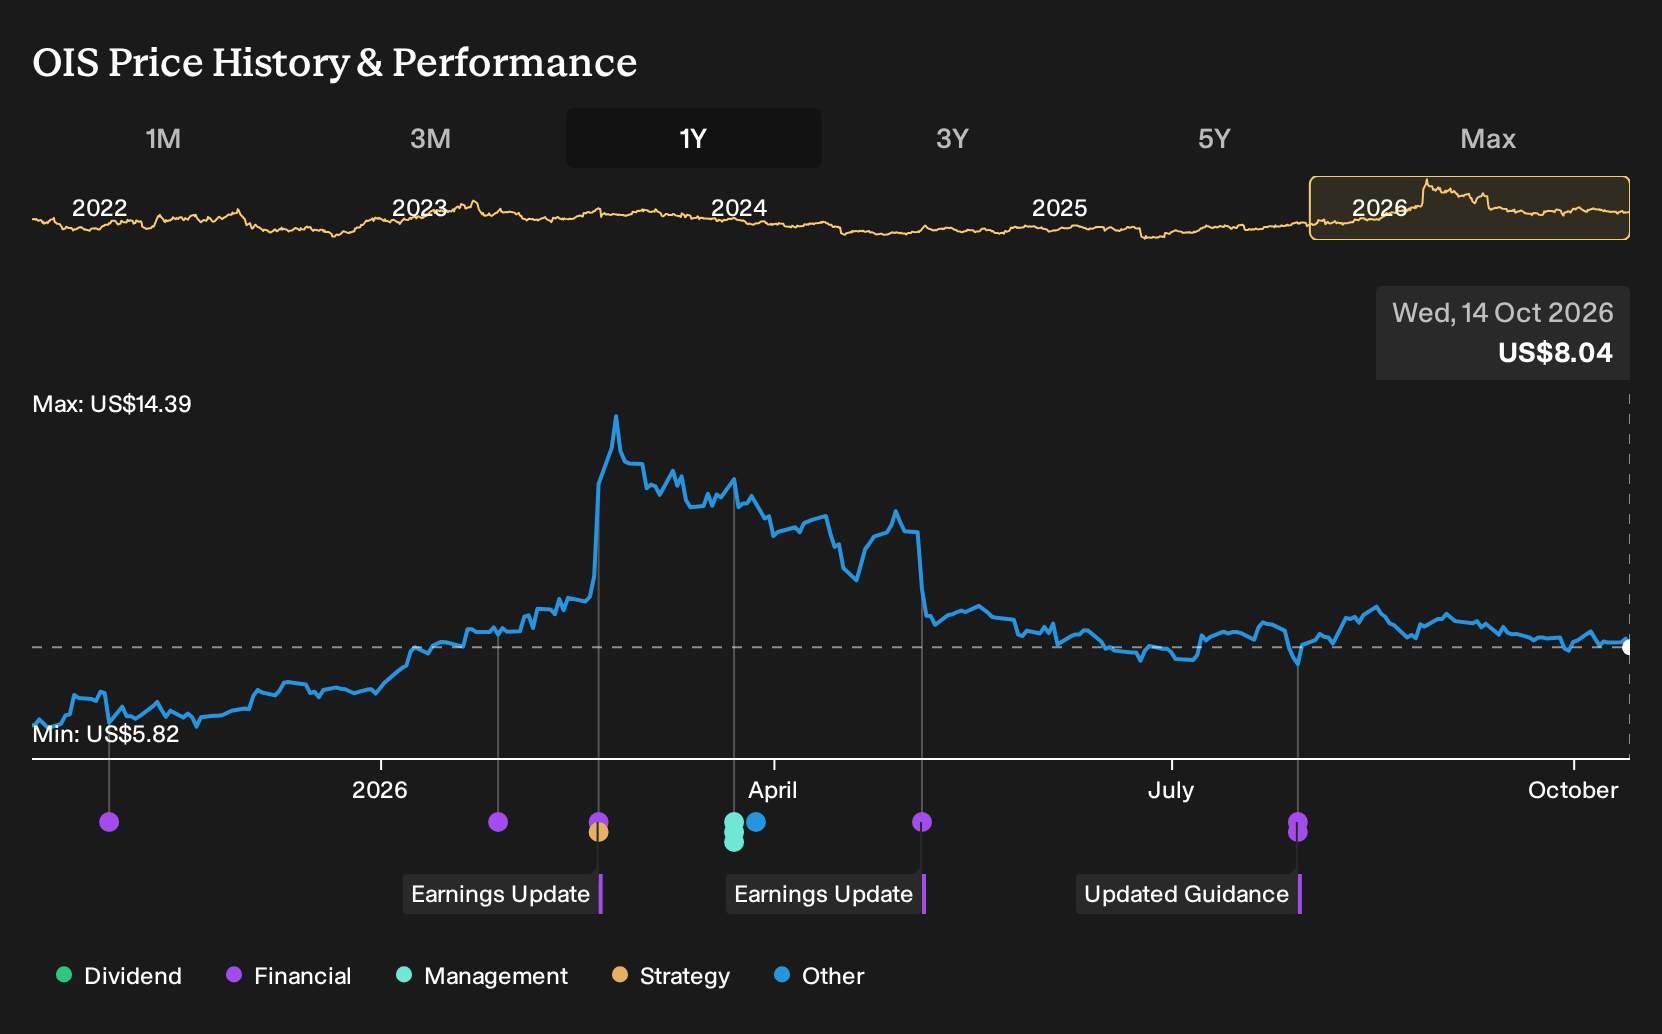
If Oil States International had been on your watchlist instead of in your account, watching the last year unfold might feel expensive. Holding Oil States International over the past year would have returned 32.7%, including dividends. That outcome invites a harder question. If analysts were already split between offshore growth potential and ESG driven demand risk when the period began, what clues in the business mix toward long cycle international projects could have helped you judge which assumption mattered more?
Oil States International has already moved. See which of 32 high quality undervalued stocks still trade below our estimates.
The Two Oil States International Stories Investors Had To Weigh
The shares cost US$5.91 at the start of the period, so any view on Oil States International had to start with what that price already assumed.
The bullish story argued that offshore and international exposure could widen the company’s reach, with a Fair Value of US$6.88 that reflected a price level implied by assumed revenue growth of 4.9% a year and rising profit margins.
The bearish view pointed to rising ESG policies and oilfield oversupply as long term threats, with a Fair Value of US$5.50 based on 4.6% assumed annual revenue growth and a 5.3% profit margin.
What The Results Changed For Oil States International
The clearest new fact was the Q2 2026 result. Oil States International reported revenue of US$156.659m against US$165.406m a year earlier, while net income rose from US$2.708m to US$5.704m and net margin moved from 1.6% to 3.6%. That mix of lower sales and higher profitability affected both the earlier bull and bear stories.
The lesson here is simple. When a thesis leans on margin expansion, track net margin first, then check whether revenue is carrying its weight or profitability is doing all the heavy lifting.
What Oil States International's Price Now Demands You Believe
With Oil States International at US$8.04, this selected Narrative places its fair value above that level and frames the recent move as only part of the story.
The Narrative leans on offshore megaproject exposure, technology-heavy products, and restructuring. It argues today’s price still does not credit the durability of premium margins from that offshore backlog and footprint.
"Analyst consensus points to multiyear offshore and international project exposure driving revenue growth, but this may understate the true opportunity, as OIS's record offshore backlog combined with industry momentum in long-cycle global megaprojects positions the company for several years of accelerating double-digit revenue and EBITDA growth, potentially well above current market expectations."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 47% below our estimate - taps online gambling migration using proprietary tech and more efficient marketing spend.
- Company 2 - 42% below our estimate - converts specialized scientific talent into project based consulting on regulatory and safety problems.
- Company 3 - 49% below our estimate - wins long duration data center groundwork tied to mission critical e-infrastructure projects.
That is three of the list. See every one of the 25 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com