


How Investors May Respond To Home Bancshares Stock Earnings Beat
- Home BancShares reported Q3 2026 net interest income of US$241.99m and net income of US$129.45m, with net loans charged off of US$2.15m, compared with US$2.92m a year earlier.
- Revenue of US$288.44m missed forecasts, while earnings per share of US$0.65 beat expectations. This suggests that cost discipline and credit performance helped offset a softer top line and higher non performing assets.
- The focus now shifts to how Home BancShares' stronger than expected earnings per share may influence the longer term investment narrative.
Scan how Home BancShares' mix of revenue softness and earnings resilience compares with peers by checking which regional lenders make it into our 32 resilient stocks with low risk scores today.
Home BancShares Investment Narrative Recap
To own Home BancShares, you need to be comfortable with a story built on disciplined credit, tight cost control and measured expansion rather than rapid balance sheet growth. The latest quarter fits that script. Net interest income and net income were higher than a year ago, and net loan charge offs were lower, so the near term earnings profile did not materially change.
The more immediate swing factor is still loan and deposit pricing. Revenue came in softer than expected, which keeps attention on how Home BancShares manages volume versus margin. The key operational risk remains volatile loan demand and competitive funding costs, which could pressure net interest income if pricing competition intensifies.
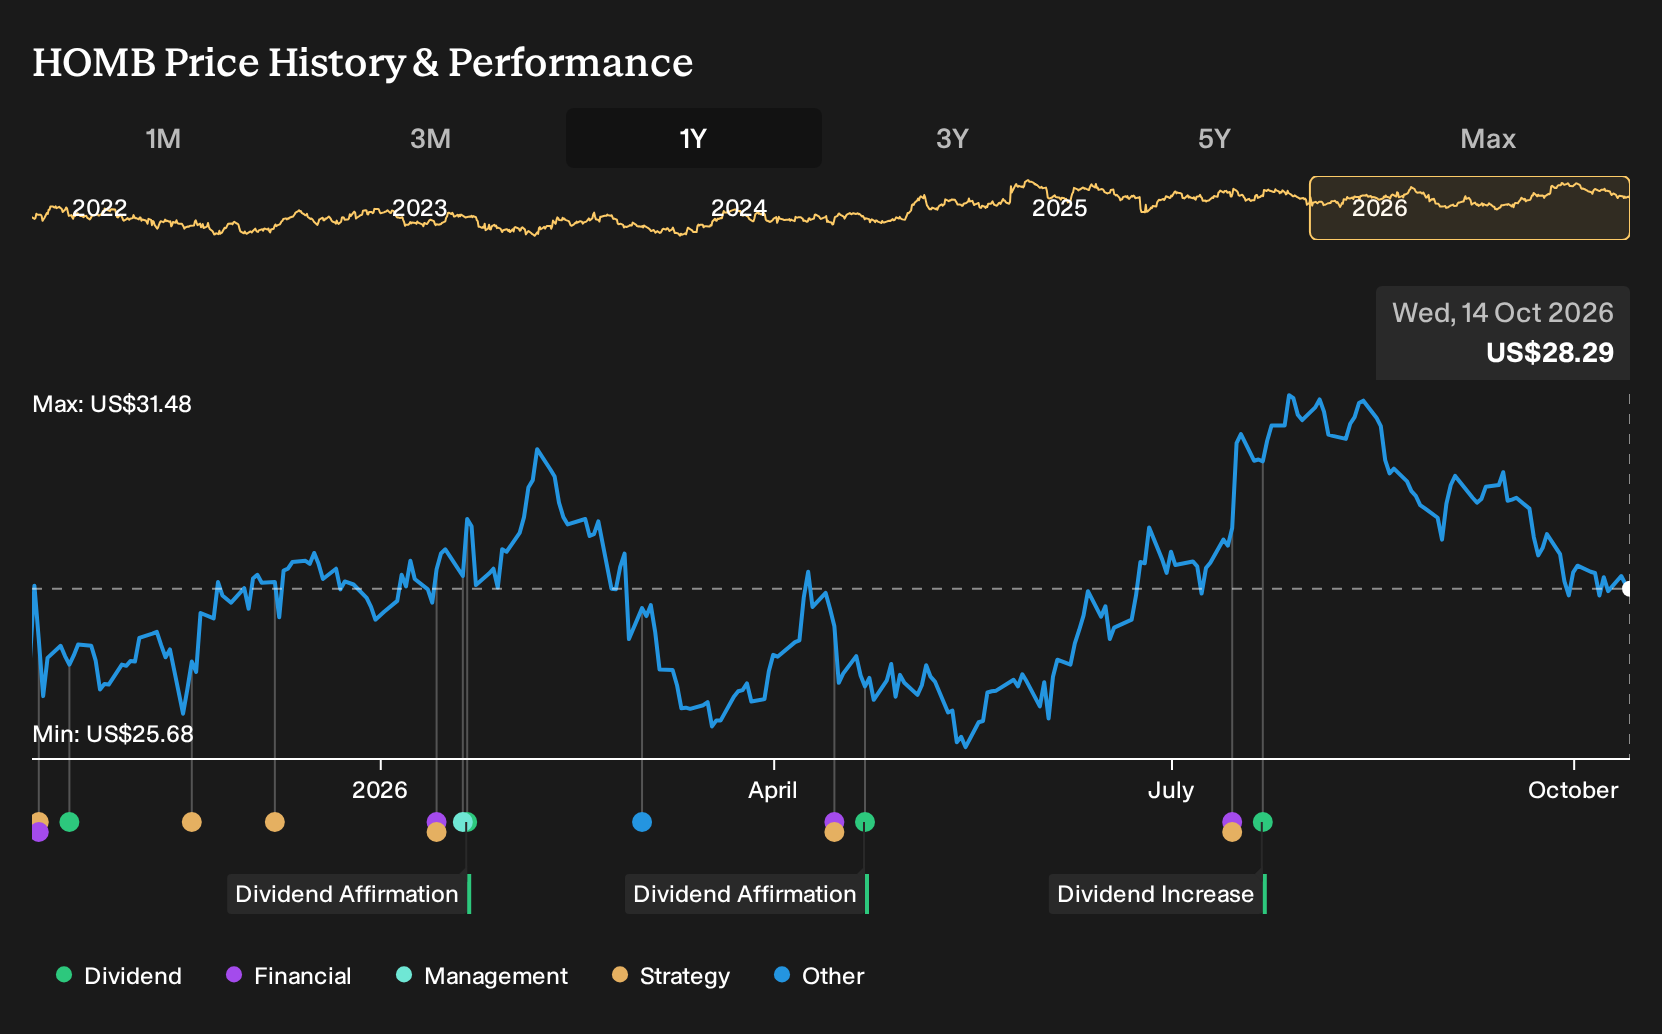
The most relevant update for this quarter is the earnings release on 14 October 2026. Home BancShares reported Q3 revenue of US$288.44m, which missed expectations, while earnings per share of US$0.65 came in ahead of forecasts. Net interest income of US$241.99m and net income of US$129.45m were above the prior year, with net loans charged off at US$2.15m.
That mix supports the near term catalyst around efficiency and credit execution. Cost discipline and credit quality helped offset softer revenue and higher non performing assets, which keeps attention on how the bank executes the Mountain Commerce Bank integration and maintains its targeted core net interest margin range. For investors, the operational question is whether this earnings resilience can be sustained if loan growth or funding competition becomes more challenging.
Home BancShares' narrative projects US$1.3b revenue and US$537.3m earnings by 2029, based on analyst forecasts. This implies 5.0% yearly revenue growth and an earnings increase of about US$57.9m from current earnings of US$479.4m.
Uncover how Home BancShares' fair value indicates an 18% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Home BancShares now faces a wide spread of fair value opinions from the Simply Wall St Community, with estimates spanning roughly US$33 to just over US$48 across 2 independent views. That gap sits against real execution questions around acquisitive growth, funding competition and loan volatility, so you are prompted to test several contrasting angles before deciding how compelling the story looks.
Explore another Home BancShares fair value estimate, including one that suggests it could be worth just $33.25.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Home BancShares research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Home BancShares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Home BancShares' overall financial health at a glance.
Looking for more Home BancShares investment ideas?
If Home BancShares has sharpened your thinking about bank earnings, you can use that momentum to assess a wider field of listed companies with clear, data driven filters.
- For investors who care most about resilience, start with a 32 resilient stocks with low risk scores and see which businesses score well on stability and downside protection.
- If value is your main focus, use the 32 high quality undervalued stocks to identify companies where fundamentals and current pricing may differ.
- Income focused investors can look for dependable cash returns by scanning a curated 7 dividend fortresses that highlights higher yielding payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com