


What Kinnevik (OM:KINV B)'s Bigger Nine Month Loss Means For Shareholders
- Kinnevik AB reported third quarter 2026 net income of SEK 218 million, with basic and diluted earnings per share of SEK 0.79, while the nine month period showed a net loss of SEK 6.034b and a loss per share of SEK 21.79.
- The sharp contrast between a profitable third quarter and a much larger loss over the first nine months highlights how the timing of portfolio valuation movements and exits can heavily sway Kinnevik’s reported earnings profile.
- We will look at how Kinnevik's investment narrative is tested by the swing to a SEK 6.034b loss over nine months.
Compare Kinnevik’s earnings swings with other listed investors under pressure from valuation marks by scanning our hand picked list of solid balance sheet and fundamentals (202 results) for potential alternatives in the same space.
Kinnevik Investment Narrative Recap
Kinnevik stock asks you to believe in its portfolio of high growth, tech enabled assets rather than smooth quarterly earnings. The recent SEK 218 million profit in Q3 sits against a SEK 6.034b loss over nine months, so the near term story still revolves around valuation marks, exits and currency swings rather than steady profitability.
The key short term catalyst is how quickly underlying holdings convert revenue traction into clearer paths to positive EBITDA and funding self sufficiency. The biggest risk right now is that further FX pressure and multiple compression in software and health assets keep dragging reported net asset value and earnings even when portfolio operations improve.
The latest quarterly report is the most relevant development for that thesis because it shows both sides of Kinnevik’s model in one set of numbers. A single quarter in the black with earnings per share of SEK 0.79 does not offset a SEK 21.79 loss per share year to date, so timing effects remain front and centre.
For catalysts, attention goes to where those fair value moves are coming from, particularly AI enabled software, travel platforms and U.S. digital health. Any evidence in upcoming updates that companies like TravelPerk, Mews, Spring Health or Cityblock are scaling with better unit economics will matter more for the long term narrative than whether Kinnevik reports another profitable quarter.
Kinnevik earnings assumptions in context
Kinnevik's analyst narrative projects SEK 2.6 billion of revenue and SEK 2.6 billion of earnings by 2028. These figures are based on an assumption of roughly 149.4% yearly revenue growth and an earnings increase of about SEK 2.5 billion from SEK 124.0 million today.
Uncover why Kinnevik's fair value indicates a 45% potential upside to its current price that could narrow quickly.
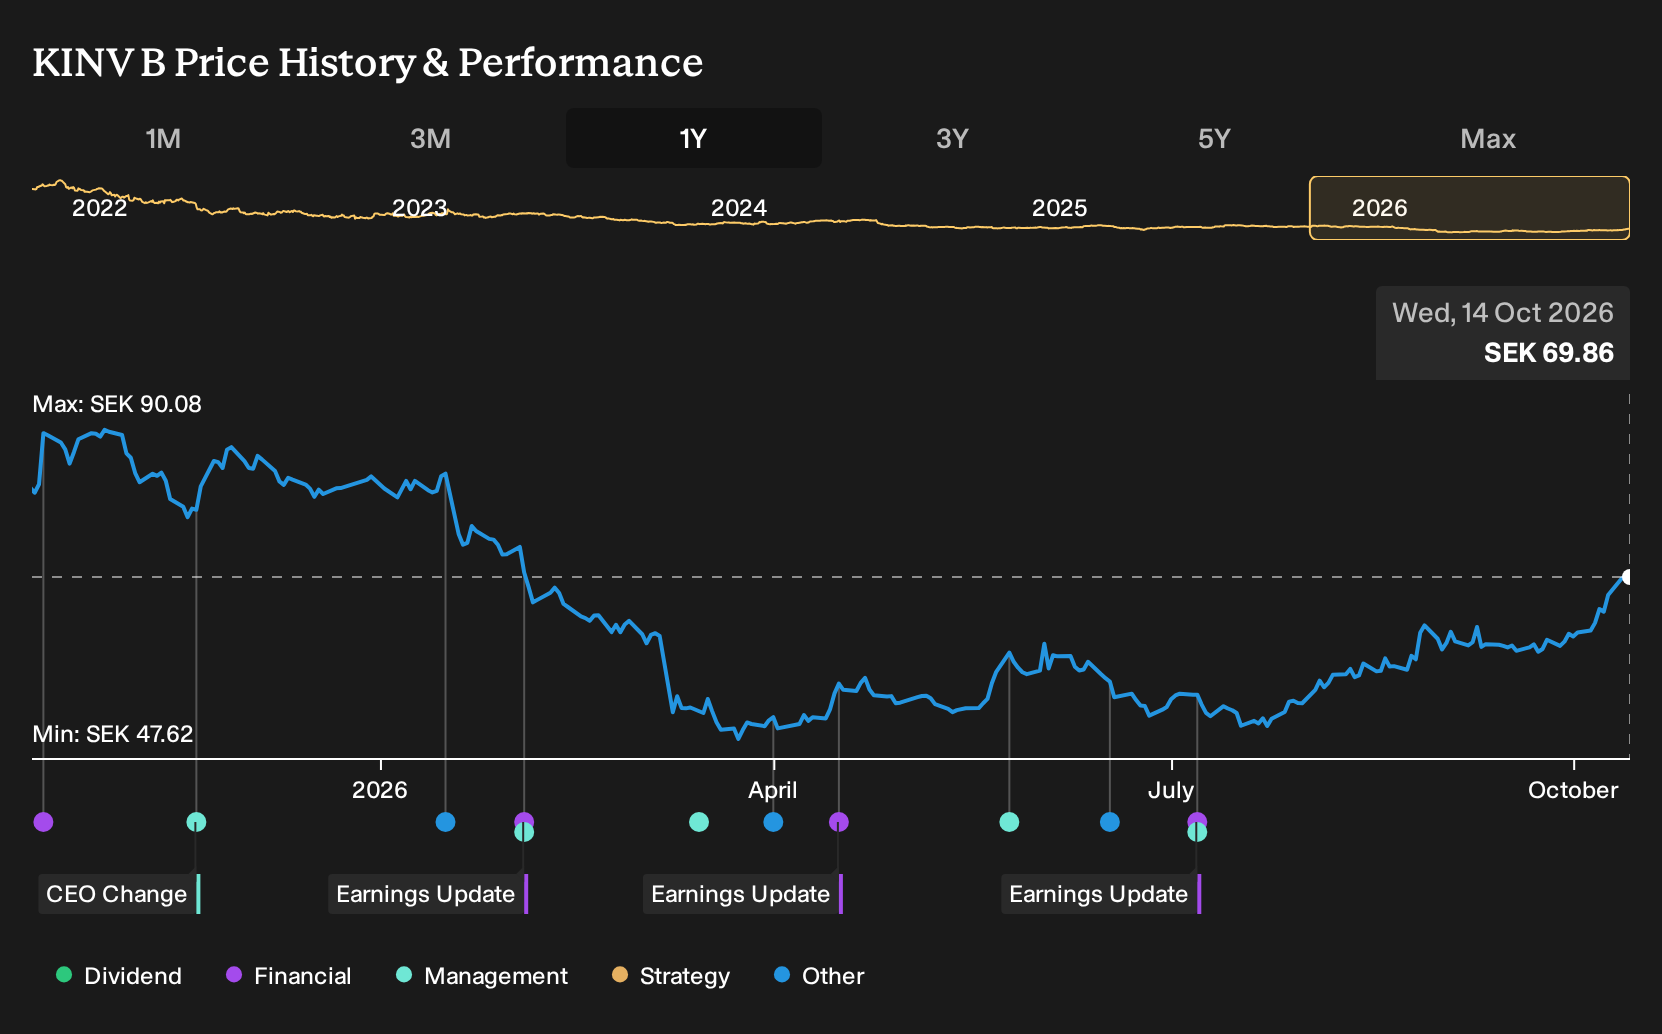
Exploring Other Perspectives
One alternate angle on Kinnevik leans hard into Oviva and digital health as a potential accelerator. The most optimistic analysts were pencilling in revenue growth of 153.8% a year and earnings of about SEK 2.7b by 2029 before this earnings release. That is a much brighter story than consensus, and it may shift as you see how these fresh Q3 numbers land.
Explore 2 other Kinnevik fair value estimates, including one that suggests the potential for up to 66% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Kinnevik research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kinnevik. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Kinnevik's overall financial health at a glance.
Looking for more investment ideas beyond Kinnevik?
Once you have a clear view on Kinnevik, it can help to compare that thesis against a wider field of opportunities using the Simply Wall St Screener.
- If capital preservation is high on your list, start with a basket of companies that score well on resilience and balance sheet strength through our 223 resilient stocks with low risk scores.
- If you prefer to cast a wider net for quality at a reasonable price, broaden your watchlist with the 613 high quality undiscovered gems that combine solid fundamentals with quieter market attention.
- If dependable cash returns appeal to you, focus on businesses with stronger income profiles by scanning our hand picked 217 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com