


P/F Bakkafrost (OB:BAKKA) After Q3 Production Update Is The Undervalued Story Still Intact
P/F Bakkafrost (OB:BAKKA) has released third quarter 2026 production figures, reporting harvest volumes of 23,100 tons in the Faroe Islands and 4,500 tons in Scotland, giving investors fresh insight into operational scale.
That production update lands after a mixed stretch for P/F Bakkafrost’s investors, with the share price at NOK442.2 and a year to date share price return down 14.55%, while the 1 year total shareholder return has fallen 6.43%. This points to fading momentum despite only modest short term gains.
Scan how P/F Bakkafrost stacks up against other potential opportunities by reviewing a curated 196 high quality undervalued stocks that combines cash generation with balance sheet strength.
P/F Bakkafrost now trades lower after a weak run, but the company is still producing at scale in both the Faroe Islands and Scotland. Do current expectations leave enough upside to justify taking on the risks?
Most Popular Narrative: 9% Undervalued
With P/F Bakkafrost closing at NOK442.2 against a widely followed fair value estimate of NOK484.28, the narrative frames the shares as trading at a discount while hinging on execution in both the Faroes and Scotland.
The program to increase smolt size and volume in the Faroe Islands, supported by expanded hatchery capacity and larger, more robust fish, is already linked to lower ring side farming costs per kilo. It also sets P/F Bakkafrost up for shorter sea cycles that may support future margin resilience and earnings stability.
See why 4 investors see P/F Bakkafrost as 9% undervalued.
Result: Fair Value of NOK484.28 (UNDERVALUED)
Still, the weak Scottish farming results and higher marine feed ingredient costs could easily pressure P/F Bakkafrost’s margins and challenge the 9% undervaluation story.
Find out about the key risks to this P/F Bakkafrost narrative.
Another View: What P/E Says About P/F Bakkafrost
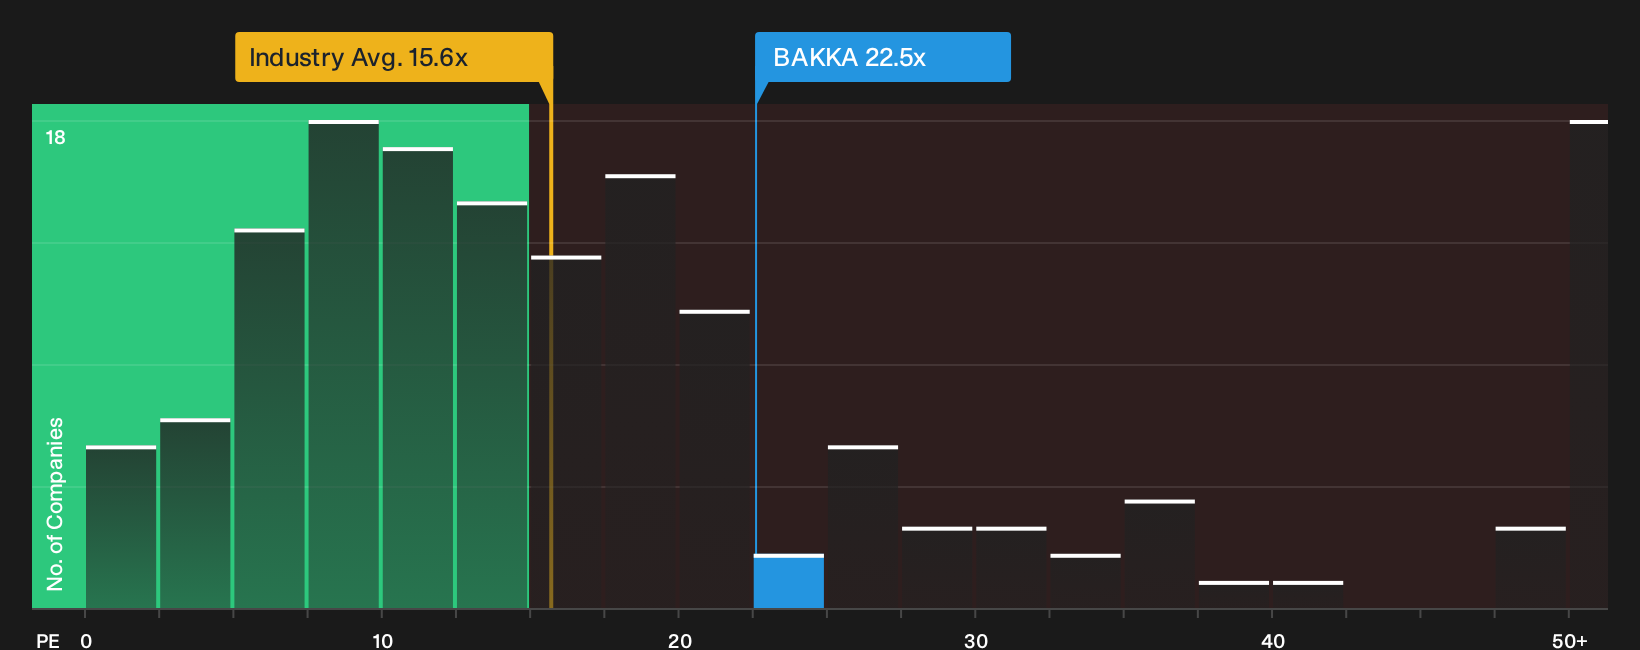
There is a different signal when you look at P/F Bakkafrost through its P/E. The shares trade at 22.5x earnings, above the European Food group on 15.7x and above an estimated fair ratio of 21.5x, which points to less of a clear bargain and more valuation risk if expectations slip.
See what the numbers say about this price and how the market could move closer to the fair ratio in our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed signals around P/F Bakkafrost leave you torn, use that unease as a prompt to interrogate the data yourself and move quickly while sentiment is still forming. Then weigh those concerns against the potential upside by reviewing the 3 key rewards.
Looking for more investment ideas beyond P/F Bakkafrost?
Do not stop with P/F Bakkafrost. Broaden your watchlist now so you are not relying on a single story when the next opportunities line up.
- Target steadier potential by focusing on resilient businesses in a 223 resilient stocks with low risk scores that may better match your appetite for smaller drawdowns.
- Hunt for value by scanning a curated 196 high quality undervalued stocks where cash generation and pricing look more attractive on current metrics.
- Seek reliable payout potential with a 217 dividend fortresses that filters for income ideas offering higher yields with a focus on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com