


SpaceX Stock Could Jump 62%. Is Elon Musk’s AI Bet a Golden Opportunity or Costly Gamble?
SpaceX (SPCX) just got a fresh vote of confidence from Wall Street. Barclays analyst Anthony Valentini initiated coverage with an Overweight rating and a $254 price target. That implies a hefty 62% upside from the stock's current price around $156.
The call came just days after the company's Starship rocket successfully launched 26 Starlink satellites into orbit for the first time. Pressured by downgrades from analysts and setbacks in engineering, this stock trades well below its IPO peak, yet it continues to draw fresh investor interest.
However, is this space stock ready for lift-off, or is the valuation too hot to handle? Let's try to find out the answer in this article.
SpaceX Stock Has More Room to Recover
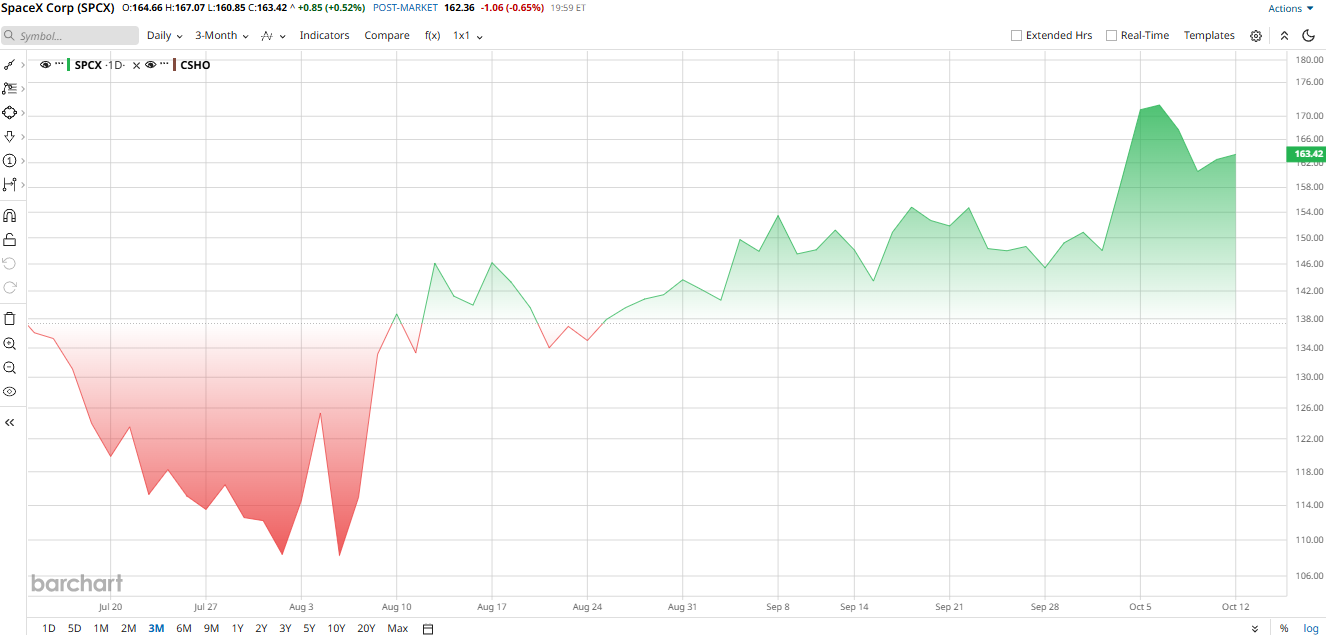
Since going public on June 12 at $135, SpaceX stock has had a bumpy ride. The stock reached a closing level around $163 in early October, about 20% higher than its IPO price but near its $225 52-week high. In the past three months, shares are up nearly 12%, simply indicating that investor attitudes are beginning to improve.
Several factors have aided recovery. The launch of Starship, which completed its orbital mission, revealed progress toward even more powerful flying events, and the company's proposed $8 billion spectrum buy has created another growth opportunity. But investors are still worried about SpaceX's big investment in AI machines. Amazon's stock plunged 12% in a single day after its debut as a public company, sending the share price down in line with the equally ambitious investments that the e-commerce giant made.
It has grown, but is not a bargain stock. The shares are well valued at approximately 41 times forecast 2026 revenue and 68 times trailing sales. The technology group has an average P/S ratio of 8, while the S&P 500's ($SPX) P/S average is 2.6.
Many factors contribute to SpaceX's premium, including its competitiveness in the satellite connectivity, launch services, and AI markets. Today's valuation may be easier to justify if the company is really experiencing fast revenue growth and is making "regular" profit out of its investments.
Starship and Starlink Could Unlock New Revenue
SpaceX's biggest strength is that it can bind a rocket launch to a growing business that handles satellites. On Sept. 28, Starship proceeded to make its first orbit-looping trip, placing 26 Starlink V3 satellites in Earth's orbit, which was an important step toward the company's launch ambitions.
A superior Starship could become capable of sending larger satellites to orbit at $100 million or less per flight. That would boost SpaceX's capability to handle more customers and, potentially, future orbital data centres. Getting to orbit is just the beginning, though, and the launch of a viable reusable system and commercial operations have yet to be proven.
SpaceX is also aggressively expanding the number of satellites it launches to bring internet to society. The proposed purchase of the 800 MHz spectrum holdings across the country by Grain Management, valued at $8 billion, would enable it to bring satellite-to-device connectivity and even enter wireless services, if approved by the regulators. This may provide another income stream and increase pressure on traditional telecom firms.
Meanwhile, American Airlines (AAL) is ready to roll out Starlink internet service to over 1,000 mainline aircraft, starting in 2027. That's another chance for SpaceX's satellite network to become a sustainable revenue stream.
Revenue Is Surging, but Spending Remains a Risk
SpaceX's second-quarter 2026 results, released in August, showed impressive growth. Revenue climbed 92% year over year to $7.81 billion, beating the approximately $6.72 billion analysts expected. The company also reported a loss of $0.09 per share, narrower than the consensus estimate of a $0.26 loss. SpaceX therefore beat expectations on both revenue and EPS, even though it remained unprofitable.
Connectivity revenue rose 66% to $4.29 billion, while AI revenue surged 247% to $2.56 billion. Space revenue increased 29% to $962 million. Adjusted EBITDA reached $3.54 billion, up 191%, while the net loss narrowed to $541 million from $2.04 billion a year earlier.
Management also guided for approximately $13 billion in third-quarter revenue and earnings of $0.13 per share. For the full year, analysts expect revenue of around $45.26 billion. These projections suggest that growth could continue, but the company's heavy AI and Starship investments could still weigh on profitability and cash flow.
Wall Street Remains Bullish on SpaceX Stock
Analysts are mostly bullish, but price targets vary wildly. Morgan Stanley's Adam Jonas reiterated a Buy rating with a $300 target, calling the stock a cheap way to play the space and intelligence economy. Goldman Sachs raised its target to $230 from $220, citing stronger AI expectations. Pivotal Research bumped its target to $230. Barclays set a Street-high among recent initiates at $254.
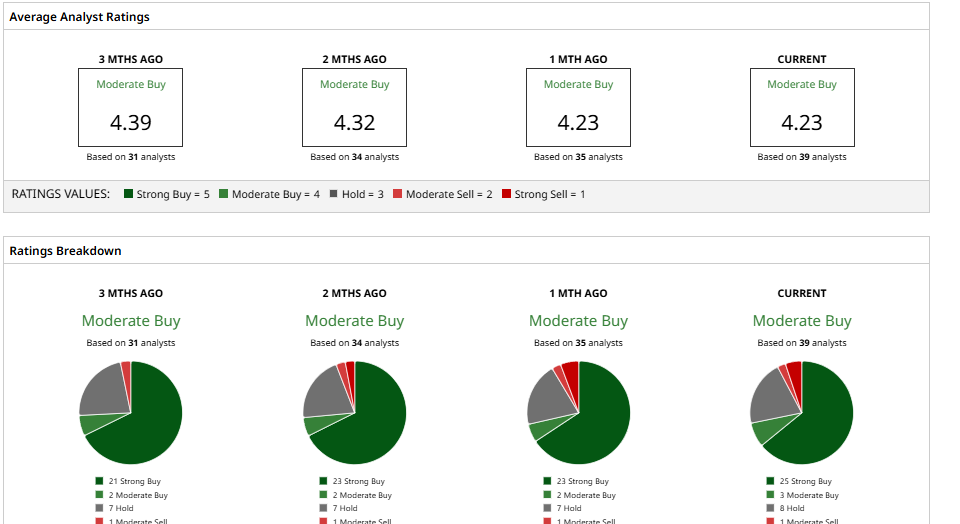
Overall, the consensus rating is a “Moderate Buy” with a mean price target of $225. That suggests upside of over 44% from current levels. Of the 39 analysts covering the stock, 25 rate it as “Strong Buy.” But not everyone is convinced. The bear case centers on the lack of profitability and the billions being burned on AI infrastructure.
The bull case is based on Starlink's expansion, Starship's ability to bring down the costs of launching, and SpaceX's increased ambitions in the field of artificial intelligence. However, there's downside potential as the stock's valuations and spending needs remain robust. SpaceX isn't an investment that deals with instability well, but for those willing to endure it, the future certainly has potential. However, it might be better at this point to stay out of the stock for those who pursue a conservative investing strategy.
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.