


Learn Why The Bull Case For Telia Company Stock Could Change Following Job Cuts Plan
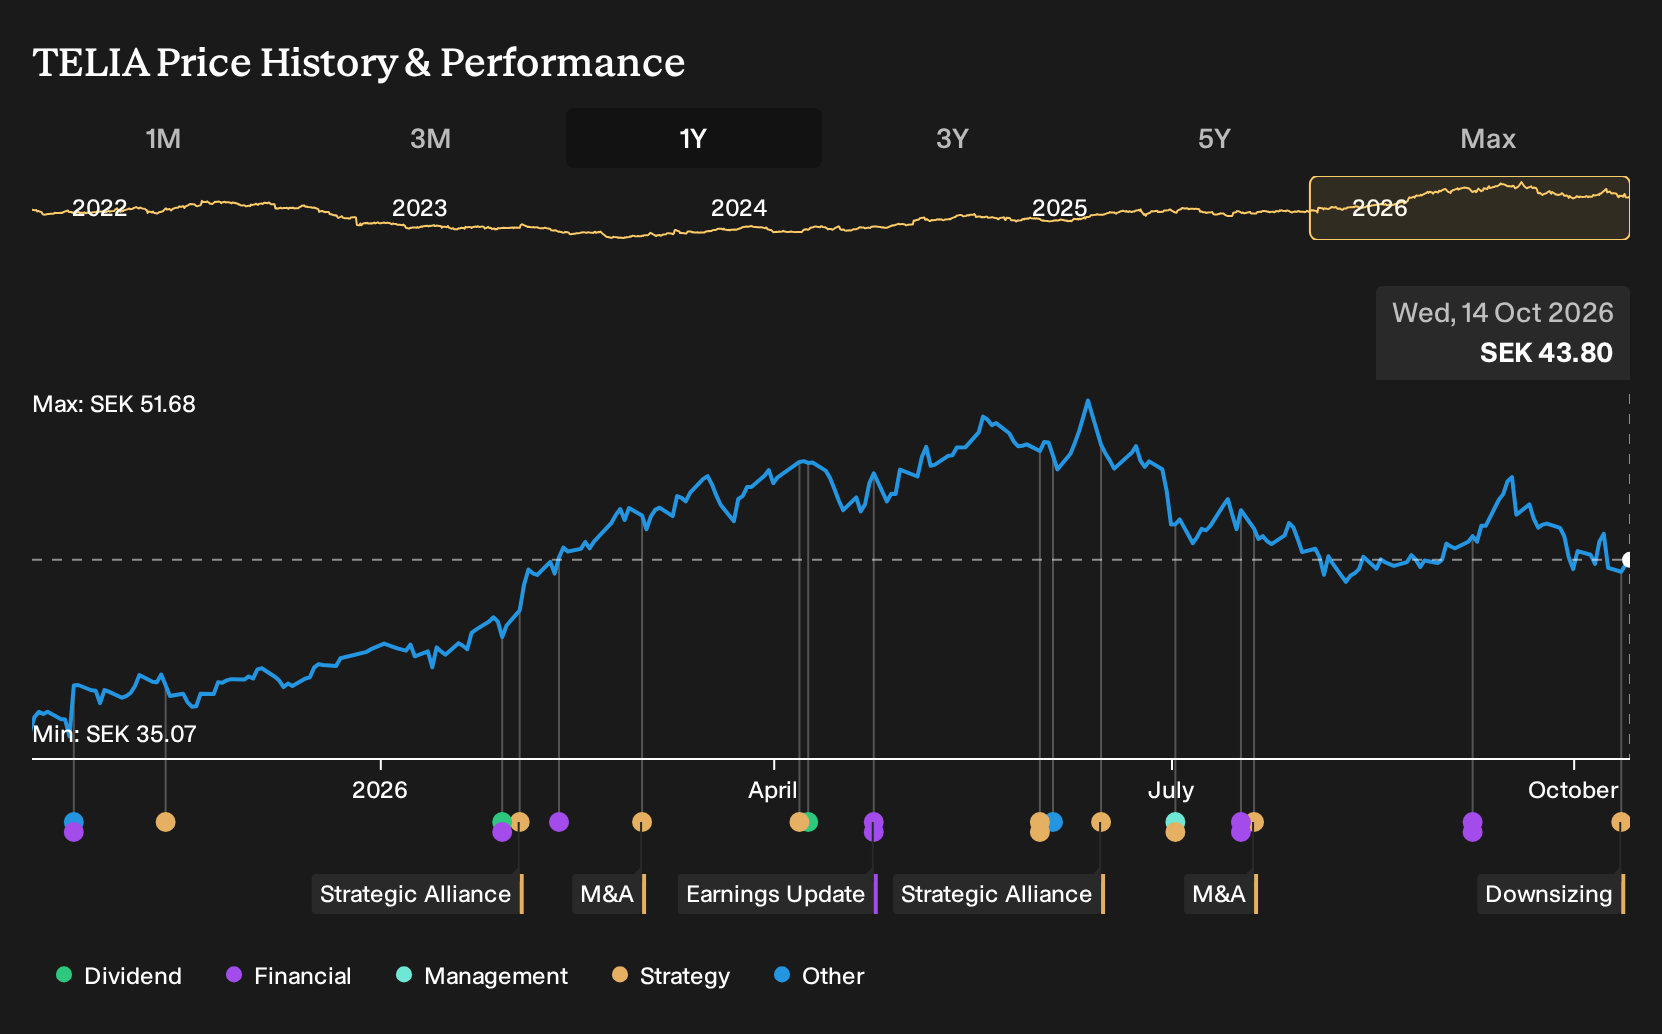
- Telia Company has launched a restructuring plan that includes reducing about 900 positions across the Nordics and Baltics and targeting SEK 1b in annual gross operating cost savings, with most restructuring charges of roughly SEK 600m booked in Q4 2026 and cash effects mainly in 2027.
- The plan shifts roughly 220 roles from the central Technology unit into country teams, signaling a push toward more local execution while still pursuing a lower cost base across Sweden, Finland, Norway and the Baltic markets.
- We will explore how Telia Company's investment narrative evolves as management pursues SEK 1b in annual cost savings through this restructuring.
Compare Telia Company's restructuring push with other operators reshaping their cost base and earnings mix by scanning our curated list of list of solid balance sheet and fundamentals (202 results)
Telia Company Investment Narrative Recap
For Telia Company to make sense in a portfolio, you need to believe the core Nordic and Baltic connectivity business can keep supporting steady broadband and mobile demand while cost efficiencies lift cash generation over time. The restructuring fits that story by targeting SEK 1b of gross annual savings, although the main free cash flow benefit is expected only once the program is fully embedded.
In the near term, the key catalyst is still operational improvement in weaker areas like Norway and competitive Finland. The job cuts and localization plan may help execution, but the impact on earnings mix and group margin will depend on how quickly savings offset restructuring charges and any disruption from removing roughly 900 positions.
The most relevant context for this restructuring is Telia Company's ongoing portfolio reshaping toward higher margin connectivity, including prior moves around non core markets and the Bredband2 acquisition. Management is trying to align the cost base with that leaner footprint, while keeping enough local capability to support broadband, mobile and converged household offers.
For you as an investor, the link to catalysts is direct. Cost programs, 5G and mission critical connectivity, and converged bundles all rely on stable execution in Sweden, Finland, Norway and the Baltics. The headcount reduction and transfer of about 220 technology roles into country units could either sharpen that delivery or, if mishandled, amplify the existing risks around Norwegian losses and Finnish price pressure.
Telia Company's current analyst storyline points to SEK 87.2b in revenue and SEK 10.7b in earnings by 2029, built on 2.1% yearly revenue growth and an earnings increase of SEK 5.8b from SEK 4.9b today.
Uncover why Telia Company's fair value indicates a 6% potential upside to its current price before that discount closes.
Exploring Other Perspectives
One alternate view focuses on Telia Company's margin story. The most optimistic analysts were already modeling SEK 91.0b of revenue and SEK 12.8b of earnings by 2029, assuming tighter OpEx and richer free cash flow. You might see this restructuring as either reinforcing that upbeat path or forcing a rethink of those forecasts.
Explore 3 other Telia Company fair value estimates, including one that suggests as much as 167% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Telia Company research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Telia Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telia Company's overall financial health at a glance.
Looking for more investment ideas beyond Telia Company?
If Telia Company is only one piece of your watchlist, it can help to compare it with other businesses filtered for the traits you care about most, from resilience to income potential.
- For investors who want income that feels more reliable than a single dividend payer, start with a curated set of 217 dividend fortresses that focus on higher yields.
- If capital preservation is top of mind and you prefer steadier profiles, narrow your search to a 223 resilient stocks with low risk scores that screens well on resilience.
- If you like backing durable balance sheets that can weather tough cycles, build a watchlist from a list of solid balance sheet and fundamentals (202 results) and compare them side by side with Telia Company.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com