


V.F (VFC) Could Be 12% Undervalued Following Its Recent Rally
V.F (VFC) drew fresh attention after its shares climbed about 5% when Barclays cited improving momentum at Vans, The North Face, and Timberland. The firm also highlighted healthier inventories and stronger consumer engagement across key labels.
That Barclays comment arrives after a sharp short-term rebound in V.F, with a 7 day share price return of 14.6% and a 30 day share price gain of 26.1%, even though the share price is still down 9.3% year to date.
Spot emerging turnarounds alongside V.F by scanning our hand picked 20 high quality undiscovered gems list, which is built around companies with improving fundamentals and still under-the-radar sentiment.The sprint in V.F shares hints at more than a mood swing, with recent revenue and net income growth giving the move some grounding. The next step is to test whether today’s valuation really reflects that shift in the business.
Most Popular Narrative: 12% Undervalued
V.F last closed at $16.48, while the most followed narrative pegs fair value at about $18.77. The current price sits below that implied level and puts the focus squarely on how the turnaround story plays out from here.
The strategic focus on expanding higher-margin channels, including direct-to-consumer and e-commerce, is beginning to drive improved gross margins and deeper customer engagement, expected to lift both revenue growth and net margins over time as V.F. capitalizes on the sustained consumer shift toward digital and premium shopping experiences.
See why 49 investors see V.F as 12% undervalued.
That view uses an 11.01% discount rate and blends in expectations for earnings, margins, and risk to arrive at the $18.77 fair value mark, which sits around 12% above where V.F trades today. The assessment leans heavily on the idea that brand repair, channel mix, and cost work can support that trajectory, while also acknowledging tariff costs, leverage, and Vans pressure as meaningful constraints.
Result: Fair Value of $18.77 (UNDERVALUED)
Still, the story can break if Vans keeps dragging on group results, or if higher tariffs and leverage squeeze the financial room V.F needs to reset.
Find out about the key risks to this V.F narrative.
Another View: What V.F’s P/E Ratio Is Telling You
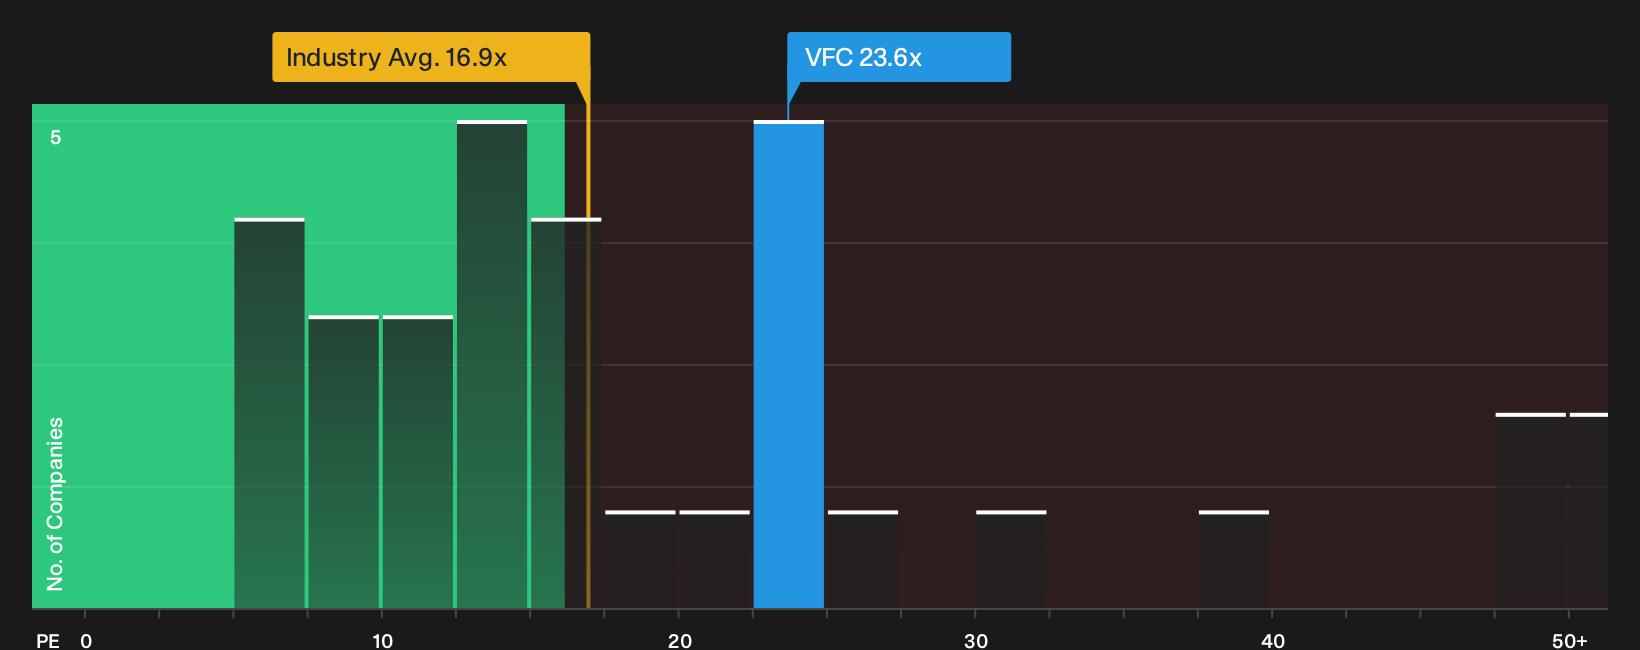
The SWS DCF work suggests V.F is undervalued, yet the simple earnings multiple paints a tighter picture. At a P/E of 23.6x, the stock trades above both peers at 19.9x and the US Luxury group at 16.6x, while still sitting a little below the 25.4x fair ratio. That gap hints at limited room for error. If earnings or sentiment wobble, this premium may start to feel uncomfortable for some shareholders.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this V.F setup feels finely balanced, move quickly from headline takes to the underlying numbers and stress test the story yourself with 3 key rewards and 3 important warning signs.
Looking for more V.F style investment ideas?
Do not stop with V.F. Use the Simply Wall Street Screener to quickly surface focused shortlists so you keep spotting opportunities before they are crowded.
- Target potential mispricing by scanning the 32 high quality undervalued stocks that combine stronger fundamentals with prices that still look beaten down on the surface.
- Prioritise resilience by reviewing the 32 resilient stocks with low risk scores that pair sturdier financial profiles with calmer risk scores.
- Lean into quality setups early by tracking our 20 high quality undiscovered gems that have cleaner balance sheets and improving metrics but limited market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com